
Personal Loans in South Africa – Borrow up to R350,000
Need flexible funding for life’s big moments or unexpected expenses? Personal loans in South Africa offer unsecured borrowing with structured repayments over an agreed term. Whether you’re in Johannesburg, Cape Town, or Durban, FatCat Loans connects you with NCR-registered credit providers offering personal loan options with structured repayment plans and transparent costs.
Submit one secure application, and we’ll match your profile with NCR-registered credit providers in our network. If a provider can make an offer, you will receive the loan amount, repayment term, interest rate, fees, and total cost of credit before deciding whether to continue.
Want to compare loan options before applying? Visit our Compare Loans South Africa hub to explore different types of loans and borrowing options.
Why Choose FatCat Loans for Personal Loans?
We make borrowing simple, fast, and stress-free for South Africans. Here’s why thousands trust us:
- NCR-Registered Credit Providers: Compare potential loan options from participating NCR-registered credit providers in our network. For more on online loans from these providers, explore our guide.
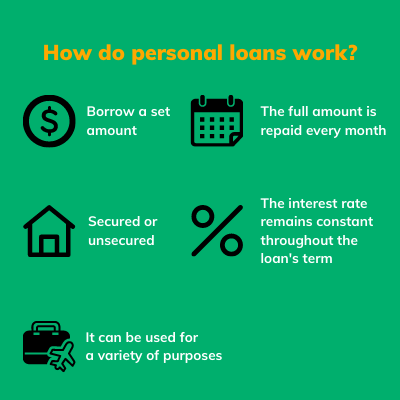
- Structured Repayments: Depending on the credit provider and loan offered, repayment terms may range from 6 - 72 months, with scheduled repayments that can make budgeting easier.
- Flexible Use of Funds: Personal loans can be used for a wide range of expenses, such as home renovations, medical bills, education costs, debt consolidation, or travel, subject to the terms of your credit agreement.
- Online Application: Apply online and, if matched, have your application assessed by a participating credit provider. Approval and payout times vary by lender and depend on affordability checks, verification, supporting documents, and banking timelines.
Personal loans explained (South Africa)
This page explains how personal loans work, what affects approval, and how to borrow responsibly under the National Credit Act.
Personal Loan Key Facts
- Loan amounts: From around R1,000 up to R350,000, depending on the credit provider’s criteria.
- Repayment terms: Usually 6 to 72 months, depending on the loan amount and lender.
- Approval checks: Credit providers assess income, expenses, existing debt, banking history, and affordability.
- Payout method: Approved funds are usually paid by EFT into your South African bank account.
- Before accepting: Always review the interest rate, monthly instalment, fees, repayment term, and total cost of credit.
What Can You Use a Personal Loan For?
Personal loans can be used for many different one-off expenses. The right loan amount and repayment term will depend on why you are borrowing, what you can afford each month, and how quickly you want to repay the debt.
Common uses include:
- Debt consolidation: Combining qualifying debts into one structured monthly repayment. Before consolidating, compare the new loan's interest, fees, repayment term, and total cost against the debts you are replacing.
- Home repairs or improvements: A personal loan can provide a fixed amount for planned repairs, renovations, or essential maintenance without using your home as security.
- Medical or dental expenses: Personal loans may help spread an unexpected healthcare cost over a structured repayment period.
- Education and school costs: Borrowing may help with education-related costs where the repayments comfortably fit your budget.
- Vehicle repairs: An unexpected repair bill can sometimes be financed with a personal loan rather than using revolving credit.
- Moving costs: Deposits, transport, and other relocation expenses can create a large one-off cost.
- Major purchases: A fixed loan may be easier to budget for than revolving credit when paying for a necessary larger purchase.
- Unexpected expenses: Personal loans may be considered for genuine emergencies where savings or another lower-cost option are not available.
A personal loan is generally better suited to a defined one-off expense than repeatedly covering normal monthly living costs. If you are borrowing regularly for groceries, rent, electricity, or other everyday expenses, another loan could increase financial pressure rather than solve the underlying shortfall.
If your main goal is reducing or simplifying existing debt repayments, compare our debt consolidation loans before deciding.
Why Compare Personal Loans Before Applying?
Two credit providers can assess the same applicant differently and may offer different loan amounts, interest rates, repayment periods, and fees. That makes comparison particularly useful before committing to a personal loan.
For example, one offer may have a lower monthly instalment because the loan is spread over a longer period. Another may require a higher monthly repayment but cost less overall because the debt is repaid sooner.
When comparing personal loan offers, look at:
- The amount you will actually receive
- The interest rate
- Initiation and monthly service fees
- The repayment period
- The monthly instalment
- The total amount repayable
- Whether the repayment comfortably fits your existing budget
Don't assume the first offer, the largest loan amount, or the smallest monthly instalment is automatically the most suitable option.
Use our Compare Loans South Africa hub if you want to review different loan types and borrowing options before applying.
Before You Apply for a Personal Loan
Before applying, work out how much you actually need and what monthly repayment your budget can comfortably support. You can estimate repayments first with our loan calculator.
It is also worth considering whether another type of borrowing better matches your needs. If you want to combine existing debts into one repayment, visit our debt consolidation loans page. For smaller or more urgent borrowing needs, compare instant loans, same-day loans, or emergency loans.
What Interest Rates Can You Expect on a Personal Loan in South Africa?
Personal loan interest rates in South Africa vary between credit providers and borrowers. The rate you are offered will depend on the credit provider's assessment of your application and may be influenced by factors such as your credit profile, income, existing debt, repayment history, loan amount, and repayment term.
This means two people applying for the same personal loan amount may receive different interest rates. A lower advertised or starting rate does not necessarily mean that every applicant will qualify for that rate.
When comparing personal loan rates, don't look at the interest rate alone. Also compare the initiation fee, monthly service fees, repayment term, monthly instalment, and total cost of credit. A loan with a lower monthly repayment can still cost more overall if it is repaid over a longer period.
Before accepting a personal loan, check the interest rate and all other borrowing costs shown in the credit provider's pre-agreement statement and quotation.
What Does a Personal Loan Cost in South Africa?
The cost of a personal loan depends on the loan amount, repayment term, interest rate, initiation fee, monthly service fee, and your affordability assessment. A lower monthly repayment can sometimes mean a longer term and a higher total cost, so it is important to compare the full cost of credit rather than only the instalment.
Before you accept any offer, the credit provider should give you a clear quotation showing the amount borrowed, interest, fees, number of instalments, monthly repayment, and total amount repayable.
Illustrative example: A R30,000 personal loan repaid over 36 months will have different monthly repayments and total costs depending on the interest rate and fees charged by the credit provider. Use our loan calculator to test different interest rates and repayment terms, and always rely on the credit provider's pre-agreement statement and quotation for the actual cost of your loan.
Your Pre-Agreement Statement and Quotation
Before entering into a credit agreement, South African consumers must be provided with a pre-agreement statement and quotation containing important information about the proposed credit.
This helps you understand key details such as the amount of credit, interest rate, fees, instalments, and total cost before you commit.
The quotation is valid for five business days, giving you time to review the proposed costs and terms before deciding whether to proceed.
Don't sign or accept a loan agreement you do not understand. If something in the quotation is unclear, ask the credit provider to explain it before proceeding.
For official information about credit agreements and consumer rights, visit the National Credit Regulator (NCR).
What is a Personal Loan?
A personal loan is an unsecured borrowing option, meaning you don’t need to put up your car, home, or other assets as collateral. Unlike revolving credit, a personal loan is generally repaid through scheduled monthly payments over an agreed term, which can make budgeting easier. In South Africa, personal loans may range from around R1,000 to R350,000, depending on your income, expenses, credit profile, and the lender’s affordability assessment.
Why go personal? They’re ideal for consolidating debt, funding big purchases, or handling emergencies without draining savings. Our matching service uses one application to look for potential loan options from participating NCR-registered credit providers in our network. Approval, loan amounts, interest rates, and repayment terms depend on the credit provider’s assessment.
What Lenders Usually Check Before Approving a Personal Loan
Approval is not based on one factor alone. In South Africa, lenders typically look at your income, existing monthly debt commitments, banking history, employment or income stability, and your credit profile. The aim is to assess whether the loan is affordable for you now and over the full repayment term.
To improve your chances of approval and help avoid delays, prepare the same details most lenders ask for:
- Your South African ID or valid identification details
- Recent proof of income or payslips
- Recent bank statements
- Your contact details and banking information
- A realistic loan amount and term that suits your budget
If you are worried about your credit profile, you can start with our free credit report page, read how to check and improve your credit score in South Africa, or compare options on our bad credit loans page.
Research Personal Loan Providers in South Africa
Want to learn more about individual credit providers before applying? Our lender guides explain how different South African loan providers work, including their application process, eligibility requirements, loan features, and important points to consider.
What Income Types May Be Accepted?
Credit providers usually need to confirm that you have regular income and enough disposable income to afford the repayment. Depending on the lender, acceptable income may include:
- Full-time or part-time employment income
- Self-employed income supported by recent bank statements
- Pension income
- Regular business or contract income
- Other recurring income that can be verified through bank statements
Not every credit provider accepts every income type. Eligibility and income-verification requirements vary between credit providers.
How to Apply for a Personal Loan Through FatCat Loans
Applying through FatCat Loans starts with one online application rather than completing separate forms for individual credit providers.
1. Complete the Online Application
Tell us how much you would like to borrow and provide the personal, income, and financial information requested. Make sure the information you provide is complete and accurate, as incorrect or missing information can delay the lender's assessment.
2. We Look for Potential Matches
FatCat Loans uses the information you provide to try to match your application with participating NCR-registered credit providers in our network. A match does not mean that a loan has been approved.
3. The Credit Provider Assesses Your Application
If your application is referred to a credit provider, that provider applies its own eligibility, credit, and affordability criteria. The lender may verify information such as your identity, income, bank statements, existing credit commitments, and repayment history.
4. Review Any Loan Offer
If a credit provider can make you an offer, review the quotation carefully. Check the:
- Approved loan amount
- Interest rate
- Initiation fee
- Monthly service fee
- Repayment amount
- Number of repayments
- Repayment dates
- Total amount repayable
5. Decide Whether to Accept
You are under no obligation to take a loan simply because an offer has been made. If you accept the lender's offer and complete its requirements, the credit provider will arrange payment according to its own processing and banking timelines.
FatCat Loans does not approve loans, issue funds, or determine your interest rate or repayment terms.
Personal Loans vs Other Borrowing Options
A personal loan is only one way to borrow. The right option depends on how much you need, why you need it, how quickly you can repay it, and what the credit will cost.
| Borrowing Option | How It Generally Works | May Be Worth Considering When |
|---|---|---|
| Personal loan | A lump sum repaid through structured instalments over an agreed period. | You need a defined amount and prefer predictable repayments. |
| Instalment loan | Credit repaid through scheduled instalments. | You want a structured repayment schedule over an agreed term. |
| Short-term loan | Usually a smaller loan with a shorter repayment period. | You have a temporary financial gap and can comfortably manage the shorter repayment period. |
| Same-day loan | Focuses on faster payout after the lender has approved the application. | The timing of an approved payout is particularly important. |
| Emergency loan | Borrowing intended for an unexpected urgent cost. | You face a genuine necessary expense that cannot reasonably wait. |
| Debt consolidation loan | May combine qualifying debts into one structured repayment. | You want to simplify existing debt and the new arrangement makes financial sense. |
These descriptions do not mean one option is automatically cheaper or easier to obtain than another. Compare the interest rate, fees, repayment term, affordability, and total amount repayable before deciding.
Learn more about instalment loans, short-term loans, same-day loans, emergency loans, and debt consolidation loans, or visit our Compare Loans South Africa hub.
Who Might a Personal Loan Be Suitable For?
A personal loan may be worth considering if you:
- Need a defined amount for a specific expense
- Prefer predictable scheduled repayments
- Want a clear repayment end date
- Can comfortably afford the instalment alongside your existing commitments
- Have compared the total borrowing cost with other suitable options
- Understand the terms of the credit agreement before accepting it
A personal loan may be less suitable if you:
- Are already struggling to meet existing debt repayments
- Need to borrow repeatedly for normal monthly living costs
- Would have very little money left for essential expenses after making the loan repayment
- Are taking the loan mainly because the maximum amount offered is attractive
- Have a cheaper realistic alternative available
The right loan is not necessarily the largest amount you can qualify for. It is an amount and repayment structure you can reasonably manage without putting unnecessary pressure on your budget.
If your existing debts are already becoming difficult to manage, consider getting information about debt counselling from the National Credit Regulator rather than automatically taking additional credit.
Your Rights When Taking Out a Personal Loan in South Africa
Personal loans are regulated by South Africa's National Credit Act (NCA), which provides protections for consumers entering into credit agreements.
Among other protections, you have the right to:
- Apply for credit: You have the right to apply for credit, although the credit provider is not required to approve the application.
- Request reasons for a decline: If your credit application is turned down, you can ask the credit provider to provide reasons.
- Receive clear information: Credit information and required documents should be provided in plain and understandable language.
- Receive a pre-agreement statement and quotation: This should disclose important information about the proposed credit before you enter into the agreement.
- Have your information treated confidentially: Personal information held about you must be handled in accordance with applicable requirements.
- Access and challenge credit information: You can access information held about you by a credit bureau and challenge information you believe is incorrect.
- Seek assistance if you become over-indebted: Debt counselling may be available where existing debt repayments have become unmanageable.
These protections do not remove your responsibility to provide truthful information when applying or to meet the repayments on a credit agreement you accept.
If a loan repayment is likely to be unaffordable, do not rely on approval alone as evidence that borrowing is right for your circumstances.
For independent information about consumer credit and your rights, visit the National Credit Regulator.
Top Questions About Personal Loans in South Africa
How much can I borrow with a personal loan in South Africa?
You can typically borrow between R1,000 and R350,000, depending on your income, credit profile, and existing debt. Lenders assess your affordability to determine the exact amount you qualify for.
How do I apply for a personal loan online?
You can apply for a personal loan online by completing a short application and getting matched with lenders. Once submitted, the lender reviews your documents and affordability before approving and paying out the funds. You can start your application here: apply online.
What is the best way to compare personal loan offers?
You should compare personal loans based on the monthly repayment, total cost of credit, repayment term, and any fees included. A lower monthly payment does not always mean a cheaper loan overall. Use our compare loans South Africa page to review options side by side.
How fast can I get a personal loan payout?
Some approved personal loans may be paid out on the same day, while others can take a few working days. Payout timing depends on the credit provider, how quickly your information and documents are verified, when you accept the loan agreement, banking cut-off times, and your bank. Same-day payout is not guaranteed.
Do personal loans require upfront fees in South Africa?
Be cautious if someone asks you to pay money upfront to “release”, “unlock”, or guarantee a personal loan. Legitimate credit agreements can include permitted costs such as an initiation fee and service fees, but these should be clearly disclosed as part of the credit agreement and cost of borrowing. If you're asked to send an unexpected upfront payment before receiving a loan, check our fraud alert page before proceeding.
How do I receive my loan funds?
If your loan is approved and you accept the credit agreement, the credit provider will usually pay the approved funds into your South African bank account. Payout times vary depending on the lender, verification requirements, banking cut-off times, and your bank.
Do I need collateral to get a personal loan?
No, most personal loans in South Africa are unsecured and do not require collateral. Credit providers may consider factors such as your income, expenses, existing debt, credit profile, repayment history, and overall affordability when assessing an application.
Can I get a personal loan with bad credit?
Some credit providers may consider personal loan applications from people with bad credit, but approval is not guaranteed and depends on factors such as your income, existing debt, credit profile, and affordability. A weaker credit profile may also affect the loan amount, interest rate, or repayment terms offered. Explore options on our bad credit loans page.
What rights do I have as a borrower in South Africa?
You have the right to receive a clear loan quote, understand all fees, and be assessed for affordability before approval. You can also request reasons if your application is declined and access your credit profile anytime with a free credit report.
What can I use a personal loan for?
You can use a personal loan for expenses like debt consolidation, medical bills, home repairs, or education. Most lenders do not restrict how the funds are used unless stated in the agreement. For debt-related needs, consider consolidation loans.
How can I avoid loan scams in South Africa?
You can avoid loan scams by using verified lenders, refusing upfront payment requests, and reviewing all loan terms carefully. Always confirm the lender is registered and visit our fraud alert page or learn how to verify NCR registration.
Can I Repay a Personal Loan Early?
Yes. Under the National Credit Act, consumers are entitled to settle a credit agreement at any time. Ask the credit provider for a settlement quotation showing the amount required to settle the loan. The settlement amount is calculated according to the type and terms of the credit agreement and applicable NCA requirements.
What Should I Do if My Personal Loan Application Is Declined?
Being declined by one credit provider does not necessarily mean every lender will make the same decision, as lending criteria can differ. However, repeatedly submitting new applications immediately after a decline may not be the best approach.
Consider:
- Asking the credit provider why the application was declined
- Checking your credit report for incorrect or outdated information
- Reviewing your existing debt commitments
- Considering whether the amount requested was affordable
- Reducing existing debt where possible
- Waiting until your financial position improves before applying again
South African consumers can request reasons when a credit application is declined. You can also start by checking your free credit report.
How Do I Know if a Personal Loan Repayment Is Affordable?
There is no single percentage that tells every borrower whether a personal loan is affordable. Start with your take-home income and subtract essential living expenses, existing debt repayments, and other regular financial commitments. Then consider whether the proposed loan instalment still leaves enough room for normal expenses and unexpected costs.
Credit providers perform their own affordability assessment before granting credit, but you should also make your own decision about whether the repayment is comfortable for your household budget.
If the repayment would leave you relying on further credit for normal monthly expenses, consider borrowing less or exploring another option.
Why FatCat Loans Stands Out
We’re not just another loan site. Our South African-focused platform helps connect applicants with participating NCR-registered credit providers offering personal loan options across different loan amounts, rates, and repayment terms. Whether you’re in Pretoria or Port Elizabeth, you can complete one online application and we’ll use your information to look for potential matches within our lender network. For more tips and advice, visit our blog or FAQ. Always review our Terms and Conditions and Privacy Policy before applying.
Ready to compare personal loan options?
Complete one secure application and we’ll match your profile with available NCR-registered credit providers. Approval is not guaranteed, and payout times depend on the lender, your documents, and your bank. Apply for a Personal Loan.
FatCat Loans is an online loan comparison tool and not a credit provider. We only work with NCR-registered credit providers in South Africa. Our comparison service to consumers is free of charge. Interest rates, fees, loan amounts and repayment terms vary between credit providers and applicants. Maximum permitted interest rates and fees are regulated under the National Credit Act. Always review the credit provider's pre-agreement statement and quotation for the actual repayment amount and total cost of credit.
How We Help You Make a Safer Borrowing Decision
FatCat Loans is a loan comparison service, not a credit provider. Our goal is to help South Africans compare suitable options, understand the borrowing process, and avoid common mistakes before submitting an application. We encourage readers to compare affordability, check lender legitimacy, and read the full loan terms before accepting any offer.
If you want to learn more before applying, you can also visit our about us page, read our personal loan explained guide, or explore whether personal loans affect your credit score.
Sources and Review Information
We review our loan information against South African consumer-credit rules and guidance to help keep the information on this page accurate and useful.
Primary sources used for this page include:
- National Credit Act 34 of 2005 – South African Government
- National Credit Regulator (NCR) – consumer credit information and guidance
- National Credit Regulator guidance on affordability assessments
- National Credit Regulator – Consumer Rights under the National Credit Act
Loan products, lending criteria, and individual offers can change. Always rely on the credit provider's current quotation and credit agreement for the actual interest rate, fees, repayment schedule, and total cost applicable to your loan.
Last reviewed: September 2026
Reviewed by: FatCat Loans Editorial Team
FatCatLoans.co.za is a South African loan-matching service, not a lender, credit provider, or financial advisor. We connect applicants with registered credit providers in our network and may receive a commission from lenders when a loan is funded. There is no cost to use our service.
The information on this website is provided to help South Africans understand personal loan options and does not constitute financial advice. Always review the credit provider’s interest rate, fees, repayment term, monthly instalment, and total cost of credit before accepting any offer.
Credit providers in South Africa must comply with the National Credit Act, including affordability assessments and clear cost disclosure before you enter into a credit agreement. Loan approval is not guaranteed.
Your personal information is processed in line with POPIA and shared only for the purpose of matching your application with relevant credit providers, subject to your consent and our Privacy Policy.