Loans for Blacklisted Consumers in South Africa
May 19, 2024
What “Blacklisted” Actually Means in South Africa
Last Updated: September 2026
In South Africa, being “blacklisted” does not mean you are on an official blacklist or permanently banned from borrowing. The term is commonly used when a credit report contains negative information such as missed payments, defaults or judgments.
Having negative credit information can make borrowing more difficult, but lenders consider more than your credit score alone. Registered credit providers must assess whether new credit is affordable and may also consider your income, existing financial obligations and credit history before making a decision.
If you are looking for loan options with a poor credit history, FatCat Loans can help you compare options from our lender network. FatCat Loans is a comparison service, not a lender, and approval is never guaranteed.
Quick answer: You may still be considered for credit if you have negative information on your credit report, but this depends on the lender’s criteria, your current financial position and an affordability assessment. Be cautious of anyone promising “guaranteed approval” or credit without the required checks.
What Does “Blacklisted” Mean in South Africa?
The term “blacklisted” is widely used in South Africa, but it is not a formal loan category or permanent borrowing status. It generally refers to negative information recorded on your credit profile.
This may include:
- Missed or late payments
- Accounts in arrears or default
- Judgments
- Collection activity
- Debt review status
Credit bureaus collect information about how consumers manage credit. When you apply for a loan, a credit provider may use your credit report alongside other information to assess the risk of lending to you.
However, a negative credit record does not automatically mean that every future application will be declined. Credit providers must also carry out an affordability assessment before granting credit.
How Can Negative Credit Information Affect a Loan Application?
Negative information on your credit report can affect whether a lender is willing to offer you credit, how much you may qualify for and the terms you are offered.
A recent default or missed payment may be viewed differently from an older issue that has since been resolved. Each lender has its own credit criteria, so having a poor credit history does not guarantee either approval or rejection.
How to Check Your Credit Record
If you are unsure what appears on your credit profile, check your credit report before applying for new credit. Your report can show payment history, defaults, judgments and other information that lenders may consider.
You can learn more about how to check your credit report in South Africa.
If information on your report is incorrect, you have the right to dispute it with the relevant credit bureau.
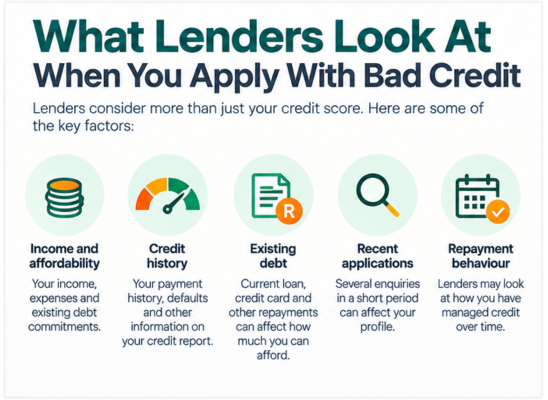
What Lenders Look At When You Apply for a Loan With Bad Credit
Having negative information on your credit report does not mean a lender will ignore your current financial situation. Credit providers consider several factors when assessing an application, including your credit history and whether you can afford the repayments.
Common factors include:
Your Income and Affordability
A lender will assess your income, regular expenses and existing debt commitments to determine whether you can reasonably afford another repayment.
A steady income may help demonstrate your ability to repay, but it does not guarantee approval.
Your Credit History
Lenders may review your payment history, outstanding debts, defaults and other information recorded on your credit report.
The type, severity and age of negative information can all form part of a lender’s assessment.
Your Existing Debt
Existing loan, credit card and other credit repayments can affect how much additional credit you can afford. Applying for more than your budget can support may reduce your chances of being approved.
Recent Credit Applications
Lenders may also consider recent credit enquiries or applications. Making several applications within a short period can result in multiple enquiries appearing on your credit profile, so it is generally better to compare suitable options before applying.
Can You Qualify for a Loan if You Are Blacklisted?
You may still be considered for credit if you have negative information on your credit report, but there is no single set of eligibility requirements for a “blacklisted loan”.
Each lender sets its own lending criteria and will assess your application before deciding whether to offer credit.
Depending on the lender and loan product, you may need to:
- Be at least 18 years old.
- Have a valid South African ID.
- Have a regular, verifiable source of income.
- Have an active South African bank account.
- Provide the documents required to verify your income and financial position.
- Pass the lender’s credit and affordability assessment.
Having a regular income does not automatically mean you will qualify. The lender must consider whether the proposed repayments are affordable alongside your existing financial obligations.
Important: If you are currently under debt review, taking on additional credit is generally restricted under the National Credit Act. Speak to your debt counsellor if you are unsure what applies to your situation.
Documents You May Need When Applying
The documents required vary by lender, but you may be asked to provide some or all of the following:
Requirements and Why They Matter
| Document | Why It May Be Requested |
|---|---|
| South African ID | To verify your identity and age |
| Recent bank statements | To help verify income, expenses and affordability |
| Proof of income | This may include payslips or other evidence of regular income |
| Proof of address | Some lenders may request this for verification purposes |
| Bank account details | Required where approved funds are paid into your bank account |
If your credit history is making it harder to find suitable borrowing options, you can also read our guide to bad credit loan options in South Africa.
How to Compare Loan Options With a Poor Credit History
If you have negative information on your credit report, comparing loan options before applying can help you avoid unnecessary applications and understand the costs involved.
When comparing loans, look at:
- Total cost of credit: Consider the full amount you will repay, not only the monthly instalment.
- Interest and fees: Check the interest rate and any initiation, service or other permitted charges.
- Repayment term: A longer term may reduce the monthly repayment but can increase the total amount repaid.
- Monthly repayment: Make sure the instalment is realistic alongside your existing expenses and debts.
- Lender registration: Check that the credit provider is registered with the National Credit Regulator (NCR).
- Loan conditions: Read the pre-agreement statement and quotation carefully before accepting an offer.
FatCat Loans allows you to compare loan options from our lender network. FatCat Loans is not a lender, and submitting an enquiry does not guarantee that you will receive a loan offer.
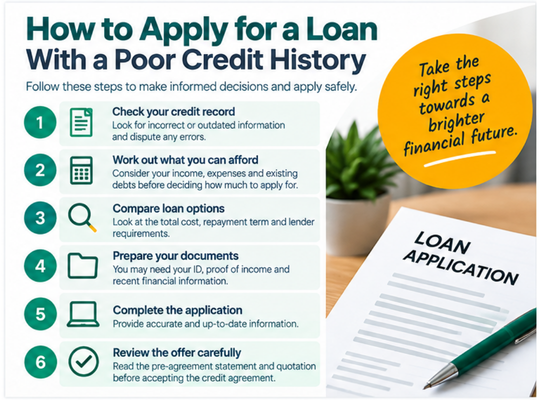
How to Apply for a Loan With a Poor Credit History
The application process varies between lenders, but it will generally involve the following steps:
- Check your credit record. Review your credit report and dispute any information you believe is incorrect.
- Work out what you can afford. Consider your income, essential expenses and existing debt repayments before deciding how much to apply for.
- Compare suitable loan options. Look at the total cost, repayment term, monthly instalment and lender requirements rather than applying to multiple lenders at once.
- Prepare your documents. You may need identification, proof of income and recent financial information so the lender can assess your application.
- Complete the application. Provide accurate information about your income, expenses and existing financial obligations.
- Review the offer carefully. If approved, read the pre-agreement statement and quotation before accepting the credit agreement.
Remember: An application is not the same as approval. The credit provider must assess your application and affordability before deciding whether to offer credit.
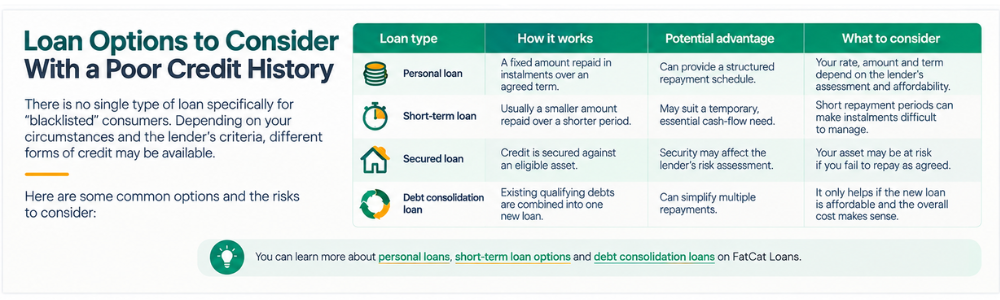
Loan Options to Consider With a Poor Credit History
There is no single type of loan specifically for “blacklisted” consumers. Depending on your circumstances and the lender’s criteria, different forms of credit may be available.
Here are some common options and the risks to consider:
| Loan Type | How It Works | Potential Advantage | What to Consider |
|---|---|---|---|
| Personal loan | A fixed amount repaid in instalments over an agreed term | Can provide a structured repayment schedule | Your rate, amount and term depend on the lender’s assessment and affordability |
| Short-term loan | Usually a smaller amount repaid over a shorter period | May suit a temporary, essential cash-flow need | Short repayment periods can make instalments difficult to manage |
| Secured loan | Credit is secured against an eligible asset | Security may affect the lender’s risk assessment | Your asset may be at risk if you fail to repay as agreed |
| Debt consolidation loan | Existing qualifying debts are combined into one new loan | Can simplify multiple repayments | It only helps if the new loan is affordable and the overall cost makes sense |
You can learn more about personal loans in South Africa, short-term loan options and debt consolidation loans before deciding which type of borrowing may suit your circumstances.
How to Improve Your Chances Before Applying
No strategy can guarantee that a loan application will be approved. However, there are practical steps you can take before applying:
- Check your credit report: Look for incorrect or outdated information and dispute errors with the relevant credit bureau.
- Apply for a realistic amount: Consider what you can comfortably repay after your normal living expenses and existing debt commitments.
- Reduce existing debt where possible: Lower financial commitments may improve your overall affordability.
- Keep repayments up to date: Paying existing accounts as agreed can help prevent further negative information being added to your credit record.
- Avoid multiple applications: Compare suitable options first rather than submitting applications to several lenders within a short period.
- Provide accurate information: Make sure the income, expenses and debt information in your application is complete and correct.
Improving your credit profile takes time. Be wary of businesses or lenders that promise to remove legitimate negative information instantly or guarantee that you will qualify for credit.
How Much Can a Loan Cost if You Have Bad Credit?
Having a poor credit history does not create a separate set of loan charges. The cost of borrowing depends on the type of credit, the amount borrowed, the repayment term, the lender’s assessment and the fees permitted under the credit agreement.
Depending on the loan, your total cost may include:
- Interest: The rate charged on the amount you borrow.
- Initiation fee: A once-off fee that may apply when the credit agreement is entered into.
- Service fee: An ongoing fee that may apply for administering the credit agreement.
- Credit life insurance: This may apply to certain credit agreements and can add to the overall cost.
Do not compare loans using the monthly repayment alone. A lower monthly instalment over a longer repayment period can still result in a higher total amount repaid.
Before accepting a loan, review the pre-agreement statement and quotation so you understand the interest, fees, repayment amount, repayment term and total cost of credit.
Affordability matters: If a new repayment would leave you struggling to cover essential living costs or existing debt, taking another loan may make your financial position worse. Consider the full repayment obligation before accepting new credit.
How to Avoid Blacklisted Loan Scams
People searching for loans with a poor credit history can be particularly vulnerable to lenders or scammers promising easy approval. Be cautious of any loan offer that sounds too good to be true.
Warning signs can include:
- Guaranteed approval: Legitimate credit providers must assess an application before granting credit.
- “No checks” claims: Be wary of anyone promising credit without assessing your financial circumstances.
- Upfront payments to release a loan: Do not pay money simply because someone claims it is required before approved funds can be released.
- Pressure to act immediately: You should have an opportunity to understand the agreement and costs before accepting credit.
- Unverifiable lender details: Check the credit provider’s details and NCR registration rather than relying only on a website, social media profile or WhatsApp message.
- Requests for sensitive banking information: Never share your PIN, password or one-time PIN (OTP) with someone offering you a loan.
You can check whether a credit provider is registered using the National Credit Regulator’s register of credit providers.
FatCat Loans will never ask you to pay an upfront fee to access a loan. Read our fraud alert if you receive a suspicious message claiming to be from FatCat Loans.
What If Another Loan Is Not the Right Option?
A new loan is not always the best solution, particularly if you are already struggling with existing repayments.
Depending on your situation, alternatives may include:
- Speaking to your existing creditors about repayment arrangements.
- Reviewing your budget and prioritising essential expenses before taking on additional debt.
- Considering debt consolidation only where the new arrangement is affordable and makes financial sense.
- Seeking help from an NCR-registered debt counsellor if you are unable to keep up with your existing credit commitments.
If you are already under debt review, speak to your debt counsellor before considering any further credit.
How Long Does “Blacklisting” Last in South Africa?
There is no single period for being “blacklisted” because there is no official blacklist. Different types of information can remain on your credit report for different periods.
The retention period depends on the type of information recorded, such as payment history, adverse information, defaults or judgments. Some information may also need to be updated or removed when the underlying debt is paid or the legal requirements for removal are met.
This is why it is better to check your actual credit report rather than assume you will be unable to borrow for a fixed number of years.
If you have settled an account but your credit report has not been updated correctly, contact the credit provider or credit bureau and ask for the information to be investigated.
For current rules on credit information and consumer rights, refer to the National Credit Regulator or the relevant credit bureau.
Your Rights When Applying for Credit
Consumers in South Africa have protections under the National Credit Act. Having a poor credit history does not remove those rights.
When considering a loan:
- Use a registered credit provider: Verify the provider’s NCR registration before borrowing.
- Expect an affordability assessment: A lender should assess whether you can afford the proposed credit rather than simply promising approval.
- Understand the cost: Review the interest, fees, repayment term and total repayment obligation before accepting an agreement.
- Check your credit information: You have the right to access your credit report and dispute information you believe is incorrect.
- Keep copies of your agreement: Save your quotation, credit agreement and relevant correspondence in case you need to refer to them later.
If you believe a credit provider has acted unlawfully or your rights have been breached, you can contact the National Credit Regulator for information about the appropriate complaints process.
Common Mistakes to Avoid When Applying With Bad Credit
When you need money urgently, it can be tempting to accept the first loan offer you receive. Before applying or accepting credit, avoid these common mistakes:
- Applying to several lenders at once: Compare suitable options first rather than submitting multiple applications in a short period.
- Focusing only on the monthly repayment: Check the interest, fees, repayment term and total amount you will repay.
- Borrowing more than you need: A larger loan means a larger repayment obligation and potentially a higher overall cost.
- Assuming approval is guaranteed: A poor credit history does not automatically prevent you from applying, but every application remains subject to the lender’s criteria and affordability assessment.
- Ignoring warning signs: Verify the lender and never pay an upfront fee simply to have loan funds released.
Final Thoughts on Loans for Blacklisted Consumers
Having negative information on your credit report does not mean you are permanently banned from applying for credit in South Africa. However, it can affect the options available to you, and approval will depend on the lender’s criteria, your credit profile and whether the repayments are affordable.
Before borrowing, check your credit report, compare the total cost of suitable options and verify that the credit provider is registered with the NCR. Never rely on promises of guaranteed approval or offers that claim the required affordability checks can be avoided.
If another loan would make your existing financial commitments harder to manage, consider speaking to your creditors or an NCR-registered debt counsellor before taking on additional debt.
Editorial disclosure: This article is for general information only and does not constitute financial advice. FatCat Loans is a loan comparison service, not a lender. Loan availability, rates, fees, terms and eligibility depend on the individual credit provider and your circumstances. Always review the lender’s pre-agreement statement and quotation before accepting credit.
Frequently Asked Questions
Can I get a loan if I am blacklisted in South Africa?
You may still be considered for credit if you have negative information on your credit report. Approval is not guaranteed and depends on the lender’s criteria, your credit history, income, existing financial obligations and affordability assessment.
What do lenders check if I have bad credit?
Lenders may consider your credit history, income, regular expenses, existing debt commitments and recent repayment behaviour. They must also assess whether you can afford the proposed repayments before granting credit.
Can I get a blacklisted loan without a credit check?
Be cautious of anyone advertising guaranteed loans with no checks. Registered credit providers are required to assess applications and affordability before granting credit. Having bad credit does not mean these checks can simply be skipped.
Can I get a loan while under debt review?
Access to further credit is generally restricted while you are under debt review. If you are currently under debt review and are unsure about your position, speak to your debt counsellor before applying for additional credit.
How long does blacklisting last in South Africa?
There is no single “blacklisting” period because South Africa does not have an official blacklist. Different types of information can remain on a credit report for different periods, so check your current credit report to see what information is recorded.
What documents might I need when applying?
Requirements vary by lender, but you may be asked for a valid South African ID, proof of income, recent bank statements or other financial information, proof of address and bank account details.
How do I check whether a lender is registered with the NCR?
You can search the National Credit Regulator’s register of credit providers using the lender’s name or NCR registration details. If you cannot verify a lender, investigate further before providing personal information or paying any money.
What should I do if information on my credit report is wrong?
Contact the credit bureau that supplied the report and dispute the information you believe is incorrect. Provide supporting documents where available and keep records of your correspondence while the dispute is investigated.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.