MoneyShop Loans Review South Africa (2026)
September 22, 2026
MoneyShop Personal Loans: What You Need to Know
Last Updated: September 2026
Reviewed by: FatCat Loans South Africa Editorial Team
This review is for informational purposes only and does not constitute financial advice. MoneyShop is a loan-finding service rather than a credit provider. Any loan ultimately offered to you will be provided by a third-party lender and subject to that lender’s affordability assessment, interest rates, fees and terms.
MoneyShop Loans at a Glance
| Feature | Details |
|---|---|
| Service | Online loan and credit matching service |
| Is MoneyShop a lender? | No |
| Personal loan amounts | Typically R10,000–R350,000 |
| Personal loan terms | Typically 12–84 months |
| Personal loan APR | Typically between prime and 29.5% p.a. |
| Short-term loan amounts | Typically R1,000–R8,000 |
| Short-term loan terms | Typically 2–6 months |
| Application | Online |
| Minimum income | R4,000 per month |
| Credit check | Yes |
| Debt review | Applicants under debt counselling do not qualify |
| Cost to use MoneyShop | MoneyShop states its service is free |
Important: These are ranges MoneyShop publishes for the loans available through its service. They are not a loan offer from MoneyShop itself. The amount, interest rate, fees and repayment period available to you will depend on the lender you’re matched with and your individual application.
What Is MoneyShop?
MoneyShop.co.za is an online South African financial-services comparison and matching platform. It offers access to personal loans, short-term loans, credit cards, debt-related services, insurance and other financial products.
The key distinction for borrowers is that MoneyShop does not lend you the money itself.
MoneyShop describes its role as helping consumers find loan products from its partner providers. Its terms state that the website is owned and operated by Online Lending Innovations Company (Pty) Ltd and that information submitted through the website may be shared with financial-service companies or brokers.
This means there are potentially two separate stages:
- You submit your information to MoneyShop.
- A partner lender ultimately decides whether to offer you credit and on what terms.
That distinction matters when comparing MoneyShop with a direct lender such as Capfin, African Bank or Wonga.
If you’d rather compare several loan options through another matching service, you can also review the providers available through the FatCat Loans lender network.
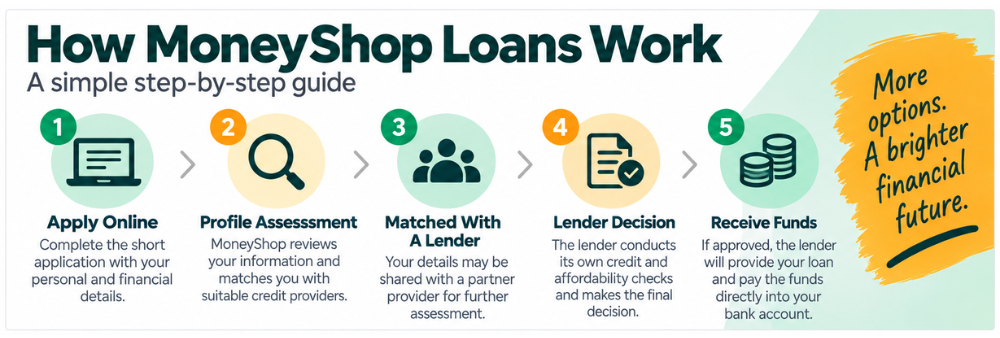
How MoneyShop Loans Work
MoneyShop uses information provided during the application process to try to match applicants with suitable credit providers.
Step 1: Complete the Online Application
You start by entering personal and financial information through MoneyShop’s online application.
MoneyShop’s published eligibility requirements for personal loans currently include:
- A valid South African ID
- Minimum income of R4,000 per month
- Passing a credit check
- Not being under debt counselling
Step 2: MoneyShop Assesses Your Profile
MoneyShop says it uses technology to match loan and credit products with consumers based on their profiles.
This does not mean MoneyShop has approved your loan.
A match or pre-approval through a comparison service should not be confused with final approval from the credit provider.
Step 3: You May Be Matched With a Partner
If MoneyShop identifies a potential provider, your application can move to that partner for further assessment.
MoneyShop’s terms explain that it has relationships with various banks, lenders and insurers and may submit consumer details to financial-service companies or brokers.
Step 4: The Lender Makes the Credit Decision
The lender may then conduct its own affordability and credit assessment and request supporting documentation.
If approved, the actual lender — not MoneyShop — provides the loan agreement.
Before accepting, check:
- Who the credit provider is
- NCR registration
- Loan amount
- Interest rate
- Initiation fee
- Monthly service fee
- Credit insurance, if applicable
- Monthly instalment
- Repayment term
- Total amount repayable
Do not accept an offer simply because the monthly repayment appears affordable.
How Much Can You Borrow Through MoneyShop?
Although MoneyShop lists personal loan options of up to R350,000, MoneyShop does not provide the loan itself. The amount available depends on the partner lender and your individual application.
Technically, it doesn’t.
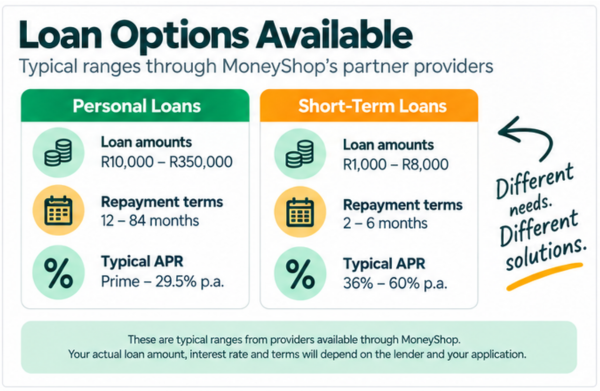
MoneyShop currently categorises the products available through its service as follows:
Personal Loans
MoneyShop publishes typical:
- Loan amounts: R10,000–R350,000
- Terms: 12–84 months
- APR: between prime and 29.5% per year
Short-Term Loans
MoneyShop publishes typical:
- Loan amounts: R1,000–R8,000
- Terms: 2–6 months
- APR: approximately 36%–60%
These figures describe products available from providers in MoneyShop’s marketplace. Individual lenders may have different limits and eligibility requirements.
If you’re looking specifically for a longer-term loan, our guide to personal loans in South Africa explains how amounts, terms and affordability assessments work.
MoneyShop Interest Rates and Fees
There isn’t one single MoneyShop interest rate.
That’s because MoneyShop isn’t the credit provider.
The rate you’re offered will depend on factors including:
- The lender you’re matched with
- Your credit profile
- Income
- Existing financial commitments
- Loan amount
- Repayment term
- Affordability assessment
MoneyShop currently says personal-loan APRs available through its service are typically between prime and 29.5% per year, while its short-term loan category carries substantially higher annualised rates.
What About Initiation and Service Fees?
These will also depend on the actual credit provider.
South African lenders may charge permitted interest and fees within the limits established by the National Credit Act and applicable regulations.
Your pre-agreement statement should therefore be the source you use when assessing the actual cost.
Don’t compare loan offers using the interest rate alone. Compare the total amount repayable.
Is MoneyShop Legit?
MoneyShop is a South African financial-services matching website rather than a lender.
Its website identifies the operator as Online Lending Innovations Company (Pty) Ltd, and MoneyShop states that it works with banks, lenders, insurers and other financial-service providers.
This distinction is important when checking regulatory information.
A direct lender extending credit must meet the applicable requirements for credit providers. With a matching service such as MoneyShop, you should also verify the actual lender named in any loan offer before entering into a credit agreement.
Before accepting a loan, check that the credit provider:
- Clearly identifies itself
- Provides its NCR registration details
- Gives you a pre-agreement statement and quotation
- Discloses interest and applicable fees
- Explains the repayment schedule
- Does not demand suspicious upfront payments to “release” your loan
You can learn more about the lenders available through FatCat Loans in our lender network.
Does MoneyShop Guarantee Loan Approval?
No.
Completing a MoneyShop application does not mean you will receive a loan.
MoneyShop’s own requirements include a credit check, minimum monthly income and restrictions for consumers undergoing debt counselling.
The lender considering your application ultimately determines whether you qualify.
Be cautious of websites or messages claiming to offer “guaranteed MoneyShop loans”, particularly where you’re asked to pay money before receiving the loan.
Can You Apply With Bad Credit?
Potentially, but poor credit can reduce the number of products available to you.
MoneyShop explains that what consumers often call being “blacklisted” can cover several different credit problems, including missed payments, arrears and judgments. It says eligibility depends on the nature and severity of the information on your credit profile.
Having poor credit therefore doesn’t necessarily mean every application will be rejected, but neither MoneyShop nor a lender can guarantee approval.
If your credit history is causing difficulty, read our guide to bad credit loans in South Africa before making multiple applications.
Can You Apply While Under Debt Review?
No.
MoneyShop specifically lists being under debt counselling as a reason you won’t qualify for a personal loan through its service.
This is consistent with South Africa’s credit framework, where consumers under debt review generally cannot take on additional credit until the relevant debt-review process has been completed and the required clearance has occurred.
Be particularly wary of advertising claiming to provide ordinary new loans to consumers actively under debt review.
What Documents Might You Need?
MoneyShop’s application process begins online, but the lender you’re matched with may require documents before final approval.
Depending on the lender and your circumstances, these can include:
- South African ID
- Recent payslips or other proof of income
- Recent bank statements
- Bank account details
- Additional verification documents
An older MoneyShop guide to its application process says partner lenders may request an ID, three months’ bank statements and payslips. Because document requirements can change and differ between lenders, check the requirements supplied with your current application.
MoneyShop Pre-Approval: What Does It Mean?
This is worth explaining because pre-approved and approved are not the same thing.
MoneyShop’s own application guidance refers to applicants potentially being informed that they are pre-approved with a partner before continuing the application with that provider.
A pre-approval generally means your initial information indicates that you could meet certain criteria.
It does not guarantee:
- Final loan approval
- A particular loan amount
- A particular interest rate
- Immediate payment
The lender may still verify your information and perform its required affordability and credit assessments before making a final decision.
How Long Does MoneyShop Take to Pay Out?
There isn’t a universal MoneyShop payout time because MoneyShop doesn’t disburse the loan.
Once you’re matched with a provider, processing and payout depend on that lender.
The time taken can be affected by:
- Document verification
- Affordability checks
- Credit assessment
- When you complete the application
- Your bank
- The particular lender’s processes
If fast access to funds matters, compare this with our guide to instant loans in South Africa, while remembering that “instant” generally refers to the application or decision process rather than guaranteed immediate payment.
MoneyShop vs Applying Directly to a Lender
| MoneyShop | Direct Lender |
|---|---|
| Loan-matching service | Provides the credit |
| May connect you with a partner | You choose the lender directly |
| One initial online process | Separate application for each lender |
| Loan terms depend on matched provider | Lender publishes its own product terms |
| MoneyShop does not set your final rate | Lender determines your rate |
| MoneyShop does not pay out the loan | Lender disburses approved funds |
Neither route automatically produces a better offer.
The important comparison is the actual credit agreement you’re offered, not simply where the application started.
Want to see what loan options may be available to you? FatCat Loans can help you compare participating lenders with one online application.
MoneyShop vs FatCat Loans
MoneyShop and FatCat Loans have an important similarity: neither is the lender providing the credit.
Both services are designed to help consumers connect with potential loan providers rather than lending money themselves.
The lender ultimately determines whether you’re approved and the amount, interest rate, fees and repayment terms you’re offered.
You can learn more about how to compare loan options before applying.
MoneyShop Free Credit Report
MoneyShop also promotes access to a free credit report as part of its credit-related services.
Checking your credit information before applying can be useful because it can help you understand what lenders may see when assessing your application.
It may also help you identify incorrect information that should be disputed before you submit further credit applications.
FatCat Loans also has a guide to getting a free credit report.
What to Check Before Accepting a Loan Found Through MoneyShop
Finding a potential lender is only the beginning of the decision.
Before signing, check the actual offer for:
- Credit provider: Who is actually lending you the money?
- NCR details: Is that provider properly registered?
- Loan amount: Are you borrowing only what you need?
- Interest: What rate have you personally been offered?
- Fees: What initiation, service and other permitted charges apply?
- Repayment term: How long will you be paying?
- Monthly instalment: Does it comfortably fit your budget?
- Total repayment: How much will you repay in rand from start to finish?
That final figure is particularly important. A lower monthly instalment achieved through a longer term can still result in a higher overall borrowing cost.

Frequently Asked Questions
Is MoneyShop a lender?
No. MoneyShop says it is not a loan provider. It operates as a financial-services matching platform that can connect applicants with partner loan providers. The lender you’re matched with is responsible for assessing the application and, if approved, providing the credit.
How much can I borrow through MoneyShop?
MoneyShop currently lists typical personal loans of R10,000 to R350,000 and short-term loans of R1,000 to R8,000. These are ranges across products available through its service rather than a loan amount guaranteed by MoneyShop.
What is the MoneyShop interest rate?
There is no single MoneyShop loan interest rate because MoneyShop isn’t the lender. MoneyShop currently says personal loans available through its service typically have APRs between prime and 29.5% per year. Your actual rate depends on the lender and your application.
What do I need to qualify for a MoneyShop loan?
MoneyShop currently lists a South African ID, minimum income of R4,000 per month, passing a credit check and not being under debt counselling among its personal-loan requirements. The lender you’re matched with may have additional requirements.
Does MoneyShop do a credit check?
MoneyShop states that applicants need to pass a credit check to qualify for personal-loan options through its service. The eventual lender may also carry out the checks and affordability assessment required before granting credit.
Can I use MoneyShop if I have bad credit?
Potentially. MoneyShop explains that eligibility depends on the information contained in your credit profile and the severity of any adverse information. Poor credit can reduce your available options, and approval is never guaranteed.
Can I apply through MoneyShop while under debt review?
MoneyShop says applicants undergoing debt counselling do not qualify for a personal loan through its service.
Is MoneyShop free to use?
MoneyShop states that its loan-finding service is free to consumers. The loan itself is not free: if you’re approved by a partner lender, interest and applicable fees will form part of that lender’s credit agreement.
Does MoneyShop guarantee approval?
No. MoneyShop can help match an applicant with a potential provider, but final approval depends on the lender’s credit and affordability assessment.
Is MoneyShop pre-approval the same as final approval?
No. MoneyShop’s application guidance describes applicants potentially being pre-approved with a partner before completing the rest of that provider’s application. The lender may still need to verify documents, affordability and other information before granting the loan.
How long does a MoneyShop loan take to pay out?
MoneyShop doesn’t pay out loans itself. If your application is approved, the payout time depends on the lender you’re matched with, its verification process and banking times.
What documents do I need for MoneyShop?
The initial MoneyShop process is online. The eventual lender may request supporting documents such as your South African ID, payslips or other proof of income and recent bank statements. Requirements differ between providers.
How do I check my MoneyShop loan application status?
MoneyShop provides an online option to check the status of a personal-loan application through its website.
Who actually provides a MoneyShop loan?
MoneyShop works with third-party financial-service providers. The specific provider you’re matched with should be identified during the application process. Always check the lender’s identity, NCR registration and full loan quotation before accepting credit.
Can I apply directly with FatCat Loans instead?
FatCat Loans is also a comparison and matching service rather than a lender. You can submit an application to compare available loan options from participating providers.
Final Takeaway
The most important thing to understand about MoneyShop is that MoneyShop is not the lender.
It provides an online service that can match consumers with third-party loan providers. That can make it convenient to explore potential options without starting separately with individual lenders, but the actual loan terms depend entirely on the provider considering your application.
Before accepting an offer, identify the actual lender and compare the interest rate, fees, monthly instalment, repayment period and total amount repayable.
If you’re ready to explore alternatives, you can compare loan options from participating lenders through FatCat Loans.
Sources & References
We reviewed publicly available information from MoneyShop and official South African consumer-credit sources. Product details can change, so always check the latest information and the terms of any loan offer before applying.
- MoneyShop South Africa – current loan ranges, typical rates and terms, eligibility requirements and service information.
- MoneyShop Terms & Conditions – information about MoneyShop’s operator, partner relationships and how applicant information may be shared with financial-service providers.
- National Credit Regulator (NCR) – information about consumer credit, credit providers and consumer protections in South Africa.
- National Credit Act 34 of 2005 – South Africa’s legislative framework governing consumer credit.
Sources checked: September 2026.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.