Sunshine Loans South Africa Review: Fees, Legal Costs & Risks
February 24, 2026
Sunshine Loans South Africa Review
Published February 2026 | Last reviewed September 2026
Reviewed by: FatCat Loans South Africa Editorial Team
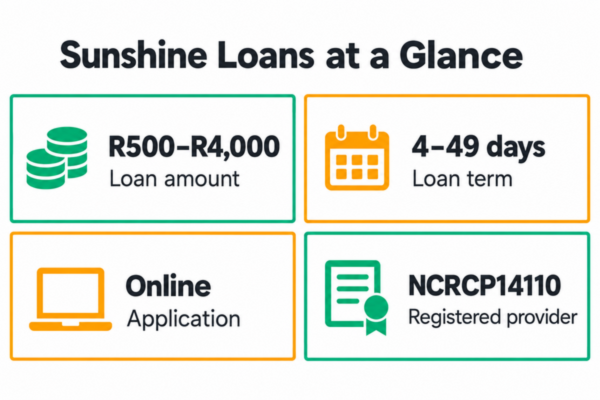
Regulatory Status: Sunshine Loans is registered with the National Credit Regulator (NCRCP14110).
Company: MoneySpot Finance SA (Pty) Ltd, trading as Sunshine Loans.
This guide is informational only and not financial advice. Always review your loan agreement carefully before accepting credit.
Executive Summary
Sunshine Loans is a South African short-term credit provider offering loans from R500 to R4,000, repayable over 4 to 49 days.
It is:
- Fully online
- NCR registered
- Designed for short-term emergency borrowing
However, the short repayment period can place considerably more pressure on your budget than a longer-term instalment loan. Check your quotation carefully to confirm whether your approved loan will be collected in one payment or more than one instalment.
If you need more than R4,000, longer than 49 days to repay, or lower monthly repayment pressure, structured options like instalment loans may be worth comparing first.

Who Is Sunshine Loans?
Sunshine Loans operates as a short-term credit provider under South Africa’s National Credit Act (NCA). Their product is designed for small, urgent cash needs such as:
- Emergency car repairs
- Medical co-payments
- School fees
- Utility shortfalls
- Temporary cash gaps before payday
They are not a long-term financing solution.
Loan Details at a Glance
| Feature | Details |
|---|---|
| Loan Amount | R500 – R4,000 |
| Repayment Term | 4 – 49 days |
| Application | Online |
| Credit Check | Yes (affordability required) |
| Funding Speed | Sunshine says funding can take place within one business day, subject to approval and bank processing times |
| Regulation | National Credit Regulator |
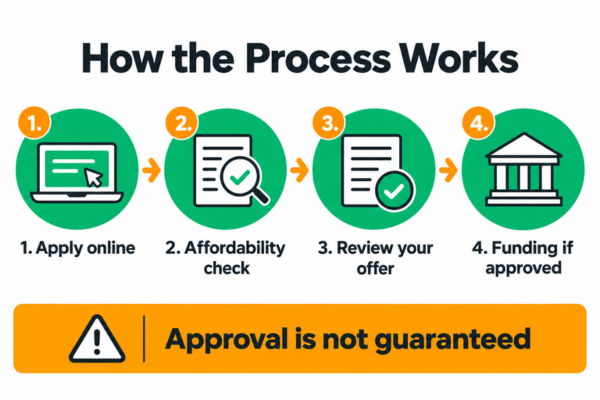
How Sunshine Loans Works
Step 1: Online Application
You complete a digital application including:
- South African ID
- Bank account details
- Income information
- Recent bank statements
Step 2: Affordability & Credit Check
Under the National Credit Act, lenders must perform affordability assessments. Sunshine Loans checks:
- Income stability
- Recent transaction behaviour
- Credit bureau data
- Existing obligations
Step 3: Approval Decision
If approved, you receive a pre-contract statement outlining:
- Loan amount
- Initiation fee
- Service fee
- Interest
- Total repayment
- Repayment date
Step 4: Payout
If an application is approved and the agreement is completed, Sunshine Loans says funding may take place by the end of the business day. The actual arrival time can depend on when the application is approved and the receiving bank’s processing times.
How Sunshine Loans Costs Are Regulated in South Africa (NCA + NCR)
Before looking at repayment examples, it’s important to understand how short-term loan pricing works in South Africa.
Sunshine Loans, like all registered credit providers, must comply with the National Credit Act (NCA) and is overseen by the National Credit Regulator (NCR).
This legislation regulates how lenders structure fees, interest, and total repayment amounts.
However, “regulated” does not mean “low cost.” It means the pricing components are legally defined and capped.
Understanding these components helps you:
- Identify what you’re being charged for
- Compare lenders accurately
- Avoid unexpected costs
- Evaluate whether the loan fits your budget
1️⃣ Initiation Fee (Once-Off Charge)
For short-term credit agreements, lenders are allowed to charge a once-off initiation fee when the loan is granted.
This fee:
- Is capped under the NCA
- Is charged once per agreement
- Is separate from interest
- May have VAT applied
Even on smaller loans (for example, R1,000), this fixed fee represents a meaningful percentage of the amount borrowed.
It is not refunded after the loan is disbursed.
2️⃣ Monthly Service Fee
Lenders may also charge a monthly service fee for administering the account.
This fee:
- Is capped under the NCA
- May apply even if the loan term is only 30 days
- Is separate from interest
- May have VAT applied
For short-term loans, this service fee can make up a noticeable portion of the total repayment.
3️⃣ Interest on Short-Term Loans
Short-term loans have regulated interest caps under South African law.
Interest:
- Is calculated on the principal amount
- Is applied according to the loan category
- Is disclosed before acceptance
Because these loans are short-term (often under 49 days), the cost may look high relative to the amount borrowed. This is due to the compressed repayment period.
The key number to focus on is not the percentage rate — it is the total repayment amount in rand.
4️⃣ VAT on Certain Fees
VAT (Value Added Tax) may be applied to:
- Initiation fees
- Service fees
It is generally not applied to the interest portion itself.
Many borrowers forget to factor VAT into the final total, which can make the repayment amount higher than expected.
5️⃣ Pre-Agreement Disclosure Requirements
Before you accept the loan, the lender must legally provide:
- A pre-agreement statement
- A quotation
- Full breakdown of fees
- Total repayment amount
- Repayment date
You should never accept a loan without reviewing this documentation carefully.
If anything is unclear, request clarification before signing.
6️⃣ Early Settlement Rights
Under the National Credit Act, borrowers have the right to settle their loan early.
If you repay early:
- Interest should be reduced proportionally
- The total cost of credit may decrease
This right exists whether or not it is heavily advertised.
7️⃣ What Regulation Does NOT Protect You From
While pricing is regulated, the law does not protect you from:
- Borrowing more than you can comfortably repay
- Cash flow pressure from a short repayment schedule
- Repeated short-term borrowing cycles
- Multiple simultaneous short-term loans
Affordability assessments reduce risk, but they do not eliminate it.
You remain responsible for evaluating whether the loan is sustainable within your monthly budget.
Understanding this regulatory structure makes the next section — where we break down real repayment examples — much easier to evaluate.
Now let’s look at what Sunshine Loans may actually cost in practice.
The Real Cost of Sunshine Loans (Detailed Breakdown)
Under the National Credit Act, short-term loans may include:
- Initiation fee (capped)
- Service fee
- Interest (monthly rate limit applies)
- VAT on applicable fees
Sunshine Loans Repayment Example
Sunshine Loans currently provides the following representative example on its official website:
- Amount borrowed: R2,800
- Repayment period: 27 days
- Interest and fees: R607.63
- Total repayment: R3,407.63
This example is provided for general guidance and may not represent the terms offered to you. Your actual cost will depend on the amount borrowed, repayment period, whether you have borrowed before and the terms contained in your quotation.
Before accepting a loan, check the pre-agreement statement for the exact interest, fees, repayment dates and total amount repayable.
Why Payday Loans Feel Affordable (But Aren’t)
Short-term loans feel manageable because:
- The amount is small
- The term is short
- Approval is quick
Because the repayment period is short, one or more repayments may fall within the next few pay cycles. Depending on the terms offered, this can create:
- Cash flow shock
- Next-month shortage
- Repeat borrowing cycle
For borrowers who need more breathing room, comparing flexible online loan options may provide better repayment structure.
Sunshine Loans vs Other South African Short-Term Lenders (Detailed Comparison)
Many short-term lenders in South Africa operate under the same National Credit Act caps. That means the legal maximum fees and interest structures are similar across providers.
However, the real differences typically appear in:
- Approval strictness
- Maximum loan limits
- Customer experience
- Repeat borrowing policies
- Transparency
- Flexibility during financial hardship
Below is a deeper breakdown comparing Sunshine Loans with common competitors such as Wonga, Boodle, and Lime Loans.
You can also review FatCat Loans’ lender network to compare Sunshine Loans with a wider range of regulated providers before applying.
1️⃣ Loan Amount Limits
| Lender | Maximum Loan |
|---|---|
| Sunshine Loans | R4,000 |
| Wonga SA | R3,000 |
| Boodle | Up to R5,000 for new customers and R8,000 for existing customers |
| Lime Loans | R4,500 |
What This Means
- If you need R3,000 or less, most lenders are viable.
- If you need above R4,000, Sunshine Loans may not meet your requirement.
- Boodle may suit borrowers needing slightly higher short-term limits.
However, remember:
Higher loan limits also mean higher total repayment pressure.
2️⃣ Repayment Term Comparison
Repayment terms differ between providers. Sunshine Loans offers terms of 4 to 49 days, while some competing lenders now provide longer repayment periods.
| Lender | Maximum Term |
|---|---|
| Sunshine Loans | 49 days |
| Wonga SA | 49 days |
| Boodle | 1–6 months |
| Lime Loans | 49 days |
When comparing repayment periods, the key question is:
Can you afford every scheduled repayment without falling short on essential expenses?
If not, a longer-term product may be safer than switching between short-term lenders.
3️⃣ Approval Criteria & Affordability Checks
All NCR-registered lenders must conduct affordability assessments.
However, approval models vary.
Sunshine Loans
- Reviews income stability
- Assesses recent bank transaction behaviour
- Evaluates existing obligations
Wonga SA
- Automated digital credit decisioning
- Strong reliance on internal risk scoring
Boodle
- May approve slightly higher limits for repeat borrowers
Lime Loans
- Focuses on short-term affordability windows
Important:
No reputable lender guarantees approval.
If any lender claims “100% guaranteed approval,” treat that as a red flag.
4️⃣ Repeat Borrowing Policies
Short-term lenders often allow repeat borrowing after successful repayment.
However:
- Some gradually increase limits
- Others maintain strict caps
- Some may reduce approval if repayment patterns appear strained
Repeat borrowing is one of the largest risk factors in payday-style lending.
If you find yourself borrowing every month, the issue is likely structural cash flow — not lender selection.
5️⃣ Customer Experience & Transparency
Key areas to compare:
- Clarity of pre-agreement disclosure
- Ease of contacting support
- Hardship flexibility
- Complaint handling
Under the National Credit Act, lenders must provide clear breakdowns of total cost before you accept.
Always check:
- Is the repayment amount clearly stated?
- Are all fees listed?
- Is the debit order date specified?
Transparency is more important than marketing claims.
6️⃣ Which Lender Is Best for Which Situation?
Here’s a practical breakdown:
| Situation | Most Suitable Type of Lender |
|---|---|
| Small emergency under R2,000 | Any regulated short-term lender |
| Need above R4,000 | Higher-limit short-term provider |
| Already financially stretched | Consider instalment alternative |
| First-time borrower | Lower limit may reduce risk |
| Ongoing monthly shortfall | Structured longer-term product |
The best lender is not necessarily the one that approves you fastest.
It is the one whose repayment structure you can sustain.
Key Takeaway From This Comparison
Under South Africa’s regulated credit environment:
- Pricing structures are broadly similar
- Maximum limits vary slightly
- Approval algorithms differ
- The real risk lies in repayment pressure
Costs may differ between lenders depending on the loan category, amount, term, fees and individual offer.
Choosing between a very short repayment period and a longer instalment structure may make an even greater difference to your monthly cash flow.
That is the more important financial decision.
Expert Insight
Many borrowers compare lenders horizontally:
“Which payday lender is cheapest?”
But the more impactful comparison is vertical:
“Is a payday structure right for my situation?”
If you can repay comfortably in one cycle, short-term lending can function as an emergency bridge.
If not, comparing structured online loan options with extended repayment may reduce risk significantly.
If you want to see how Sunshine Loans compares side-by-side with other regulated lenders across loan limits, repayment terms, and approval criteria, you can review our full loan comparison hub where multiple providers are evaluated using consistent criteria.
What Happens If You Miss a Payment?
If you miss repayment:
- Debit order fails
- Bank may charge penalty fee
- Lender may apply default interest
- Account may be handed to collections
- Credit bureau listing may occur
Late payment impacts your credit profile and future borrowing ability.
If you expect repayment difficulties, contact the lender before the due date.
How a Sunshine Loan May Affect Your Credit Record
Sunshine Loans may use credit-bureau information when assessing an application. Applying for credit, taking out a new loan and making or missing repayments can all form part of your broader credit record.
Repaying according to the agreement may help you avoid adverse payment information. However, taking out a Sunshine loan does not guarantee that your credit score will improve.
If you miss payments, the consequences may include:
- Adverse information being reported to a credit bureau
- Greater difficulty qualifying for future credit
- Possible collection activity
If you are working on rebuilding credit, structured bad credit loan comparisons may offer more manageable repayment options.
When Sunshine Loans May Be a Good Choice
- Short-term emergency
- Stable salary
- One-time borrowing
- Clear repayment plan
When You Should Consider Alternatives
- Multiple existing loans
- Already short each month
- Need more than 49 days to repay
- Need over R4,000
Short-term loans are designed for temporary gaps — not ongoing financial pressure. If you are already managing multiple debts, regularly running short before payday, or relying on borrowing each month to cover essentials, a short repayment schedule can worsen the cycle rather than solve it. In these situations, the issue is often cash flow imbalance, not access to credit. Choosing a longer-term product with structured monthly repayments may reduce repayment shock and help stabilise your budget. The key question is not “Can I get approved?” but “Will this repayment leave me financially stable next month?”
Decision Framework Before Borrowing
Ask yourself:
- Can I repay in full without borrowing again?
- Is this expense urgent or emotional?
- Have I compared longer-term alternatives?
- Will this affect rent or essential bills?
- Am I using more than one short-term lender?
If unsure — pause.
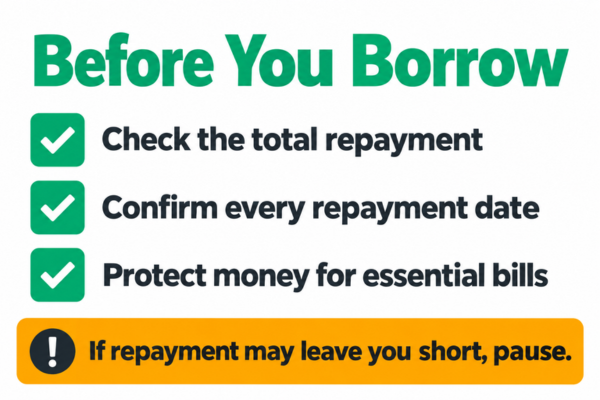
Responsible Borrowing Checklist
☑ Confirm total repayment
☑ Confirm debit order date
☑ Understand late fees
☑ Check early settlement options
☑ Ensure post-repayment affordability
Data Security & Privacy Considerations
Sunshine Loans collects:
- ID information
- Bank details
- Income data
Ensure:
- Website is secure (HTTPS)
- You are on official domain
- You understand privacy policy
Never share login credentials.
Before making a final decision, here are answers to the most common questions South African borrowers ask about Sunshine Loans.
Frequently Asked Questions
Is Sunshine Loans a legitimate lender in South Africa?
Yes. MoneySpot Finance SA (Pty) Ltd, trading as Sunshine Loans, is registered with the National Credit Regulator under NCRCP14110. Registration does not guarantee that a loan will be affordable, so always check the full cost and repayment terms before accepting an offer.
How much can I borrow from Sunshine Loans?
Sunshine Loans currently offers short-term loans from R500 to R4,000. The amount offered will depend on your income, existing financial commitments, credit profile and affordability assessment.
What is the Sunshine Loans repayment period?
Sunshine Loans currently advertises repayment periods of 4 to 49 days. Your repayment schedule should be shown in the quotation and credit agreement provided before you accept the loan.
How much interest does Sunshine Loans charge?
The cost depends on the amount borrowed, repayment term and whether it is your first or a subsequent short-term loan. Your quotation should show the interest, applicable fees, VAT and total amount repayable in rand.
Does Sunshine Loans perform a credit check?
Sunshine Loans considers credit and financial information when assessing an application. It also conducts an affordability assessment based on factors such as your income, expenses, existing commitments and recent banking activity. Approval is not guaranteed.
How quickly does Sunshine Loans pay out?
Sunshine Loans says applications submitted during business hours are typically processed quickly and that approved funds may arrive by the end of the business day. The actual timing depends on verification, approval and your bank’s processing times.
What do I need to apply for a Sunshine loan?
You generally need to be over 18, live in South Africa, be employed and receive a regular income. You should also have your South African ID, bank details and recent bank statements available when applying.
Can I get a Sunshine loan with bad credit?
A perfect credit history is not necessarily required, but approval will depend on Sunshine Loans’ assessment of your recent repayment history and ability to afford the loan. Sunshine Loans does not guarantee approval for applicants with bad credit.
What happens if I miss a repayment?
A missed repayment could result in additional charges, collection activity and adverse information being reported to a credit bureau. Contact Sunshine Loans as soon as possible if you believe you will be unable to pay on the agreed date.
Can I extend a Sunshine loan?
You should contact Sunshine Loans directly to ask what options may be available for your particular agreement. Do not assume that a loan can automatically be extended, and remember that changing a repayment arrangement could increase the total cost.
Can I repay a Sunshine loan early?
South African consumers generally have the right to settle a credit agreement early. Ask Sunshine Loans for a settlement figure so that you know the exact amount required and whether early payment will reduce the remaining cost.
Will a Sunshine loan affect my credit score?
It could. Applying for credit, opening a new loan and making or missing repayments may all affect your broader credit profile. Paying on time does not guarantee that your score will improve, while missed payments could make future borrowing more difficult.
Is it safe to apply for Sunshine Loans online?
Only apply through the official sunshineloans.co.za website and check that the connection is secure before entering personal information. Never give your banking password, PIN or one-time PIN to someone claiming that they can arrange approval for you.
How does Sunshine Loans compare with an instalment loan?
Sunshine Loans offers small amounts over a short period of 4 to 49 days. Instalment loans generally spread repayments over a longer period and may offer larger amounts, although a longer term can increase the total interest paid.
Should I compare lenders before applying?
Yes. Compare the amount available, repayment schedule, total cost and eligibility requirements—not only application or payout speed. The most suitable option is one whose repayments fit comfortably within your budget.
Final Expert Verdict
Sunshine Loans is a legitimate, NCR-registered short-term lender offering fast access to small emergency funds between R500 and R4,000. The application process is fully online, approval decisions are typically quick, and pricing structures operate within South Africa’s regulated National Credit Act framework.
However, legality does not equal affordability.
Because the repayment period is only 4 to 49 days, the real risk is not approval—it is whether the scheduled repayments will place too much pressure on your next pay cycle. For borrowers with stable income and a clear plan to repay on the agreed date, Sunshine Loans can function as a short-term emergency bridge. But for those already managing financial strain, juggling multiple debts, or experiencing recurring monthly shortfalls, this structure may increase stress rather than reduce it.
The most important factor is not speed of payout or marketing claims. It is whether the full repayment amount fits comfortably into your next pay cycle without forcing you to borrow again.
If you can repay confidently and the expense is genuinely urgent, Sunshine Loans may be suitable.
If you need more time, more flexibility, or lower monthly pressure, comparing structured alternatives before committing could provide greater long-term financial stability.
Borrow deliberately. Review the full pre-agreement statement. Understand the total cost in rand. And make a decision based on sustainability — not urgency.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.