Supreme Finance Loans Review South Africa (2026): Costs, Requirements & Safety
October 29, 2026
Is Supreme Finance a Good Loan Option in South Africa?
Last updated: October 2026
Supreme Finance offers personal loans to South Africans who need to borrow money and repay it over an agreed period. It advertises loans from R500 to R20,000, with applications available online and through branches.
But before applying, you need to know more than the maximum loan amount. How much will the loan cost? What documents must you provide? How long will approval take? And how can you make sure you are dealing with the real Supreme Finance?
This independent Supreme Finance review explains what the lender publishes, what remains unclear and what you should check before signing a credit agreement.
Quick verdict: Supreme Finance may be worth considering if you prefer a lender with physical branches and can provide regular income documents. However, its website does not clearly publish a standard interest rate, full fee schedule or exact repayment periods for all applicants. Ask for a written quotation before accepting any offer.
Supreme Finance Loans at a Glance
| Feature | Supreme Finance Details |
|---|---|
| Lender | Supreme Finance (Pty) Ltd |
| Loan amounts | R500 to R20,000 advertised |
| Loan types | Short- and longer-term personal loans |
| Repayment period | Flexible terms advertised; exact range not clearly published |
| Interest rate | Not clearly published; request a written quotation |
| Additional fees | Check the written quotation for applicable fees and credit life insurance |
| Application methods | Online form or branch |
| Documents | Original South African ID, latest three months’ bank statements and payslips |
| Approval speed | Website advertises approval within minutes; not guaranteed |
| Branch coverage | Branches across all nine provinces |
| NCR number published | NCRCP7342 |
| FSP number published | 46666 |
| Official website | supremefinance.co.za |
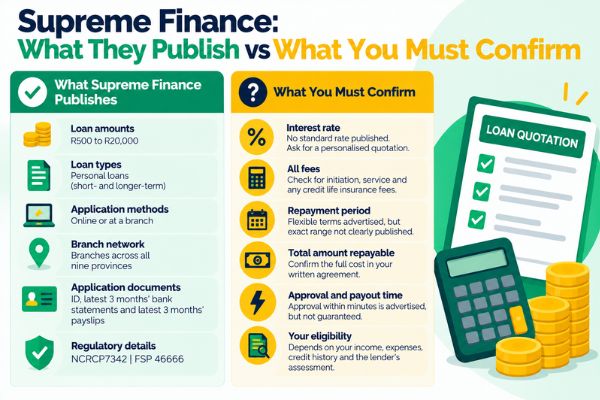
Important: These details describe publicly advertised products and requirements. They are not a personal loan offer. The amount, repayment term and total cost available to you will depend on the lender’s assessment and written agreement.
Who Is Supreme Finance?
Supreme Finance (Pty) Ltd is a South African credit provider offering personal loans through an online application process and a network of branches.
The company describes itself as an authorised microfinance service provider and says it is a member of Micro Finance South Africa (MFSA).
Supreme Finance publishes two regulatory numbers:
- NCRCP7342: Its credit provider registration number under the National Credit Regulator.
- FSP 46666: Its financial services provider number.
These numbers are useful when checking that you are dealing with the correct business. They should not be treated as a substitute for checking the current registration status.
You can independently verify a credit provider through the National Credit Regulator.
How Much Can You Borrow From Supreme Finance?
Supreme Finance advertises loans starting at R500 and going up to R20,000.
That does not mean every applicant can borrow R20,000.
The amount offered may depend on your income, regular expenses, existing debts, credit history and the lender’s affordability assessment.
For example, someone applying for R15,000 may be offered a smaller amount if the lender decides the larger repayment would be unaffordable.
Our advice: Work out how much you actually need before applying. Borrowing more than necessary means paying interest and possibly other charges on money you did not need.
What Are Supreme Finance’s Repayment Terms?
Supreme Finance advertises both short- and longer-term loans with flexible repayment options.
However, its main website does not clearly state one minimum and maximum repayment period that applies to all products.
That makes it difficult to compare the lender’s loans using the website alone.
Before accepting an offer, ask:
- How many repayments will I make?
- What is the amount of each repayment?
- On which dates will repayments be collected?
- How much will I repay in total?
- Can I settle the loan early, and what charges would apply?
Example: A R5,000 loan repaid over three months will have a different monthly payment and total interest cost from the same amount repaid over a longer period.
A smaller monthly instalment may be easier to manage, but a longer term can increase the total interest paid.
Always compare the total repayment amount, not just the monthly instalment.
Supreme Finance Interest Rates and Fees
Supreme Finance does not clearly display one standard interest rate or a complete product-by-product fee schedule on its main website.
This does not automatically mean the lender charges excessive fees. It means a visitor cannot calculate a reliable personal loan cost from the headline information alone.
Under South Africa’s National Credit Act, credit providers must follow the rules that apply to their type of credit agreement.
Depending on the product, your quotation may include:
- Interest: The charge for borrowing money.
- Initiation fee: A once-off fee for setting up the credit agreement, where permitted.
- Monthly service fee: A charge for administering the loan, where applicable.
- Credit life insurance: Insurance that may apply to certain credit agreements, subject to legal requirements.
- Default-related charges: Charges that may arise if you fail to repay, subject to the law and your agreement.
The exact fees must be confirmed in the pre-agreement statement and quotation provided to you.
How to Compare the Real Cost of a Supreme Finance Loan
Imagine you receive an offer for a R5,000 loan.
Do not compare lenders using the interest rate alone. Instead, write down these figures from each quotation:
| What to Compare | What You Need to Know |
|---|---|
| Loan amount | How much money you will actually receive |
| Interest | The rate and interest amount payable |
| Fees | Initiation, service and other permitted charges |
| Insurance | Any required credit life premium |
| Repayment period | How long you have to repay |
| Total repayment | The full amount you must pay back |
Simple calculation: If a quotation says you will receive R5,000 and repay R5,900 in total, the difference is R900.
The R900 represents the total borrowing cost above the amount received, including any interest, fees and insurance included in the quoted repayments.
This is only an example of how to read a quotation. It is not a Supreme Finance price estimate.
You can also use our loan calculator to explore how different interest rates and repayment periods affect instalments. A calculator estimate is not a lender quotation.
Supreme Finance Loan Requirements
Supreme Finance lists three main documents for loan applications:
- Your original South African identity document.
- Your latest three months’ bank statements.
- Your latest three months’ payslips.
The lender may also request other information to verify your identity, income, expenses and existing credit commitments.
Can You Apply Without Payslips?
Supreme Finance specifically lists payslips among its standard application documents.
It does not clearly explain on its main website whether applicants without formal payslips can use alternative proof of income.
If you are self-employed, work informally or receive income from another source, contact the lender before submitting an application.
Do not assume that bank statements alone will be accepted.
Can Pensioners Apply?
Supreme Finance’s standard website requirements focus on identity documents, bank statements and payslips.
Some third-party listings mention pensioner lending, but the main website does not clearly explain the current rules for pension income.
If you receive a pension, ask a branch whether your income type is accepted and which supporting documents are required.
Approval is not guaranteed.
How to Apply for a Supreme Finance Loan
Supreme Finance offers an online application form and a physical branch network.
Option 1: Apply Online
- Visit the official Supreme Finance application page.
- Complete the requested application details.
- Wait for the lender to contact you about the next steps.
- Provide the required documents through a verified channel.
- Review the written quotation if your application is approved.
- Accept the agreement only if you understand and can afford the repayments.
The official online page says applicants should complete the form and that Supreme Finance will contact them shortly.
Submitting the form does not mean the loan has been approved.
Option 2: Apply at a Branch
- Use the branch locator or branch list on the official website.
- Confirm the branch’s location and opening hours.
- Take your identity document and the required income documents.
- Ask the consultant to explain the loan amount, repayment period and total cost.
- Read the agreement before signing.
Applying at a branch may suit someone who wants to speak to a consultant or needs help with the application.
However, visiting a branch does not guarantee approval.
How Long Does Supreme Finance Take to Approve a Loan?
Supreme Finance advertises approval within minutes.
This is a promotional claim, not a guaranteed turnaround time for every application.
The lender may need to verify your documents, check your credit information and assess whether the repayments are affordable.
Approval and payment are also different steps. An approval message does not necessarily mean money has already reached your bank account.
Before relying on the money for an urgent expense, ask: When will the funds actually be paid, and are there any further checks?
If speed is your main concern, read our guide to instant loans in South Africa to understand the difference between fast decisions and actual payment times.
Does Supreme Finance Do Credit Checks?
Yes. Supreme Finance’s published application terms allow it to conduct a credit enquiry and confirm applicant details with credit bureaus or other relevant parties.
As a registered credit provider, it must also follow applicable affordability assessment requirements.
A credit check does not mean the lender will automatically reject everyone with a low score.
However, the lender must consider whether the loan is suitable and affordable based on the information available.
Can You Get a Supreme Finance Loan With Bad Credit?
Supreme Finance does not clearly publish a guaranteed minimum credit score for approval.
If you have missed payments, defaults or other negative information, your application may be more difficult to approve.
Your current income, expenses, existing debts and overall credit record can all matter.
There is no reliable basis for promising approval to someone with bad credit.
If you are struggling to qualify, read our guide to bad credit loans before making further applications.
Supreme Finance and Debt Review
Supreme Finance’s published application terms state that applicants confirm they are not currently under debt review, administration or sequestration.
This is important if you are already receiving formal debt assistance.
If you are under debt review, do not assume you can obtain a new loan simply because an online application form allows you to submit your details.
Speak to your registered debt counsellor about your options and the restrictions that apply.
Taking on more debt while struggling with existing repayments can make your financial situation worse.
Supreme Finance Branches and Contact Details
Supreme Finance says it operates across all nine South African provinces.
Its branch network is a practical difference from lenders that operate entirely online.
Use the official website to find current branch information rather than relying on an old address from a directory or social media post.
| Contact Method | Details |
|---|---|
| Official website | supremefinance.co.za |
| Telephone | 086 055 5440 |
| General email | [email protected] |
| Complaints email | [email protected] |
| Branch information | Official branch list |
| Regulatory and complaints information | Supreme Finance regulation page |
Contact details were taken from Supreme Finance’s official website. Confirm them again before sending sensitive personal information.
Supreme Finance Scam Warning: How to Avoid Fake Loan Offers
This is one of the most important things to understand before applying.
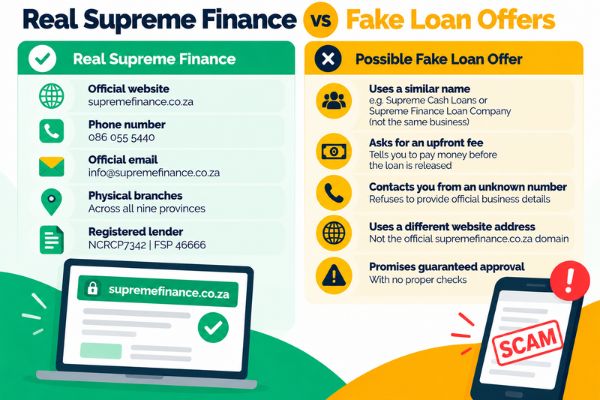
Supreme Finance has published a fraud warning stating that it is not associated with businesses using names such as Fusion Finance, Supreme Cash Loans or Supreme Finance Loan Company.
Someone using a similar name, logo or loan advertisement is not necessarily representing the registered Supreme Finance business.
Warning Signs of a Possible Loan Scam
- Someone asks you to pay an upfront fee to release a loan.
- You are told approval is guaranteed without any checks.
- A person contacts you from an unfamiliar number and refuses to provide official business details.
- You are asked to send money to a personal bank account.
- The website address is different from the official lender’s domain.
- You are pressured to act immediately or keep the arrangement secret.
Important: Do not pay an advance payment to an unknown person in exchange for a promised loan payout. Legitimate charges under a credit agreement are different from scam demands to transfer money before funds are released.
If you receive a suspicious Supreme Finance offer, contact the lender using the number published on its official website before sharing documents or making any payment.
For further guidance, visit our loan fraud alert page.
What Happens if You Cannot Repay a Supreme Finance Loan?
If you miss a repayment, contact Supreme Finance as soon as possible.
Depending on your agreement and the law, missed payments may lead to additional charges, collection activity and negative information being reported to credit bureaus.
Do not ignore calls, letters or notices about overdue debt.
Ask the lender to explain your outstanding balance and whether any repayment arrangement is available.
If you are struggling with several debts, consider speaking to a registered debt counsellor before taking on another loan.
How to Complain About Supreme Finance
Supreme Finance publishes a formal complaints process.
The company advises customers to start with their branch manager or consultant.
If the issue is not resolved, you can contact:
-
- Supreme Finance complaints: [email protected]
- Supreme Finance telephone: 086 055 5440
- National Credit Regulator: 0860 627 627 or ncr.org.za, for matters within its jurisdiction.
- National Financial Ombud Scheme: 0860 800 900 or nfosa.co.za, for complaints within its jurisdiction.
Keep copies of your agreement, payment records, emails and complaint reference numbers.
Not every complaint belongs with the same regulator or ombud. The appropriate escalation route depends on whether the problem concerns a credit agreement, insurance or another financial service.
Supreme Finance: Advantages and Limitations
| Potential Advantages | Limitations to Consider |
|---|---|
| Advertises loans from R500 to R20,000 | Maximum amount is not guaranteed |
| Online and branch applications | Income documentation is required |
| Branches across all nine provinces | Branch availability and hours must be checked |
| Publishes NCR and FSP registration numbers | Current registration status should still be verified |
| Advertises quick approval | No guaranteed payout time established |
| Publishes complaints and regulatory information | Standard rates, fees and repayment ranges are not clearly shown on the main website |
Who Might Consider Supreme Finance?
Supreme Finance may be worth comparing if you:
- Need to borrow between R500 and R20,000.
- Have the required identity and income documents.
- Prefer access to a physical branch.
- Want to compare an offer from a registered credit provider with other available options.
It may be less suitable if you cannot provide the required documents, need a guaranteed immediate payout or want to see a complete public price estimate before starting an application.
If you need a larger loan or a longer repayment period, compare other personal loan options.
For smaller borrowing needs, our short-term loan guide explains the costs and risks to consider.
Frequently Asked Questions About Supreme Finance Loans
Is Supreme Finance registered in South Africa?
Supreme Finance publishes NCR registration number NCRCP7342 and FSP number 46666 on its official website. Check the relevant official registers to confirm the current status before applying.
How much can I borrow from Supreme Finance?
Supreme Finance advertises personal loans from R500 to R20,000. The amount you may qualify for depends on the lender’s affordability and credit assessment.
What documents do I need for a Supreme Finance loan?
Supreme Finance lists an original South African ID, the latest three months’ bank statements and the latest three months’ payslips as its standard application documents.
Can I apply for a Supreme Finance loan online?
Yes. Supreme Finance provides an online application form on its official website. You can also enquire about applying through one of its branches.
How long does Supreme Finance take to approve a loan?
Supreme Finance advertises approval within minutes, but actual processing time depends on verification and affordability checks. Approval does not guarantee immediate payment.
What interest rate does Supreme Finance charge?
Supreme Finance does not clearly publish one standard interest rate for every loan on its main website. Request a written quotation showing the interest, fees, repayment period and total amount repayable.
Can I get a Supreme Finance loan with bad credit?
Approval is not guaranteed. Supreme Finance may consider your credit history, income, expenses and existing debts. It does not clearly publish a guaranteed minimum credit score for approval.
Does Supreme Finance accept people under debt review?
Its published application terms state that applicants confirm they are not currently under debt review. If you are under debt review, speak to your registered debt counsellor before considering further credit.
Does Supreme Finance charge an upfront fee?
Supreme Finance warns about loan scams and unrelated businesses using similar names. Do not pay an unknown person an advance fee to release a promised loan. Confirm any legitimate loan charges in the written agreement.
What is the Supreme Finance contact number?
Supreme Finance publishes 086 055 5440 as its telephone number and [email protected] as its general email address. Verify contact details on the official website before sharing personal information.
Final Verdict: Is Supreme Finance Worth Considering?
Supreme Finance has several features that may appeal to borrowers, including a nationwide branch network, online applications and advertised loans of up to R20,000.
It also publishes regulatory details and a complaints process, which makes it easier to identify the business and raise concerns.
However, there is an important limitation: the main website does not provide enough standard pricing information to calculate the full cost of a loan before receiving a quotation.
Our recommendation: Supreme Finance is worth considering as one option to compare, particularly if you prefer access to a branch. But do not choose it based only on the advertised loan amount or quick-approval claim.
Request a written quotation, check the total repayment amount and compare it with other lenders before signing.
If you would like to explore alternatives, you can compare loans in South Africa and review the costs and repayment terms available to you.
Sources and References
- Supreme Finance – Official Website
- Supreme Finance – Services and Application Requirements
- Supreme Finance – Online Application
- Supreme Finance – Application Terms and Conditions
- Supreme Finance – Regulation and Complaints
- Supreme Finance – Company Information and Fraud Warning
- National Credit Regulator – Registration and Consumer Information
Sources reviewed: October 2026. Published: November 2026. Product details, eligibility requirements, contact information and regulatory status may change. Confirm current terms directly with Supreme Finance and the relevant regulators.
Editorial disclosure: This independent review was prepared by FatCat Loans using publicly available information. FatCat Loans is not Supreme Finance and cannot guarantee loan approval, rates or payment times. Any loan comparison or application service offered by FatCat Loans is separate from Supreme Finance. Borrowers should review all applicable terms before entering a credit agreement.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.