African Bank Loans: What South Africans Should Know Before Applying
December 16, 2025
Introduction to African Bank Loans
Last Updated: September 2026
African Bank is a South African bank offering unsecured personal loans with fixed repayments. Qualifying borrowers can currently access personal loans of up to R350,000, with repayment periods extending up to 72 months.
Unlike short-term lenders that typically provide smaller amounts repayable over a few weeks or months, African Bank’s personal loans are designed for larger borrowing needs that can be repaid over several years.
However, the amount you’re approved for, your interest rate and the total cost of borrowing depend on your credit profile, affordability and African Bank’s assessment.
This African Bank Loans review looks at its current loan amounts, repayment terms, interest rates, fees, requirements, application process and credit checks, as well as what to consider before accepting an offer.
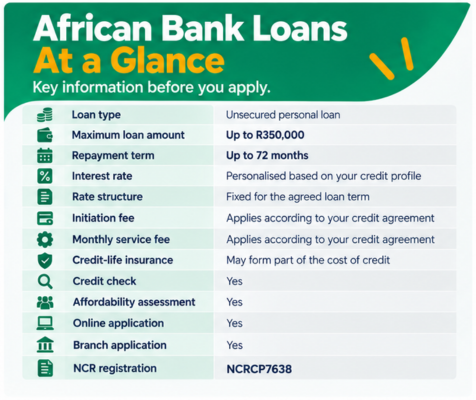
African Bank Loans at a Glance
| Feature | African Bank Personal Loan |
|---|---|
| Loan type | Unsecured personal loan |
| Maximum loan amount | Up to R350,000 |
| Repayment term | Up to 72 months |
| Interest rate | Personalised based on your credit profile and affordability assessment |
| Rate structure | Fixed for the agreed loan term |
| Initiation fee | May apply according to your credit agreement |
| Monthly service fee | May apply according to your credit agreement |
| Credit-life insurance | May form part of the cost of credit |
| Credit check | Yes |
| Affordability assessment | Yes |
| Online application | Yes |
| Branch application | Yes |
| Lender | African Bank Limited |
| NCR registration | NCRCP7638 |
Loan amounts, repayment terms, interest rates and fees are subject to African Bank’s lending criteria, affordability assessment and your individual credit profile. Always check your personalised quotation and pre-agreement statement before accepting credit.
Understanding African Bank as a Lender
African Bank operates as a registered retail bank in South Africa with a strong focus on personal lending. Unlike short-term or digital-only lenders, African Bank follows a more traditional banking model, combining structured credit assessments with longer repayment periods.
Because of this, African Bank is commonly associated with:
- Formal affordability assessments
- Fixed repayment structures
- Medium- to long-term loan products
African Bank is often compared with other banks and institutional lenders rather than short-term credit providers.
African Bank Limited is also a registered credit provider under NCRCP7638. This means its lending is subject to South Africa’s consumer-credit rules, including requirements around affordability assessments and credit disclosure.
What Types of Loans Does African Bank Offer?
African Bank’s lending options are designed primarily around structured personal credit rather than very small payday-style borrowing.
African Bank Personal Loan
African Bank’s standard personal loan allows qualifying borrowers to access up to R350,000, with repayment terms extending up to 72 months.
The loan is unsecured, meaning you don’t generally provide a house or vehicle as security. Instead, approval and pricing depend on factors such as your income, expenses, existing financial commitments, credit profile and affordability.
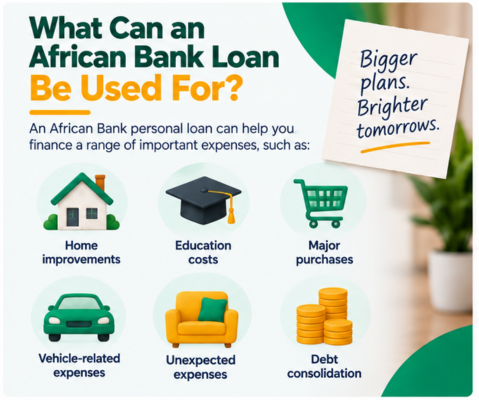
Personal loans may be used for purposes such as home improvements, education costs, major purchases or unexpected expenses.
African Bank Consolidation Loan
African Bank also provides debt-consolidation options designed to combine qualifying existing credit commitments into a more manageable repayment structure.
Debt consolidation doesn’t make debt disappear. Existing debts are replaced or settled using new credit, so it’s important to compare the new interest rate, fees, repayment period and total cost with what you’re currently paying.
A lower monthly repayment can improve short-term cash flow, but extending the debt over a longer period can sometimes increase the total amount repaid.
African Bank 12% Loan
You may also come across searches and promotions for an African Bank 12% loan.
Don’t assume that 12% is the standard rate available to every African Bank applicant. Promotional or qualifying rates can have specific eligibility criteria, loan limits and terms.
Always check whether a particular advertised rate applies to you and compare the complete cost shown in your personalised quotation rather than choosing a loan based on the headline interest rate alone.
It’s often useful to estimate your monthly repayments before applying so you understand what may fit your budget.
Who Typically Considers African Bank Loans?
African Bank loans are commonly considered by:
- Salaried individuals with stable, verifiable income
- Borrowers seeking structured repayment plans
- Consumers who prefer traditional banking institutions
Because African Bank offers longer repayment periods than many short-term lenders, it may appeal to borrowers who need a larger amount but want to spread the cost over a structured monthly repayment period.
However, a longer term doesn’t automatically make a loan more affordable overall. Smaller monthly instalments can mean paying interest and fees for longer.
African Bank Loan Requirements and Eligibility
African Bank assesses applications individually. Meeting the basic requirements doesn’t guarantee that your application will be approved or that you’ll qualify for the maximum advertised amount.
The assessment can consider factors including:
- your age and identity
- regular and verifiable income
- existing debts and monthly commitments
- normal living expenses
- your credit history
- your ability to afford the proposed repayment
African Bank performs both credit and affordability assessments before granting credit.
This means the amount one applicant qualifies for can be very different from the amount available to another person, even where they earn similar incomes.
What Documents Do You Need for an African Bank Loan?
The documents required can depend on your circumstances and application channel, but you should be prepared to provide information that allows African Bank to verify your identity, income and affordability.
This may include:
- South African ID: to verify your identity
- Proof of income: such as a recent payslip
- Bank statements: African Bank may require recent statements showing your income
- Proof of residence: this may be required depending on your circumstances
- Banking details: for verification, payment and repayment purposes
Having the required documents available can help prevent delays, but providing them doesn’t guarantee approval.
African Bank Interest Rates and Fees
The cost of an African Bank loan isn’t determined by the amount borrowed alone.
Your total cost can include interest, fees and credit-life insurance, so it’s important to review the complete quotation rather than focusing only on the monthly instalment.
Interest rate
African Bank uses personalised, risk-based pricing.
This means your interest rate can depend on factors such as your credit profile, income, affordability, amount borrowed and repayment period.
Once agreed, the applicable rate is generally fixed for the loan term, giving you greater certainty about your scheduled repayments.
Initiation fee
An initiation fee may be charged when the loan is established.
The amount applicable to your loan should be clearly disclosed in your pre-agreement statement and quotation.
Monthly service fee
A monthly service fee can also form part of the cost of maintaining the credit agreement.
Although a monthly fee may appear relatively small, remember that it can be charged repeatedly over a multi-year loan.
Credit-life insurance
Credit-life insurance may also form part of the cost of borrowing.
Depending on the policy and agreement, this type of insurance can provide cover for the outstanding debt in specified circumstances such as death, disability or certain forms of loss of income.
Check the premium, benefits, exclusions and conditions applicable to your particular policy.
Total cost of credit
The most useful figure isn’t necessarily your monthly instalment.
Look at the total amount repayable over the entire loan term.
For example, extending a loan from three years to six years may reduce the monthly instalment, but it also means you’re potentially paying interest, service fees and insurance for much longer.
Always compare:
- the amount you receive
- your interest rate
- monthly repayment
- fees
- insurance
- number of repayments
- total amount repayable
How Much Could an African Bank Loan Cost?
Because African Bank uses personalised pricing, there isn’t one repayment figure that applies to every borrower.
Two people borrowing the same amount over the same period could potentially receive different interest rates based on their individual credit and affordability assessments.
For this reason, your personalised quotation is more useful than a generic repayment example.
When you receive an offer, compare:
| What to check | Why it matters |
|---|---|
| Loan amount | How much credit you’re actually receiving |
| Interest rate | The rate charged on your agreement |
| Loan term | How long you’ll be repaying the debt |
| Monthly instalment | What must fit into your monthly budget |
| Fees | Additional charges that increase borrowing costs |
| Credit-life premium | Insurance costs that may form part of your repayment |
| Total repayment | The total rand amount you’ll repay over the agreement |
The final figure is particularly important. A loan with a comfortable monthly instalment isn’t necessarily inexpensive if you’re making that payment for several years.
How Does the African Bank Loan Calculator Work?
An online loan calculator can help you understand how changing the loan amount or repayment period could affect your monthly repayment.
However, a calculator result shouldn’t be treated as guaranteed approval or a final quotation.
Your actual African Bank offer can depend on:
- the amount you apply for
- your chosen or approved repayment term
- your personalised interest rate
- applicable fees
- credit-life insurance
- your credit profile
- your affordability assessment
Use calculator results as a budgeting guide and rely on your final pre-agreement statement and quotation when assessing the actual cost of the loan.
Advantages of African Bank Loans
Large personal loan amounts
Qualifying borrowers can access personal loans of up to R350,000.
Longer repayment periods
Terms extending up to 72 months can allow larger borrowing amounts to be spread over several years.
Fixed repayment structure
A fixed agreed rate and structured instalments can make monthly budgeting more predictable.
Established South African bank
African Bank is an identifiable regulated bank and registered credit provider.
Online access
Borrowers can begin the loan process digitally rather than relying exclusively on a branch.
Potential Drawbacks of African Bank Loans
Your advertised maximum isn’t guaranteed
The fact that African Bank offers personal loans of up to R350,000 doesn’t mean every applicant can borrow that amount.
Rates are personalised
You won’t necessarily know your final borrowing cost until African Bank assesses your application.
Longer terms can increase total costs
Extending repayments can reduce the monthly instalment but may increase the total interest, fees and insurance paid over the life of the loan.
Credit and affordability checks apply
African Bank doesn’t offer guaranteed approval. Your application remains subject to its lending criteria.
Insurance and fees can add to borrowing costs
The interest rate isn’t necessarily the only cost you’ll pay, so check the total amount repayable before accepting an offer.
How to Apply for an African Bank Loan
Step 1: Decide how much you need
Before applying, consider the amount you genuinely need rather than automatically requesting the maximum available.
Step 2: Start your application
African Bank provides digital application options, and assistance may also be available through its other customer-service channels.
Step 3: Provide your personal and financial information
You’ll need to provide information that allows African Bank to verify your identity, income and financial circumstances.
Step 4: Complete the credit and affordability assessment
African Bank assesses your credit profile and whether the proposed repayment is affordable based on your financial circumstances.
Step 5: Receive your offer
If approved, you’ll receive the terms available to you. The amount and rate may differ from headline advertising because pricing is personalised.
Step 6: Review the quotation
Before accepting, check your:
- loan amount
- interest rate
- repayment period
- monthly instalment
- initiation fee
- monthly service fee
- credit-life insurance
- total amount repayable
Step 7: Accept the agreement
Only accept the loan once you understand the repayment obligation and are confident it fits your budget.
Step 8: Receive the funds
Once the agreement has been accepted and African Bank’s remaining requirements have been completed, approved funds can be paid to the relevant bank account.
Does African Bank Perform a Credit Check?
Yes. African Bank assesses your creditworthiness as part of its lending process.
A credit assessment helps the bank understand factors such as your existing debts, repayment history and overall credit profile.
African Bank also needs to assess affordability.
This means claims about “guaranteed African Bank loans” or “African Bank loans with no credit check” should be treated cautiously because they don’t accurately describe the normal lending process.
If you’re unsure how lender enquiries work, read our guide to soft and hard credit checks in South Africa.
Can You Get an African Bank Loan With Bad Credit?
Having a weaker credit profile doesn’t allow us to predict whether African Bank will approve or decline your application.
The bank considers your application according to its own lending criteria and affordability requirements.
Factors that may influence the outcome include:
- your repayment history
- existing debts
- recent credit applications
- income
- expenses
- affordability
There isn’t one universal credit-score number that guarantees African Bank approval.
If you’re struggling to qualify for mainstream personal credit, you can learn more about loan options for bad credit in South Africa.
Be cautious about repeatedly submitting applications to multiple lenders after being declined. Multiple credit applications over a short period can result in additional enquiries appearing on your credit profile, while doing nothing to address the affordability or credit issues that caused the original decline.
How Long Does an African Bank Loan Take to Approve?
African Bank doesn’t guarantee that every application will be approved or paid out within the same timeframe.
Processing can depend on factors such as:
- whether your application is complete
- income and document verification
- credit assessment
- affordability checks
- whether additional information is required
- acceptance of the final agreement
A quick online application shouldn’t be confused with guaranteed instant approval.
If you need money for a time-sensitive expense, confirm the expected processing and payout timeframe directly with African Bank rather than assuming the funds will arrive on a particular day.
Who Might an African Bank Loan Suit?
An African Bank personal loan may be worth considering if you:
- have stable and verifiable income
- need a larger personal loan rather than very short-term credit
- want structured monthly repayments
- want to spread a significant expense over a longer period
- can comfortably afford the repayment
- understand the complete cost of the agreement
It may be less suitable if:
- you’re already struggling to meet existing debt repayments
- you need guaranteed approval
- you want very small, very short-term borrowing
- the monthly instalment would leave little money for essential expenses
- you’d need to borrow again simply to make the repayments
The important question isn’t simply whether African Bank is willing to lend you the money.
It’s whether the repayment comfortably fits your budget for the entire loan term.
African Bank vs Other Personal Loan Providers
African Bank isn’t the only provider offering larger personal loans in South Africa.
Before choosing a lender, compare the amount available, repayment period, personalised interest rate, fees, insurance and total amount repayable.
African Bank vs ABSA
Both African Bank and ABSA offer personal loans to South African borrowers, with approval and pricing based on individual circumstances.
Rather than choosing solely on the maximum advertised loan amount, compare the actual offer available to you from each provider — particularly the interest rate, repayment term and total cost.
Read our full ABSA Loans review for current product information.
African Bank vs Sanlam
Sanlam is another established financial-services provider offering personal credit options.
The right choice depends on the amount you need, the rate you’re offered, repayment period, fees and whether the resulting instalment comfortably fits your budget.
See our Sanlam Loans review for a closer look at its offering.
African Bank vs Short-Term Lenders
African Bank’s mainstream personal loan serves a different purpose from small short-term loans.
A longer personal loan can spread the cost over several years, while short-term credit generally needs to be repaid much sooner.
Neither is automatically cheaper.
Compare the total amount repayable, not simply the repayment period or advertised interest rate.
Is African Bank Legit?
Yes. African Bank Limited is an established South African bank and registered credit provider.
African Bank identifies itself under registration number 2014/176899/06 and credit-provider registration NCRCP7638.
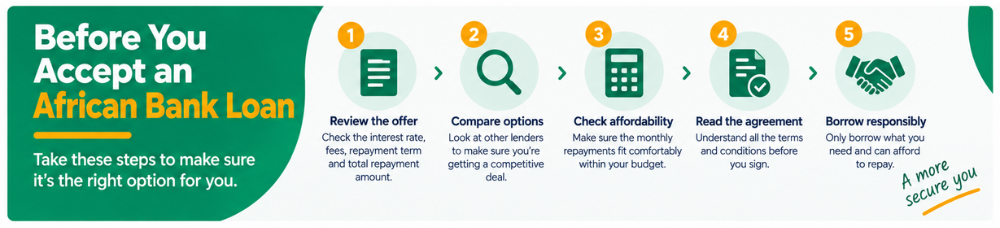
Being a registered provider doesn’t mean every loan it offers will be suitable for every borrower. You should still assess the interest rate, fees, insurance, repayment term and total cost before accepting credit.
Consumers can also use the National Credit Regulator as an independent source of information about regulated credit in South Africa.
Compare African Bank With Other Loan Options
African Bank is one borrowing option, but applying directly to a single lender isn’t the only way to explore personal credit.
FatCat Loans is a comparison service rather than a lender. You can submit one online request to see whether loan options may be available from participating providers.
We’re not affiliated with African Bank and can’t guarantee that African Bank will be one of the options presented.
Using a comparison service can help you explore available options before deciding what type of loan may suit your circumstances.
Before accepting any offer, compare:
- amount borrowed
- interest rate
- fees
- insurance
- repayment period
- monthly repayment
- total amount repayable
African Bank Loan Scams and Safety Tips
Well-known lender names can be used by scammers to make fraudulent loan offers appear legitimate.
If someone contacts you claiming to represent African Bank:
- verify the contact details through African Bank’s official website
- be cautious of unsolicited WhatsApp, SMS or social-media loan offers
- never share your banking PIN, password or one-time PIN with someone offering a loan
- don’t assume an offer is genuine simply because it uses African Bank’s name or logo
- be suspicious of anyone promising guaranteed approval regardless of your finances
- confirm unexpected payment requests directly with African Bank before sending money
If you’re unsure whether a communication is genuine, contact African Bank using contact information obtained independently from its official website rather than the details contained in the suspicious message.
Frequently Asked Questions About African Bank Loans
How much can I borrow from African Bank?
African Bank currently advertises personal loans of up to R350,000. The amount available to you depends on your credit profile, income, affordability and African Bank’s assessment.
What interest rate does African Bank charge?
African Bank uses personalised pricing, so there isn’t one standard interest rate that applies to every borrower. Your actual rate should be shown in your personalised quotation before you accept the loan.
What do I need to qualify for an African Bank loan?
You’ll need to meet African Bank’s eligibility, credit and affordability requirements. The bank may require identification, proof of income, bank statements and other supporting information depending on your application.
How long does African Bank take to approve a loan?
Processing times can vary. Approval depends on factors such as completing the application, providing the required documents, credit and affordability assessments and any additional verification African Bank requires.
Does African Bank check your credit?
Yes. African Bank assesses creditworthiness and affordability when considering loan applications. Approval is not guaranteed.
Is African Bank registered with the NCR?
Yes. African Bank Limited is identified as a registered credit provider under NCRCP7638.
Final Verdict: Is an African Bank Loan Worth Considering?
African Bank is an established South African bank offering personal loans of up to R350,000 with repayment periods extending up to 72 months for qualifying borrowers.
That makes it potentially worth considering if you need a larger personal loan and want to repay it through structured monthly instalments rather than using very short-term credit.
However, the maximum advertised amount isn’t guaranteed, and African Bank uses personalised pricing. The rate, amount and terms you’re offered will depend on your individual credit profile and affordability assessment.
Longer repayment periods also need careful consideration.
Spreading a loan over several years can make the monthly instalment easier to manage, but it can also mean paying interest, service fees and insurance for much longer.
Before accepting an African Bank loan, compare the amount you’ll receive, monthly repayment, interest rate, fees, insurance, repayment period and total amount repayable.
Most importantly, make sure the repayment comfortably fits your budget without compromising essential expenses or forcing you to borrow again.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.