Debt Consolidation Meaning in South Africa: How It Works
May 08, 2024
Debt Consolidation Meaning in South Africa
Updated October 2026
Debt consolidation means combining two or more existing debts into one new loan, usually with a single monthly repayment. In South Africa, people may consider debt consolidation when they have several credit accounts, personal loans or store accounts with different repayment dates and interest rates.
The main purpose is to make existing debt easier to manage. Depending on the interest rate, fees and repayment period of the new loan, consolidation may also reduce monthly repayments or borrowing costs. However, savings are not guaranteed.
This guide explains what debt consolidation means, how it works in practice, which debts may be included and when it might be worth considering.
What Does Debt Consolidation Mean in South Africa?
Debt consolidation is a form of refinancing. Instead of continuing to repay several separate debts, you take out a new loan and use it to settle eligible existing balances.
If the consolidation is completed successfully, you repay the new loan according to its agreed terms.
Debts that may be eligible for consolidation include:
- Credit card balances
- Store accounts
- Personal loans
- Short-term loans
- Other qualifying unsecured credit agreements
Eligibility depends on the lender, the type of debt and your financial circumstances. Not every account or outstanding balance can necessarily be consolidated.
Important: Debt consolidation does not cancel or forgive what you owe. It replaces eligible existing debt with a new repayment obligation.
Debt Consolidation Example in South Africa
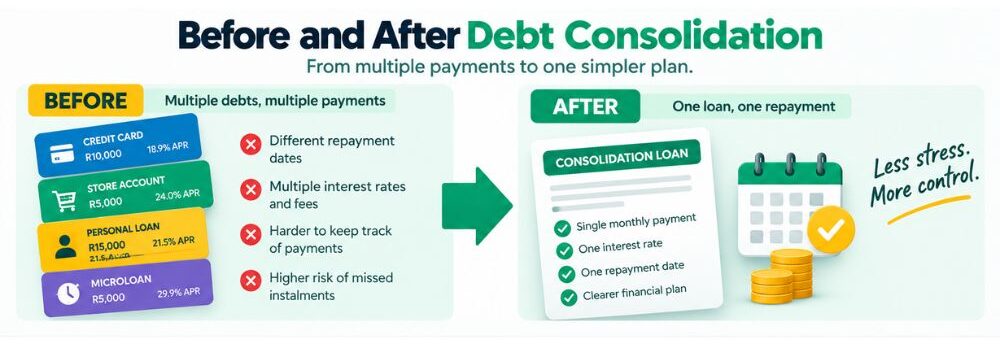
Imagine you have three outstanding debts:
- Credit card: R10,000
- Store account: R5,000
- Personal loan: R15,000
Your total outstanding debt is R30,000.
If a lender approves a suitable R30,000 consolidation loan, the money could be used to settle those three balances. You would then repay the new loan through one monthly instalment rather than making three separate payments.
This example illustrates how consolidation works. It does not mean your monthly repayment or total borrowing cost will necessarily decrease.
The new loan’s interest rate, fees and repayment term determine whether it is financially worthwhile. A longer repayment period can reduce the monthly instalment while increasing the total interest paid.
For a more detailed explanation, read our guide to how debt consolidation loans work in South Africa.
Benefits of Debt Consolidation
Knowing what consolidation means empowers you to make informed financial decisions. Here are some key benefits:
1️⃣ Fewer Monthly Payments:
Managing one repayment may make budgeting easier.
2️⃣Potentially Lower Borrowing Costs:
Possible if the new loan’s total cost is lower, including fees.
3️⃣ More Predictable Repayments:
A fixed-term loan can provide a defined repayment schedule.
For more financial guidance, explore resources at the National Credit Regulator (NCR).
4️⃣ Possible Monthly Cash-Flow Relief:
A lower instalment may help, but extending the term can cost more overall.
5️⃣ An Opportunity to Simplify Debt Management:
Consolidation may help with organisation, but doesn’t automatically improve a credit score or resolve overspending.
What If Debt Consolidation Is Not Right for You?
Debt consolidation is not suitable for everyone. If you cannot comfortably afford the repayments on a new loan, borrowing more money may make your financial position worse.
Other options worth exploring include:
- Contacting existing creditors: Ask whether alternative payment arrangements may be available.
- Reviewing your household budget: Identify essential expenses and determine what you can realistically afford to repay.
- Prioritising existing debt repayments: Consider a structured repayment strategy if you can meet your obligations without refinancing.
- Seeking debt counselling: If you are over-indebted, an NCR-registered debt counsellor can assess whether debt review may be appropriate.
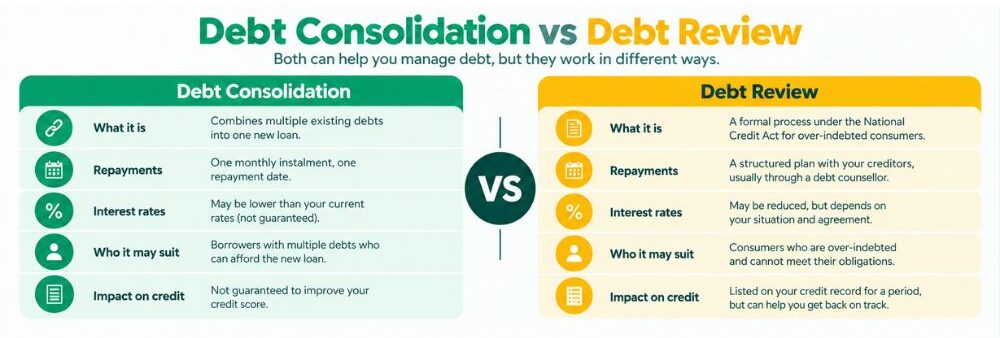
Debt review is different from taking out a consolidation loan. It is a regulated process under South Africa’s National Credit Act and may be more appropriate for consumers who are unable to meet their existing credit obligations.
You can find information about registered debt counsellors and consumer protections through the National Credit Regulator.
Does Your Credit Score Matter for Debt Consolidation?
Yes. Your credit history is one of several factors lenders may consider when assessing a debt consolidation loan application in South Africa.
Lenders may assess:
- Credit history: How you have managed previous credit agreements and repayments.
- Income: Whether you have sufficient, verifiable income to support the proposed repayments.
- Existing debt: Your current credit commitments and outstanding balances.
- Affordability: Whether you can reasonably afford the new loan alongside your essential living expenses and other financial obligations.
A stronger credit profile may improve your chances of qualifying for more favourable terms, but approval and interest rates depend on the lender’s assessment. A good credit score does not guarantee approval.
Before applying, consider checking your credit report through a registered South African credit bureau. This can help you identify inaccurate information and understand your existing credit commitments.
For more information about eligibility, read our guide to debt consolidation loan approval in South Africa.
How Debt Consolidation Works from Start to Finish
Understanding debt consolidation is only the first step. Here’s how the actual process works:
Step 1 – List Your Debts
Write down:
- Balances
- Interest rates
- Minimum monthly payments
- Due dates
This helps you determine whether consolidation will save you money.
Step 2 – Explore Debt Consolidation Loan Options
Research available debt consolidation loan options and compare important details such as interest rates, fees, repayment periods and total repayment costs.
FatCat Loans is a loan comparison and matching service, not a lender. You can use the platform to explore available loan options, but eligibility, approval and final loan terms are determined by the lender.
Step 3 – Submit Your Application
If you decide to proceed, you may need to provide information and supporting documents for the lender’s affordability and credit assessment.
Depending on the lender, this may include:
- Valid identification
- Proof of income or other income information
- Recent bank statements
- Proof of residential address
- Details of your existing debts
Requirements vary between lenders. Submitting an application does not guarantee approval.
Step 4 – Settle the Existing Debts
If your consolidation loan is approved and paid out, the funds are used to settle the eligible debts included in the arrangement.
Depending on the lender and loan agreement, funds may be paid directly to creditors or provided to you for settlement.
Confirm that the intended debts have been settled and retain any settlement confirmations. Paying off a credit account does not necessarily mean the account has been closed.
Step 5 – Repay the New Loan
You then repay the consolidation loan according to its agreed interest rate, repayment schedule and loan term.
Continue making repayments on time and avoid accumulating new debt on accounts that remain open.
Common Debt Consolidation Mistakes to Avoid
Understanding what debt consolidation means also involves recognising the risks. Some common mistakes include:
Taking on New Debt After Consolidation
If you continue borrowing on credit cards or store accounts after settling their balances, you could end up with both the consolidation loan and new outstanding debts.
Looking Only at the Monthly Instalment
A lower monthly repayment does not necessarily mean a cheaper loan. Extending the repayment period may increase the total interest paid.
Overlooking Fees and Loan Terms
Check the applicable interest rate, initiation fees, monthly service fees, total repayment amount and any relevant early-settlement terms before accepting an offer.
Not Comparing the Total Cost
Compare the total amount repayable on the new loan with the cost of continuing to repay your existing debts. Consider the repayment period as well as the monthly instalment.
Failing to Confirm Existing Debts Are Settled
After consolidation, check that the intended creditors have received payment and that the relevant balances have been updated. Keep settlement records and check whether any accounts remain open.
Frequently Asked Questions About Debt Consolidation
What does debt consolidation mean in simple terms?
Debt consolidation means combining two or more existing debts into one new loan. The new loan is used to settle eligible outstanding balances, leaving you with one repayment arrangement for the consolidated debt.
Does debt consolidation reduce the amount you owe?
Not automatically. Debt consolidation usually replaces existing debt rather than reducing or cancelling it. Whether it saves money depends on the new interest rate, fees and repayment period.
Does debt consolidation improve your credit score?
Not automatically. Your credit score may change depending on the new credit application, your repayment history, outstanding balances and how you manage your accounts after consolidation. Making repayments on time can support a healthier credit history over time.
Can anyone qualify for a debt consolidation loan?
No. Lenders assess factors such as income, affordability, credit history and existing financial obligations. Approval is not guaranteed, and consumers under debt review are generally restricted from taking on further credit.
Is debt consolidation the same as debt review?
No. Debt consolidation involves taking out a new loan to settle eligible existing debts. Debt review is a regulated process under South Africa’s National Credit Act for consumers who are over-indebted. It involves a registered debt counsellor and does not work in the same way as refinancing.
If you are considering combining existing debts, you can explore debt consolidation loan options in South Africa to learn more about the available options and what to consider before applying.
Conclusion: Understanding Debt Consolidation in South Africa
Debt consolidation means combining eligible existing debts into one new loan, usually with a single monthly repayment. For some South Africans, this can make repayments easier to organise and may offer more suitable loan terms.
However, consolidation does not eliminate debt or guarantee lower borrowing costs. Before deciding whether it is worthwhile, compare the new loan’s interest rate, fees, repayment period and total amount repayable against your existing commitments.
If you are struggling to afford essential expenses or meet your current debt repayments, consider speaking to your creditors or an NCR-registered debt counsellor before taking on further credit.
FatCat Loans is a loan comparison and matching service, not a lender. Loan approval, affordability assessments and final credit terms are determined by the lender.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.