Debt Consolidation Loan Approval South Africa (2026 Guide)
October 09, 2025
How Debt Consolidation Loan Approval Works in South Africa
Last Updated: October 2026
Applying for a debt consolidation loan involves more than checking your credit score. Credit providers must consider your income, existing debts, monthly expenses and ability to afford the proposed repayments.
If you have several outstanding credit agreements, consolidation may allow you to combine eligible debts into one new loan. However, approval is not guaranteed, and a new loan does not automatically reduce your monthly repayment or total borrowing costs.
This guide explains debt consolidation loan approval in South Africa, the factors credit providers may assess, documents you may need and practical steps to take before applying.
What Does Debt Consolidation Loan Approval Mean?
Debt consolidation loan approval means a credit provider has assessed your application and agreed to offer a new credit agreement, subject to its terms and any outstanding requirements.
The new loan may be used to settle eligible existing debts, leaving you with a new repayment schedule. The provider will consider whether you qualify and can afford the proposed repayments.
For a broader explanation of the product, visit our debt consolidation loans in South Africa page.
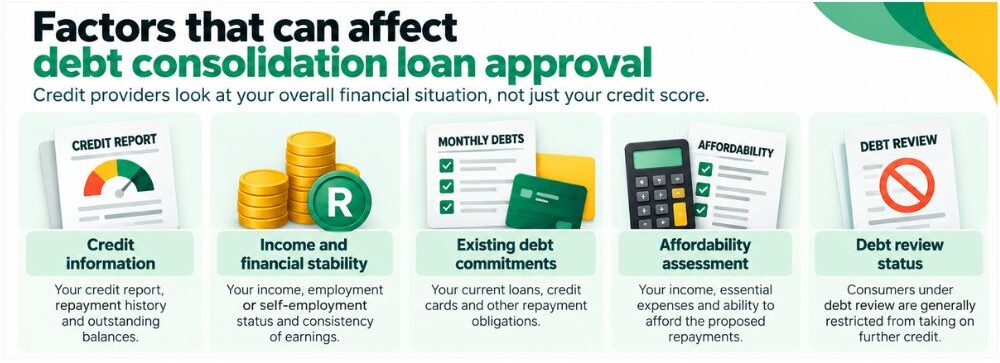
Factors That Affect Debt Consolidation Loan Approval
1. Your Credit Information
Credit providers may review your credit report, repayment history, outstanding balances and other relevant credit information.
A poor credit history may limit your options, but there is no single credit score that guarantees approval across all providers.
2. Income and Financial Stability
Providers may assess your income, employment or self-employment circumstances and the consistency of your earnings.
Having a regular income may support an application, but it does not guarantee approval.
3. Existing Debt Commitments
Credit providers consider your existing repayment obligations when assessing whether you can afford another credit agreement.
Having several outstanding loans does not automatically prevent approval, but high repayment commitments may limit the amount you can afford.
4. Debt-to-Income Ratio
Your debt-to-income ratio compares your monthly debt repayments with your monthly income.
Debt-to-income ratio = (Monthly debt repayments ÷ Monthly income) × 100
For example, if your monthly debt repayments total R6,000 and your monthly income is R20,000, your debt-to-income ratio is 30%.
This calculation can help you understand your debt commitments, but it does not replace the affordability assessment required under South African credit regulations.
There is no universal debt-to-income percentage that guarantees debt consolidation loan approval.
5. Affordability Assessment
Under the National Credit Act and applicable regulations, credit providers must assess affordability before granting credit.
This may involve reviewing your income, necessary living expenses, existing debt obligations and other relevant financial information.
A provider may decline an application if the proposed repayments are not considered affordable.
6. Debt Review Status
Consumers under debt review are generally restricted from taking on further credit. A consolidation loan should not be treated as a way to bypass debt review restrictions.
If you are under debt review, speak to your registered debt counsellor about the options available to you.
What Documents May Be Needed for Debt Consolidation Loan Approval?
Document requirements vary between credit providers and applicants. Depending on your circumstances, you may be asked for:
- South African identification or other accepted identification
- Recent payslips or other proof of income
- Bank statements
- Proof of residential address
- Details of existing debts and repayment commitments
- Settlement balances for the debts you want to consolidate
- Additional financial or verification documents where required
Self-employed applicants may need to provide additional evidence of income, such as business bank statements or financial records.
Preparing accurate, up-to-date information can help avoid unnecessary delays, although it does not guarantee approval.
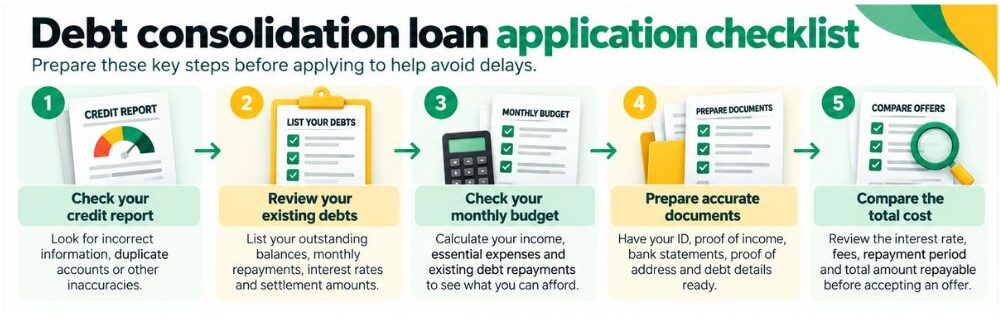
How to Prepare Before Applying for a Debt Consolidation Loan
Check Your Credit Report
Review your credit information for incorrect balances, duplicate accounts or other inaccuracies.
You can obtain credit information through recognised credit bureaus and dispute inaccurate information through the appropriate channels. The National Credit Regulator (NCR) provides information about consumer credit rights.
Correcting inaccurate information may help ensure that credit providers assess a more accurate credit record, but it does not guarantee approval.
Review Your Existing Debts
List your outstanding balances, monthly repayments, interest rates and any settlement amounts.
Compare these commitments with the proposed consolidation loan to understand whether a new agreement would genuinely improve your financial position.
Check Your Monthly Budget
Calculate your income, essential living expenses and existing credit repayments before deciding how much you could reasonably afford.
Prepare Accurate Documents
Provide complete and accurate information requested by the credit provider. Missing or inconsistent details may delay assessment.
Avoid Unnecessary Applications
Consider your eligibility and affordability before submitting multiple credit applications. Applications may involve credit enquiries, and repeated applications do not guarantee a better outcome.
Common Mistakes That Can Affect Debt Consolidation Loan Approval
- Providing incomplete information: Missing or inconsistent details may delay the assessment.
- Applying for an unaffordable amount: The proposed repayments must be considered alongside your existing financial commitments.
- Ignoring the total borrowing cost: A lower monthly instalment may result in higher total costs if the repayment period is extended.
- Not checking settlement amounts: Confirm how much is needed to settle each eligible debt.
- Assuming approval is guaranteed: Every application remains subject to the provider’s eligibility and affordability requirements.
How FatCat Loans Can Help You Explore Debt Consolidation Options
FatCat Loans is a loan comparison platform, not a credit provider. Our website helps South African consumers explore available loan options and understand the information that may be required when applying.
You can learn more about debt consolidation loan options or explore our bad credit loans page if your credit history is a concern.
Comparing options does not guarantee approval or that a consolidation loan will be suitable for your circumstances.
For more information about the process, read our guide to how debt consolidation loans work in South Africa.
What Happens After a Debt Consolidation Loan Is Approved?
If your application is approved and you accept the credit agreement, the next steps depend on the provider and the loan terms.
- Review the agreement: Check the interest rate, fees, repayment period and total amount repayable.
- Settle eligible debts: Confirm whether the provider will settle creditors directly or whether you must arrange settlement.
- Check existing accounts: Verify which debts have been settled and whether any accounts remain open.
- Begin repayments: Follow the agreed repayment schedule and monitor any remaining financial commitments.
Approval does not automatically mean you will save money or improve your credit score. Compare the new agreement with your existing debts before accepting it.
FAQs About Debt Consolidation Loan Approval in South Africa
How long does debt consolidation loan approval take?
Approval times vary between credit providers. The process may depend on document verification, affordability assessments and the provider’s application procedures. Approval is not guaranteed.
Can I qualify for debt consolidation with bad credit?
Possibly. A poor credit history may limit your options, but providers may consider your income, expenses, existing debts and credit information when assessing affordability.
What documents are needed for a debt consolidation loan?
Requirements vary, but providers may request identification, proof of income, bank statements and details of existing debts. Additional documents may be required.
Does a good credit score guarantee approval?
No. Credit providers consider several factors, including affordability and existing financial commitments. A good credit score alone does not guarantee approval.
Can I apply for debt consolidation while under debt review?
Consumers under debt review are generally restricted from taking on additional credit. Speak to your registered debt counsellor about the options available to you.
Conclusion: Preparing for Debt Consolidation Loan Approval
Debt consolidation loan approval in South Africa depends on more than your credit score. Credit providers consider your financial circumstances, existing debts and ability to afford the proposed repayments.
Before applying, review your credit information, gather accurate documents and compare the full cost of a new agreement with your existing debts.
To learn more about the products and requirements involved, explore our debt consolidation loan options page.
Disclosure: This article is for informational purposes only and does not constitute financial advice. FatCat Loans is a loan comparison platform, not a lender. Eligibility, approval, rates and terms depend on the credit provider and your individual circumstances.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.