Bad Credit Consolidation Loans South Africa (2026 Guide)
May 18, 2024
Can You Consolidate Debt With Bad Credit in South Africa?
Last Updated: October 2026
Having a poor credit history can make it harder to qualify for a new loan, especially when you already have several outstanding debts. However, bad credit does not automatically mean every credit provider will decline your application.
A debt consolidation loan may allow you to combine eligible existing debts into one new credit agreement. This can simplify repayments, but approval depends on your financial circumstances, and consolidation does not guarantee a lower interest rate or reduced borrowing costs.
This guide explains how bad credit consolidation loans in South Africa work, what lenders may consider, the costs and risks involved, and what alternatives are available if another loan is unsuitable.
What Are Bad Credit Debt Consolidation Loans?
Debt consolidation involves using a new credit agreement to settle eligible existing debts. Depending on the provider, these may include credit cards, store accounts, personal loans and other qualifying credit agreements.
For borrowers with poor credit histories, qualifying may be more difficult because lenders consider existing repayment commitments, credit information and affordability.
Consolidation does not erase debt or automatically improve your credit score. The new loan must still be repaid according to its agreed terms.
For a broader explanation of available products and requirements, visit our debt consolidation loans in South Africa page.
How Bad Credit Consolidation Loans Work in South Africa
Step 1 – Review Your Debts and Credit Information
Start by listing your existing debts, outstanding balances, monthly repayments, interest rates and settlement amounts.
You can also review your credit information through providers such as TransUnion or Experian. Check for errors and dispute inaccurate information through the appropriate channels.
Step 2 – Compare Available Options
Not every credit provider offers debt consolidation, and eligibility requirements differ. Review the interest rate, fees, repayment period and total cost before deciding whether a new agreement would help.
Borrowers with weaker credit histories can also explore our bad credit loan options page to understand the broader types of credit that may be available.
Step 3 – Apply and Complete Affordability Checks
Credit providers may request identification, income information, bank statements, existing debt details and other supporting documents.
The provider will assess your financial circumstances and affordability before deciding whether to approve the application. Having a regular income does not guarantee approval.
Step 4 – Settle Eligible Debts and Repay the New Loan
If approved, the settlement process depends on the credit provider and agreement. Some arrangements may involve direct settlement with existing creditors, while others require the borrower to settle specified debts.
Confirm which accounts have been settled and whether any remain open. You must then repay the new loan according to its agreed repayment schedule.
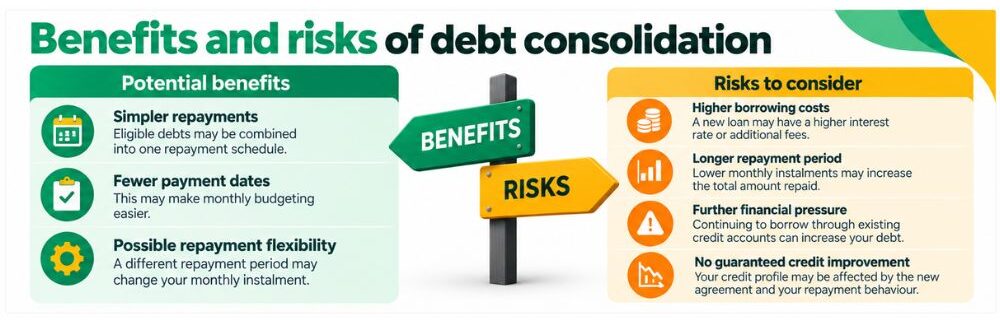
Potential Benefits and Risks of Consolidating Debt With Bad Credit
Debt consolidation may offer benefits, but it also carries risks, particularly when your existing financial commitments are already difficult to manage.
Potential Benefits
- Simpler repayments: Eligible debts may be combined into one new repayment schedule.
- Fewer payment dates: This may make monthly budgeting easier.
- Possible repayment flexibility: A different repayment period may change your monthly instalment.
Risks to Consider
- Higher borrowing costs: A new loan may have a higher interest rate or additional fees.
- Longer repayment period: Lower monthly instalments may increase the total amount repaid.
- Further financial pressure: Borrowing again through existing credit accounts can increase your debt.
- No guaranteed credit improvement: Your credit profile may be affected by the new agreement and your repayment behaviour.
Before consolidating, compare the full cost of the proposed agreement with your existing debts.
Example: Consolidating Debt With a Poor Credit History
Imagine you have three outstanding debts:
- Store account: R5,000
- Credit card: R10,000
- Personal loan: R15,000
Your total outstanding balance is R30,000.
If a credit provider approves a R30,000 consolidation loan and all three debts are eligible for settlement, the new agreement could replace those separate repayment obligations.
However, the monthly repayment and total borrowing cost would depend on the interest rate, fees and repayment period.
Important: If your credit history is poor, the terms offered may be less favourable than you expect. Compare the total repayment amount before accepting the agreement.
This is a hypothetical example for illustration only. It does not represent a specific lender offer or guarantee that these debts can be consolidated.
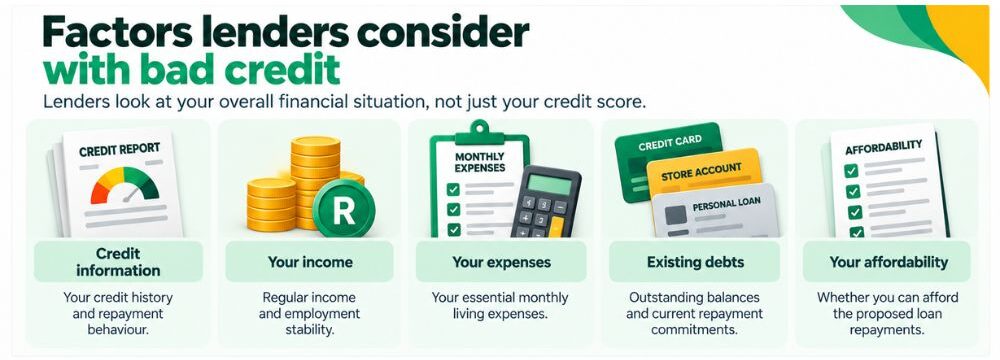
Can You Qualify for Debt Consolidation With Bad Credit?
Possibly. Having a poor credit history does not automatically prevent approval, but it may limit your available options.
Credit providers may assess:
- Your income and regular expenses
- Existing debts and monthly repayment commitments
- Your credit information and repayment history
- The amount you want to borrow
- Your ability to afford the proposed repayments
There is no single credit score that guarantees approval across all South African credit providers. Each provider applies its own eligibility criteria within applicable legal requirements.
Important: Consumers under debt review are generally restricted from taking on further credit. If you are already under debt review, speak to your registered debt counsellor rather than applying for a new consolidation loan.
How to Compare Consolidation Loans for Bad Credit in South Africa
When comparing options, look at more than just the rate.
Interest Rates
Rates for these solutions are usually higher. However, they differ by lender. So, compare several offers before deciding.
Fees
Check if there are any extra costs, such as initiation or service fees. Always read your loan contract carefully.
Loan Term (Repayment Period)
A shorter repayment period may reduce total interest costs but require higher monthly instalments. A longer period may reduce monthly repayments while increasing the overall cost of borrowing.
Compare the total amount repayable, including applicable fees, rather than focusing only on the monthly instalment.
Monthly Instalments
Use the FatCat Loans calculator to estimate what you can afford.
How to Prepare Before Applying for Debt Consolidation With Bad Credit
Although no action guarantees approval, the following steps may help you assess your position before applying:
- Check your credit report for inaccurate information.
- Calculate your current debt repayments and essential monthly expenses.
- Gather accurate income and existing debt information.
- Avoid borrowing more than is needed to settle eligible debts.
- Consider whether the new loan would genuinely improve your financial position.
If your existing repayments are already unaffordable, seeking debt advice may be more appropriate than applying for additional credit.
Common mistakes to avoid with consolidation loans for bad credit
- Taking a longer loan term just to reduce monthly payments
- Not comparing multiple lenders before applying
- Borrowing more than needed during consolidation
- Continuing to use credit after consolidating debt
- Ignoring the total repayment amount
Alternatives to Bad Credit Debt Consolidation Loans
If you cannot qualify for an affordable consolidation loan, consider whether another approach may be more suitable.
- Review your budget: Identify expenses that could be reduced to free up money for existing repayments.
- Speak to your creditors: Ask whether repayment arrangements are available.
- Prioritise higher-cost debt: Consider paying additional amounts towards expensive debts where affordable.
- Seek debt counselling: A registered debt counsellor can assess your circumstances and explain the debt review process where appropriate.
Taking out another loan is not always the best way to manage existing debt.
How to Avoid Scams When Applying for Bad Credit Consolidation Loans South Africa
Borrowers with bad credit are often targeted by unregistered lenders. Therefore, protect yourself by:
- Verifying that the lender is registered with the NCR.
- Be cautious of guaranteed approval claims or demands for suspicious upfront payments before a loan is granted.
- Check the lender’s identity, contact information and registration details. A secure website alone does not prove a lender is legitimate.
- Comparing legitimate offers through FatCat Loans instead of unverified sources.
FAQs About Bad Credit Consolidation Loans in South Africa
Can I get a consolidation loan if I am under debt review?
Consumers under debt review are generally restricted from taking on further credit. Speak to your registered debt counsellor about your options before applying for a new loan.
Can debt consolidation improve my credit score?
Debt consolidation does not guarantee a better credit score. Your credit profile may be affected by the new agreement, existing account settlements and your repayment behaviour over time.
How long does approval take?
Application and approval times vary between credit providers. Additional affordability checks or document verification may be required, and approval is not guaranteed.
Do I need collateral for debt consolidation?
Requirements depend on the provider and the credit product. Some arrangements may be unsecured, while others may require security. Always check the terms before applying.
Conclusion: Is Debt Consolidation an Option With Bad Credit?
Debt consolidation may be an option for some South Africans with poor credit histories, but eligibility depends on the credit provider and your financial circumstances.
Before applying, compare the total cost of the proposed agreement with your existing debts. Consider whether the new repayments are affordable and whether consolidation would genuinely help you manage your obligations.
For more information about available products, explore our debt consolidation loan options page.
Disclosure: This article is for informational purposes only and does not constitute financial advice. FatCat Loans is a loan comparison platform, not a lender. Loan approval, rates and terms depend on the credit provider and your individual circumstances.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.