How to Repay Debt Faster in South Africa: A Practical 2026 Guide
May 16, 2024
How to Repay Debt Faster in South Africa
Last Updated: October 2026
Learning how to repay debt faster in South Africa starts with understanding what you owe, choosing a realistic repayment strategy and making the most of the money available in your budget.
Whether you have credit card balances, personal loans, store accounts or short-term credit, there are practical steps you can take to reduce outstanding debt. These include prioritising expensive debts, avoiding unnecessary borrowing and making additional repayments when affordable.
This guide explains how the debt snowball and avalanche methods work, how to create a repayment plan and what to do if you are struggling to meet your existing obligations.
Not every strategy suits every borrower. If your repayments are already unaffordable, seeking help from creditors or a registered debt counsellor may be more appropriate than taking on another loan.
Why Repaying Debt Faster Can Make a Difference
Repaying outstanding debt sooner may improve your financial position, particularly when you are paying interest on balances that remain unpaid for long periods.
Potential benefits include:
- Lower interest costs: Reducing an interest-bearing balance sooner may decrease the interest charged over the remaining repayment period.
- Fewer ongoing commitments: Settling an account removes its future scheduled repayments, provided no balance or additional charges remain.
- More room in your budget: Money previously used for repayments may become available for essential expenses or savings.
- Improved financial organisation: Following a structured repayment plan can make it easier to monitor your progress.
- Potential credit-history benefits: Consistently meeting your repayment obligations may support a healthier credit history over time, although improvements are not guaranteed.
Even a relatively small additional repayment can make a difference, depending on the interest rate, outstanding balance and terms of the credit agreement.
If you are also working on your credit profile, read our guide to checking and improving your credit score in South Africa.
Understanding Your Debt: The First Step to Repaying Faster
Before you tackle your debt, you need clarity. That means understanding exactly:
- How much you owe
- What interest rates you’re paying
- Which accounts are costing you the most
- How your monthly payments are structured
Different debt types affect your repayment plan differently:
Credit Card Debt
High interest + revolving balance = one of the biggest drains on South African households.
Personal Loans
Fixed repayment terms can make budgeting more predictable. Paying off a personal loan early may reduce interest costs, depending on the loan agreement and applicable charges.
Store Accounts & Buy-Now-Pay-Later
Store accounts and buy-now-pay-later arrangements can have different fee structures, repayment terms and interest charges. Check the full agreement to understand the costs of missing payments or carrying a balance.
Microloans & Short-term Loans
Short-term loans can carry relatively high borrowing costs. Prioritising them may reduce interest expenses, depending on their rates, fees and outstanding balances.
If these multiple debts are causing overwhelm, consider reading our explanation on how debt consolidation loans work in South Africa, which breaks down how to merge accounts into one manageable repayment.
How Interest Rates Affect Debt Repayment
Interest is one of the main reasons outstanding debt can become expensive over time. Generally, the longer an interest-bearing balance remains unpaid, the more interest may accumulate.
For example, a credit card charging a higher interest rate will usually be more expensive to carry than a comparable balance charging a lower rate, assuming similar fees and repayment terms.
Ways to manage interest costs include:
- Paying more than the required minimum when affordable.
- Prioritising higher-interest debts while keeping other repayments up to date.
- Avoiding additional borrowing on revolving credit accounts.
- Asking creditors whether alternative repayment arrangements are available.
- Checking whether additional payments reduce the outstanding principal and how they affect the repayment schedule.
Before making additional repayments, check your credit agreement for applicable terms, fees and any early-settlement provisions.
If you have several outstanding debts, understanding the meaning of debt consolidation may also help you assess whether refinancing is worth considering.
How to Prepare Yourself to Repay Debt Faster
Debt freedom begins with a plan. Here’s how to set yourself up for success:
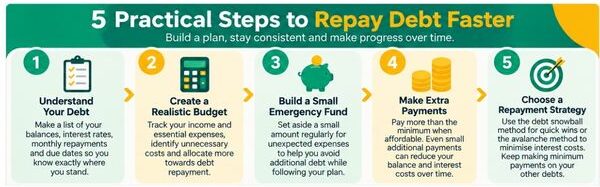
1️⃣ Assess Your Financial Situation
Start with:
- A complete list of debts
- Balances + interest rates
- Monthly instalments
- Income + essential expenses
This alone often provides the clarity people need to take action.
2️⃣ Create a Budget that Supports Faster Repayment
A realistic budget helps you:
- Avoid overspending
- Allocate more toward debt
- Track progress monthly
- Identify unnecessary expenses
Use budgeting tools like 22seven or a simple spreadsheet.
3️⃣ Build a Small Emergency Fund
Having some money set aside for unexpected expenses may help you avoid taking on additional debt while following your repayment plan.
Depending on your budget, even setting aside a small amount regularly can help you build an emergency buffer over time.
However, prioritise essential living expenses and required debt repayments before setting money aside. The amount you can realistically save will depend on your financial circumstances.
Debt Repayment Strategies: Snowball vs Avalanche
Two commonly used approaches to repaying multiple debts are the debt snowball and debt avalanche methods.
With either method, the starting point is to keep up with the required repayments on your other accounts. Any affordable extra amount is then directed towards the debt you have chosen to prioritise.
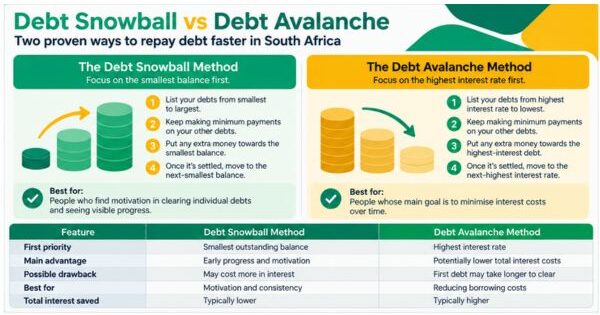
The Debt Snowball Method
The debt snowball method focuses on repaying your smallest outstanding balance first, regardless of its interest rate.
- List your debts from the smallest balance to the largest.
- Continue making the required repayments on your other debts.
- Put any additional repayment money towards the smallest debt.
- Once that debt is settled, redirect the amount you were paying towards the next-smallest balance.
Example: If you owe R2,000 on a store account, R8,000 on a credit card and R20,000 on a personal loan, you would focus your extra repayments on the R2,000 balance first.
Best suited to: People who find motivation in clearing individual debts and seeing visible progress.
The Debt Avalanche Method
The debt avalanche method prioritises the debt with the highest interest rate rather than the smallest balance.
- List your debts from the highest interest rate to the lowest.
- Keep making the required repayments on your other accounts.
- Direct any affordable extra repayments towards the highest-interest debt.
- Once it is settled, move to the debt with the next-highest interest rate.
Example: If your credit card charges 24% interest, your store account charges 20% and your personal loan charges 15%, you would prioritise extra repayments towards the credit card first.
Best suited to: People whose main goal is to minimise interest costs over time.
Which Debt Repayment Method Is Better?
| Feature | Snowball Method | Avalanche Method |
|---|---|---|
| First priority | Smallest outstanding balance | Highest interest rate |
| Main advantage | Early progress and motivation | Potentially lower total interest costs |
| Possible drawback | May cost more in interest | First debt may take longer to clear |
| Best for | Motivation and consistency | Reducing borrowing costs |
Neither method guarantees a particular repayment timeline. Your results depend on your balances, interest rates, fees and how much you can afford to repay.
When Might Debt Consolidation Help?
If you have several existing debts, a consolidation loan may allow you to combine eligible balances into one repayment arrangement.
However, consolidation does not automatically reduce the amount you owe or help you become debt-free sooner. A longer repayment term may reduce your monthly instalment while increasing the total cost of borrowing.
Before refinancing, compare the new loan’s interest rate, fees, repayment period and total repayment amount against your existing debts.
You can explore debt consolidation loan options in South Africa through FatCat Loans, a loan comparison and matching service rather than a lender.
Common Mistakes That Slow Down Debt Repayment
Avoid these traps if you want to make real progress:
❌ Only paying the minimum instalment
Interest keeps growing.
❌ Opening new credit accounts
This creates a cycle that’s hard to break.
❌ Ignoring high-interest debts
They grow the fastest.
❌ Not budgeting
You can’t fix what you can’t see.
❌ Paying late
This adds fees and harms your credit score.
Conclusion: Start With a Realistic Debt Repayment Plan
Repaying debt faster starts with understanding your balances, choosing a manageable strategy and keeping up with your existing repayment obligations.
The snowball and avalanche methods offer different ways to prioritise debts, while budgeting and affordable additional repayments can help you make progress over time.
If you cannot afford your current repayments, contact your creditors or seek guidance from an NCR-registered debt counsellor before considering further borrowing.
If refinancing is appropriate for your circumstances, FatCat Loans can help you explore available loan options. Approval and loan terms remain subject to the lender’s assessment.
Frequently Asked Questions About Repaying Debt Faster
What is the fastest way to pay off debt in South Africa?
There is no single fastest method for everyone. Prioritising higher-interest debts while maintaining other required repayments can help reduce interest costs. The best approach depends on your outstanding balances, interest rates, fees and available budget.
Which is better: the snowball or avalanche method?
The snowball method focuses on clearing smaller balances first and may help with motivation. The avalanche method targets higher-interest debts first and will generally minimise interest costs when other factors are equal.
Can making extra repayments reduce loan interest?
Potentially. Additional repayments may reduce your outstanding principal and future interest charges, depending on the loan agreement and how the lender applies payments. Check the applicable terms before making extra payments.
What should I do if I cannot afford my monthly debt repayments?
Contact your creditors as soon as possible to discuss available arrangements. If you are over-indebted, consider speaking to an NCR-registered debt counsellor. Taking out another loan may not be appropriate if your existing repayments are already unaffordable.
How long does it take to become debt-free?
There is no standard timeframe. The time needed depends on how much you owe, your interest rates, repayment obligations and how much you can realistically afford to pay each month.
Disclosure: This article is for general informational purposes and does not constitute personalised financial advice. FatCat Loans is a loan comparison and matching service, not a lender. Loan eligibility, approval, rates and terms are determined by the lender. Always review the full cost and conditions of any credit agreement before accepting an offer.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.