Fasta Loans: What South Africans Should Know Before Applying
December 30, 2025
FASTA Loans in South Africa: How They Work
Last Updated: September 2026
Fasta is a South African credit provider offering short- to medium-term personal loan solutions.
Many South Africans come across this lender when searching for accessible credit options that may offer faster decisions than traditional banks.
Searches for Fasta loans, Fasta personal loans, and Fasta credit options are common among borrowers comparing lenders.
Before applying, it’s important to understand how these loans work, who they suit, and how they compare with other options on the market.
You can also explore other providers in the FatCat Loans lender network before choosing a loan.
Applying without comparing alternatives can lead to repayment commitments that don’t match your affordability or long-term goals.
FASTA loans at a glance (quick summary)
This quick summary helps you decide if FASTA is worth considering before reading the full guide.
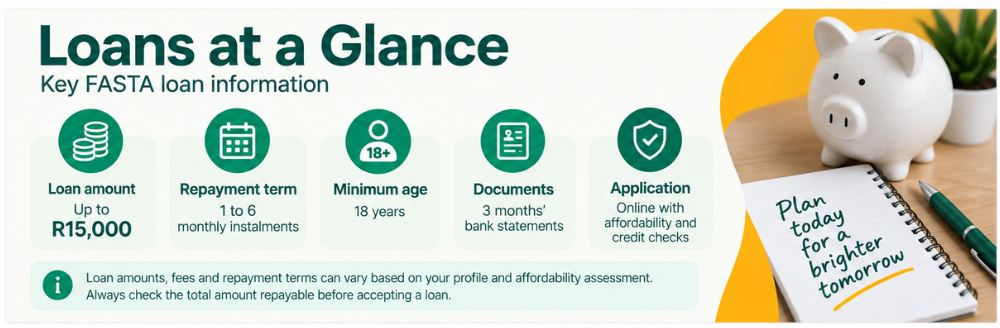
- Typical loan size: Up to R15,000
- Repayment term: 1 to 6 monthly instalments
- Best for: short-term cash-flow gaps and urgent small expenses (not long-term borrowing)
- Key watch-outs: fees add up quickly on short terms—always check the total repayable before accepting
FASTA offers short-term loans in South Africa of up to R15,000, repayable over 1 to 6 monthly instalments.
Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.
Understanding Fasta as a Lender
Fasta operates as a non-bank personal loan provider in South Africa.
FASTA operates differently from a traditional bank, with an online application process focused on short-term credit.
Some borrowers may consider FASTA alongside traditional banks and other non-bank credit providers when comparing short-term loan options.
How to verify FASTA (or any lender) is registered with the NCR
In South Africa, legitimate credit providers are typically registered with the National Credit Regulator (NCR).
You can verify a lender by searching the NCR’s Register of Registrants and checking the provider name or registration number.
FASTA is a registered South African credit provider under NCRCP10591. You can independently verify a credit provider using the National Credit Regulator’s Register of Registrants.
Why this matters: If a lender cannot be found on the NCR register, treat it as a red flag—especially if they request upfront payments before you have signed a credit agreement.
Fasta is often compared with other non-bank and alternative lenders such as MPowa loan options, Lime loan options, and Blink Finance loans.
FASTA Contact Details
If you need to contact FASTA about an application, existing loan, repayment or account query, FASTA primarily directs customers to its online Customer Support Portal.
| Customer support | Use the Support portal at www.fasta.co.za |
| Support email | [email protected] |
| General email | [email protected] |
| Collections email | [email protected] |
| Customer service hours | Monday–Friday: 08:00–17:00 Saturday: 08:00–12:00 Sunday & public holidays: Closed |
| Physical address | 33 Bree Street, Cape Town, 8001 |
| NCR registration | NCRCP10591 |
FASTA states that customers can submit a support ticket by selecting Support on its website. Logged-in customers can also access the Customer Support Portal through their FASTA profile.
Repayment problems: If you think you may miss a payment, FASTA advises contacting its Collections team at [email protected].
Contact details checked against FASTA’s official website in September 2026. FASTA may change its contact channels, so confirm the latest details on the official website.
Types of Loans Commonly Associated With Fasta
Searches for Fasta loans generally relate to:
- Personal instalment loans
- Short- to medium-term credit solutions
- Fixed-repayment loan agreements
These loans are commonly used for:
Managing unexpected expenses
- Covering short-term financial needs
- Supporting household or personal cash-flow requirements
- Bridging gaps between income cycles
Fasta loans are typically structured with fixed monthly repayments, allowing borrowers to understand their repayment obligations upfront.
This predictability can be useful for budgeting, particularly for borrowers who want clarity around their monthly financial commitments.
A FASTA-style loan is usually best for a small, urgent expense or a short cash-flow gap—not for long-term borrowing
Who Typically Considers Fasta Loan Options?
Fasta loan options are commonly explored by:
- Borrowers seeking alternatives to traditional bank loans
- Consumers comparing non-bank lenders
- Individuals looking for structured instalment repayments
- Borrowers researching multiple lenders before applying
Many users researching Fasta are also comparing:
- Fasta vs other lenders
- Fasta loan alternatives
- Options from banks such as African Bank loan options or ABSA loan options
This behaviour highlights that Fasta is rarely considered in isolation and is usually part of a wider loan comparison process.
Eligibility and Approval Considerations
Fasta applies affordability and credit assessments before approving loan applications. These assessments typically take into account:
- Income stability and consistency
- Existing financial commitments
- Credit history and repayment behaviour
As a non-bank lender, Fasta may assess applications differently from traditional banks. This can result in approval outcomes that vary depending on an applicant’s financial profile.
Borrowers with stable income and manageable debt are more likely to qualify for better repayment terms.
Tip: Always compare the total repayable amount — not just the monthly instalment.
Costs, fees, and what “cheap” really means on a short-term loan
With short-term credit, the rate is only part of the story. The total cost typically includes:
- Interest (often quoted monthly for short-term credit)
- Once-off initiation fee (charged when a new credit agreement is set up)
- Monthly service fee (admin/maintenance fee on the agreement)
- Optional or required add-ons (for example, credit protection/insurance if included in the offer).
Representative example (why you must check the total repayable)
A representative example shown by FASTA includes a combination of interest + initiation fee + monthly service fee + credit protection, and also references a maximum APR. Always compare:
- the total amount repayable, and
- what happens if you miss a payment (extra fees/interest).
Quick affordability checklist
Before accepting any offer, sanity-check:
- Can you repay on your next pay cycle without needing another loan?
- If income drops, do you still have a fallback plan?
- Are you borrowing for a need (essentials/emergency) rather than a want?
If any answer is “no”, it’s safer to compare longer-term personal loans instead of rolling short-term debt.
What fees can be included in a FASTA-style short-term loan?
Short-term credit commonly includes interest, a once-off initiation fee, and a monthly service fee, and may include additional cover/insurance depending on the offer.
Advantages Often Associated With Fasta Loans
Borrowers often consider Fasta because of:
- Access to non-bank credit solutions
- Fixed monthly repayments that support budgeting
- Structured instalment-based loan agreements
- Simpler application processes compared to banks
These features may appeal to borrowers who want predictable repayments and a straightforward alternative to traditional bank lending.
Important Limitations to Consider
Fasta may not be suitable for everyone. Some limitations to consider include:
- Repayment terms that may not suit long-term borrowing
- Interest rates that may differ from traditional bank loans
- Approval criteria that still require affordability checks
Because of these factors, Fasta loans should always be reviewed alongside other available lenders before making a final decision.
You can verify a lender by searching the NCR’s Register of Registrants for the provider name or registration number.
What to do if you’re struggling to repay
Short-term loans become expensive when you miss a payment or need to refinance repeatedly. If you think you’ll struggle:
- Contact the credit provider immediately to discuss arrangements before you default.
- Prioritise essentials (housing, transport to work, food) over non-essential repayments.
- Avoid “loan stacking” (taking a second loan to pay the first). This is where many borrowers get trapped.
If your current repayments feel unmanageable, comparing alternative lenders may help you find a more affordable option.
Comparing Fasta With Other Lenders
When comparing Fasta with lenders such as Finchoice loan options, Sanlam loan options, or RCS credit options, borrowers should consider:
- Repayment structure and loan duration
- Monthly affordability
- Differences in approval criteria
- Flexibility versus predictability
Some lenders may offer longer repayment periods, while others focus on shorter-term credit. Comparing these differences helps ensure you select a loan that aligns with your financial needs and repayment capacity.
When Fasta May Be a Good Fit
Fasta may suit borrowers who:
- Are exploring non-bank loan options
- Have stable income and manageable debt
- Prefer structured instalment repayments
- Want predictable monthly commitments
- Are actively comparing multiple lenders
In these scenarios, Fasta can form part of a broader loan comparison strategy rather than a standalone decision.
If you fall into one of these categories, it’s worth checking what lenders will actually offer you based on your profile.
When Fasta May Not Be the Right Option
Fasta may be less suitable if you:
- Are seeking long-term repayment flexibility
- Prefer traditional bank lending products
- Are managing complex or high-value financial commitments
- Require highly flexible credit structures
In such cases, other lenders may offer solutions better aligned with your financial needs.
Alternatives if Fasta Is Not the Right Fit
If Fasta does not meet your requirements, alternatives may include:
- Traditional banks offering personal loans
- Other non-bank instalment lenders
- Digital lenders with different approval models
Exploring alternatives ensures you are not limited to a single lender’s criteria or lending structure.
FASTA vs other options (quick comparison)
| Option | Typically best for | Typical trade-off |
|---|---|---|
| Short-term loans (FASTA-style) | Small urgent gaps | Higher cost density over short term (fees matter) |
| Personal loans (longer term) | Bigger needs, lower monthly strain | Slower approval / stricter checks |
| Compare multiple lenders (recommended first step) | Avoiding mismatches & rejections | Takes a few extra minutes, saves cost/risk |
How FatCat Loans Helps You Compare Fasta With Other Options
Borrowers who want to compare Fasta with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.
FatCat Loans helps South Africans compare loan options from multiple lenders, including non-bank providers like Fasta and traditional financial institutions. By using a comparison platform, you can:
- Compare repayment structures and affordability
- Review multiple lenders in one place
- Identify alternatives without submitting multiple applications
This comparison-first approach supports informed and responsible borrowing decisions.
Frequently Asked Questions About Fasta Loans
How much can I borrow with FASTA loans?
FASTA currently offers cash loans of up to R15,000. The amount you can borrow depends on your application, affordability assessment and credit checks. Approval for the maximum amount is not guaranteed.
How long do I have to repay a FASTA loan?
FASTA loans can currently be repaid over 1 to 6 monthly instalments. Your repayment term, instalment amount and total amount repayable will be shown before you accept the loan.
What are the FASTA contact details?
FASTA’s Customer Services Team can be contacted through the Customer Support Portal at FASTA’s official website. Select Support to submit a query.
Customer service hours are Monday to Friday, 08:00–17:00, and Saturday, 08:00–12:00. The service is closed on Sundays and public holidays. Customers who are struggling with a repayment can email [email protected].
Is FASTA a registered lender in South Africa?
Yes. FASTA (Pty) Ltd states that it is a registered credit provider with the National Credit Regulator under NCRCP10591. You can independently verify a credit provider using the NCR’s Register of Registrants.
What do I need to apply for a FASTA loan?
FASTA’s current application information states that applicants need to be 18 or older, have a valid South African ID number and provide three months’ bank statements. You’ll also need your mobile number and online banking details during the application process. Applications remain subject to affordability and credit checks.
How quickly does FASTA pay out a loan?
FASTA currently advertises automated applications and says approved FASTACash funds can be paid directly into your bank account. Its FAQ says applications generally take around 2–3 minutes, although actual timing can vary depending on the application and banking process.
What fees does FASTA charge?
Your loan cost can include interest, a once-off initiation fee, a monthly service fee and credit protection insurance. The exact cost depends on the loan product and offer, so check the total amount repayable before accepting the agreement.
Can I get a FASTA loan with bad credit?
FASTA does not guarantee approval based simply on having a particular credit score. Applications are subject to affordability and credit checks, so your individual financial circumstances will affect the outcome.
Final Thoughts
Fasta provides access to structured personal loan solutions for South Africans exploring non-bank lending options.
However, accessibility alone should not determine your choice of lender.
By comparing Fasta with other lenders, you gain a clearer understanding of repayment obligations, approval criteria, and alternative solutions that may better suit your financial needs.
The key step is simple: compare before you apply.
With one quick check, you can see which lenders are most likely to approve you — and what your repayments could look like.
Sources & Verification
We checked the information in this FASTA loans review against current lender information and South African consumer-credit sources. Key sources include:
- FASTA Official Website – current loan amounts, repayment terms, application requirements and representative loan information.
- FASTA FAQs – customer support details, repayment information, credit protection insurance and other borrower information.
- FASTA Short-Term Loans – current product information, repayment terms, fees and representative example.
- National Credit Regulator – Register of Registrants – used to independently check South African credit-provider registration information.
- National Credit Regulator – guidance on regulated credit and consumer protections under South Africa’s National Credit Act.
Product information and contact details were checked in September 2026. Loan amounts, interest rates, fees, eligibility requirements and other terms can change. Always check your individual quotation and the lender’s official website before accepting a credit agreement.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.