Hippo Loans South Africa Review 2026: How It Works & What to Know
September 08, 2026
Hippo Loans Review: What You Need to Know
Last Updated: September 2026
If you’re searching for Hippo loans in South Africa, there’s an important point to understand before you apply: Hippo.co.za does not provide personal loans itself.
Instead, Hippo is a comparison platform that lets South Africans compare personal loan options from a panel of participating providers. You enter some basic information about yourself and the loan you’re looking for, and Hippo helps you see available options from its partners.
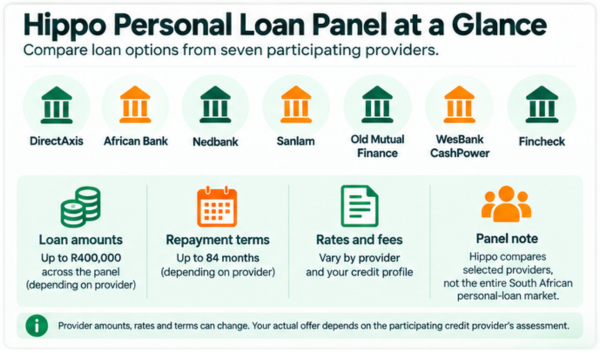
Hippo currently advertises comparisons from 7 personal loan providers, with individual partners offering loans ranging from a few thousand rand to as much as R400,000, depending on the provider, your affordability and credit assessment.
This Hippo Loans review looks at how the service works, which providers it compares, current rates and repayment terms, its loan calculator and the advantages and limitations of using a comparison platform.
Important: FatCat Loans is a loan comparison service and not a lender. Hippo.co.za is a separate comparison platform and is not affiliated with FatCat Loans. Loan approval, rates and terms depend on the credit provider and your individual circumstances.
Hippo Loans at a Glance
| Feature | Hippo Personal Loans |
|---|---|
| Is Hippo a lender? | No |
| What does Hippo do? | Compares personal loan options |
| Number of providers currently advertised | 7 |
| Maximum available across current panel | Up to R400,000 |
| Repayment terms across current panel | Up to 84 months |
| Does Hippo set the interest rate? | No |
| Does Hippo charge consumers to compare? | No |
| Does comparing affect your credit score? | Hippo says comparing through its platform does not |
| Application method | Online |
| Company | Hippo Comparative Services (Pty) Ltd |
| FSP | 16357 |
Provider amounts, rates and terms were checked in September 2026 and can change. Your actual offer depends on the participating credit provider’s assessment.
What Is Hippo.co.za?
Hippo.co.za is a South African comparison website that allows consumers to compare products from different providers rather than approaching each company individually.
It launched in 2007 and compares products across several categories, including insurance, medical aid, personal loans, debt consolidation and other financial products. Hippo Comparative Services (Pty) Ltd is an authorised financial services provider, FSP 16357.
For personal loans, Hippo acts as the comparison platform between you and participating loan providers.
That distinction matters.
If you ultimately take out a loan after using Hippo, your credit agreement is with the lender that approves and provides the loan — not with Hippo.
So what is a “Hippo loan”?
There isn’t technically a separate loan product called a Hippo loan.
When people refer to “Hippo loans”, they are generally referring to personal loans found by using Hippo’s comparison service.
Think of it this way:
You → Hippo comparison service → participating provider → potential loan offer
Hippo helps with the comparison. The participating credit provider is responsible for the actual credit product, assessment, approval and loan agreement.
Which Loan Providers Does Hippo Compare?
As of September 2026, Hippo advertises personal loan comparisons involving these seven providers:
- DirectAxis
- African Bank
- Nedbank
- Sanlam
- Old Mutual Finance
- WesBank CashPower
- Fincheck
Hippo says it is continually looking to add brands to its panel.
This is an important consideration when using any comparison service.
Comparing loans through Hippo does not mean you are comparing every personal loan available in South Africa.
You’re comparing options available through its participating panel.
That doesn’t make the comparison less useful, but borrowers should understand the distinction between “compare participating providers” and “compare the entire market.”
Hippo Personal Loan Amounts, Rates and Terms
There isn’t one standard Hippo loan amount, interest rate or repayment term because Hippo doesn’t issue the loan.
Instead, these depend on the provider.
Hippo currently publishes the following information for several of its personal loan partners:
| Provider | Loan Amount | Advertised Interest Rate | Term |
|---|---|---|---|
| DirectAxis | Up to R350,000 | Up to 28% | 24–72 months |
| African Bank | R2,000–R350,000 | 15%–24.5% | 7–72 months |
| Nedbank | R2,000–R400,000 | 10.25%–27.75% | 6–84 months |
| Sanlam | R5,000–R350,000 | 16%–27.75% | 12–84 months |
| Old Mutual Finance | R2,000–R250,000 | Up to 28% | 3–72 months |
| WesBank CashPower | R5,000–R350,000 | From 18% | 24–72 months |
Source: Hippo.co.za personal loans comparison information, September 2026. Rates and product terms can change.
These figures show why it’s misleading to talk about a single “Hippo loan interest rate.”
Your rate comes from the provider, not Hippo.
The amount and terms you’re actually offered may also depend on factors such as your income, existing financial commitments, credit profile and affordability assessment.
Can You Borrow R400,000 Through Hippo?
Potentially, but R400,000 isn’t a standard Hippo loan limit.
Hippo currently advertises personal loans of up to R400,000 across its comparison service because Nedbank is listed with loans ranging from R2,000 to R400,000.
Other providers have different maximums.
For example, Hippo currently lists DirectAxis, African Bank, Sanlam and WesBank CashPower with maximum loan amounts of R350,000, while Old Mutual Finance is listed at up to R250,000.
Even where a provider advertises a high maximum, that doesn’t mean every applicant will qualify for it.
The lender still needs to determine what you can realistically afford.
If you’re trying to estimate your borrowing capacity before applying, see our guide to how much you can borrow in South Africa.
How Does the Hippo Loan Application Work?
Hippo aims to simplify comparison by allowing you to start with one online process rather than independently researching each participating provider.
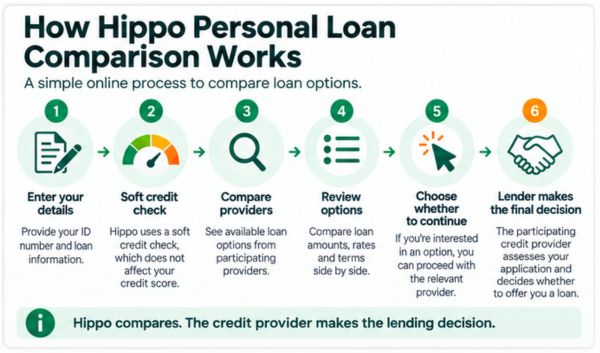
Hippo currently describes its process as follows:
1. Start your comparison
Go to Hippo’s personal loans comparison tool and begin the quote process.
2. Provide your ID details
You’ll be asked to provide your South African ID number.
Hippo states that your ID number is shared with a registered credit provider to help generate more accurate loan options.
3. Enter the loan details
You’ll provide information about the amount you’re considering and other information required during the comparison process.
4. Compare available options
If options are available, you can compare participating providers rather than having to visit every provider individually.
5. Choose whether to continue
If you’re interested in an option, the relevant provider can take the application further.
6. The lender makes the lending decision
This is the crucial part.
Hippo doesn’t decide whether your loan is approved.
The relevant credit provider conducts the required checks and determines whether it can offer you credit, how much it is prepared to lend and the rate and terms that apply.
Does Comparing Loans on Hippo Affect Your Credit Score?
Hippo states that comparing personal loans through Hippo.co.za uses a soft credit check, which does not affect your credit score.
However, it’s important to distinguish the comparison stage from subsequently proceeding with a credit application.
Once you decide to proceed with a particular lender, that provider may perform the credit and affordability checks required to assess the application.
If you’re concerned about enquiries appearing on your credit profile, our guide to soft vs hard credit checks in South Africa explains the difference and what to look for before submitting a credit application.
What Credit Score Do You Need for a Hippo Loan?
Hippo doesn’t publish one minimum credit score that guarantees access to personal loans across its entire panel.
That makes sense because Hippo isn’t the lender.
Each participating credit provider has its own credit criteria and assessment process.
Your credit profile may influence:
- whether a provider is prepared to lend to you
- the amount you’re offered
- your interest rate
- your repayment terms
A stronger credit profile doesn’t guarantee approval, and a weaker score doesn’t automatically tell you what every provider will decide.
Lenders also need to consider affordability and other application information.
If you’re unsure how lenders interpret your credit history, read our guide to what’s a good credit score in South Africa.
Who Can Apply for a Personal Loan Through Hippo?
Hippo now publishes some fairly specific typical requirements. Its current FAQ says applicants will generally need to:
- be a South African citizen or permanent resident
- be aged 18–60
- be permanently employed or earn verifiable income at least equal to minimum wage
- have no active debt review or administration order
- meet the eventual lender’s credit/risk assessment.
Can You Get a Hippo Loan With Bad Credit?
There is no guaranteed Hippo bad credit loan.
Using a comparison service doesn’t bypass the lending criteria of the providers on the panel.
A participating provider still needs to decide whether it’s willing to lend based on its own criteria and the required credit and affordability assessment.
Be particularly careful with websites promising:
- guaranteed approval
- loans for everyone
- no affordability checks
- guaranteed loans despite serious credit problems
- payment of an upfront fee before receiving a loan
Legitimate credit shouldn’t be presented as guaranteed regardless of your circumstances.
If your application has previously been unsuccessful, repeatedly submitting new applications isn’t necessarily the best response. You can first check your credit report, existing debt commitments and affordability to identify possible reasons for the decline.
Hippo Personal Loan Calculator: How Does It Work?
Hippo provides a personal loan calculator that currently allows you to estimate repayments on loan amounts up to R350,000 and select a repayment period of up to six years. This is slightly different from Hippo’s wider comparison panel, where some participating providers advertise loans of up to R400,000.
There is an important catch:
The calculator doesn’t show the personalised rate you’ll actually receive from a lender.
As of September 2026, Hippo states that its calculator uses an illustrative 28.25% interest rate and a R69 monthly service fee when estimating repayments.
Hippo explicitly describes the calculator as being for illustration purposes only, with actual quotes subject to credit approval and the individual’s risk profile.
Why does this matter?
Suppose the calculator estimates a certain monthly repayment.
That figure shouldn’t be treated as an offer.
Your eventual lender could offer a different:
- interest rate
- loan amount
- repayment term
- monthly instalment
- total cost of credit
The calculator is therefore best used for rough planning, rather than predicting exactly what a Hippo partner will offer you.
Does Hippo Charge a Fee for Comparing Loans?
Hippo says its comparison service is free to use and commission free for consumers.
So how does the business make money?
According to Hippo’s terms, it charges participating partners a fee when a consumer chooses to find out more about their products. Hippo states that this fee doesn’t influence the price paid by the consumer.
This business model is worth understanding because Hippo is a commercial comparison service, rather than an independent database of every loan available in South Africa.
FatCat Loans also operates as a loan comparison service rather than a lender.
Are Hippo Loan Quotes Guaranteed?
No.
Hippo’s terms explain that quotes presented through its platform are based on limited information supplied through the online quote process and are illustrative rather than binding offers.
The information can change after a provider verifies your details and considers additional risk information.
That means seeing an attractive option during the comparison stage doesn’t guarantee that you’ll ultimately receive:
- that loan amount
- that interest rate
- that repayment
- those exact terms
- approval
Always review the lender’s final pre-agreement statement and quotation before accepting credit.
What Documents Could You Need?
Because Hippo works with different providers, there isn’t one universal Hippo document list that applies to every eventual loan application.
The lender may require information or documents such as:
- South African identification
- proof of income
- recent bank statements
- proof of residential address
- bank account details
Exact requirements depend on the provider and your circumstances.
You may initially provide less information while comparing, with additional verification required if you decide to proceed.
Why Do Lenders Perform an Affordability Assessment?
South African credit providers can’t simply look at the amount you want and decide whether they’re happy to lend it.
Credit providers have obligations under the National Credit Act and applicable affordability assessment requirements when assessing consumer credit.
This is why an advertised maximum such as R350,000 or R400,000 shouldn’t be interpreted as an amount that everyone can borrow.
Your income might look sufficient at first glance, but lenders may also need to consider your existing financial obligations and ability to meet the proposed repayments.
That’s why two people requesting the same amount through Hippo could receive very different results.
Hippo vs Applying Directly to a Lender
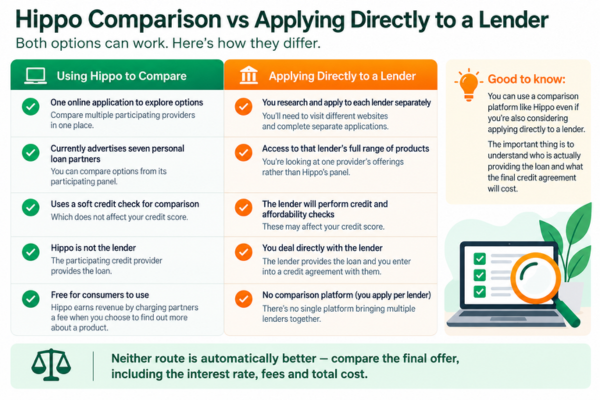
One of the main decisions is whether to use a comparison platform or approach a particular lender directly.
Using Hippo
The main advantage is convenience.
Instead of starting at several different lender websites, you can use one platform to explore options from participating providers.
That can be particularly useful if you don’t already know which lender you want.
The limitation is that Hippo has a panel. It isn’t necessarily showing every loan provider or every loan product available in South Africa.
Applying directly
Going directly to a bank or lender can make sense if you’ve already researched the product and know which provider you want.
You’ll be dealing with that company from the beginning.
The downside is that you may need to research several lenders separately if you want to compare your options.
Neither route is automatically better for every borrower.
The important thing is to understand who is actually providing the loan and what the final credit agreement will cost.
Hippo vs FatCat Loans
Hippo and FatCat Loans have an important similarity: neither is the lender providing the personal loan.
Both help South Africans explore loan options through online comparison services.
There are, however, differences in how the two brands are positioned.
| Hippo | FatCat Loans |
|---|---|
| Broad financial-product comparison platform | Loan-focused comparison service |
| Compares insurance, health, loans and other products | Focused primarily on borrowing |
| Currently advertises 7 personal loan partners | Uses its own participating lending network |
| Shows several named loan partners on its comparison page | Matches loan requests with available options from participating providers |
| Not the lender | Not the lender |
There is no reason you have to use only one comparison service when researching borrowing options.
What’s more important is that you understand which lender is ultimately making the offer and compare the actual rate, fees, repayment period, monthly instalment and total cost before accepting it.
Advantages of Using Hippo for Personal Loans
Compare several providers
Hippo’s biggest attraction is the ability to explore participating lenders through one platform.
Free for consumers to use
Hippo states that consumers aren’t charged for using its comparison service.
Established South African comparison brand
Hippo says it launched in 2007 and has been operating in the South African comparison market for many years.
Current provider information is relatively transparent
Hippo publishes useful information about participating lenders, including indicative loan amounts, rates and repayment terms.
Comparison itself shouldn’t affect your credit score
Hippo states that comparing personal loans through its platform won’t impact your credit score.
Useful calculator
The calculator can provide a rough indication of how borrowing amount and term can affect repayments, provided you remember that it isn’t a personalised quote.
Potential Drawbacks of Using Hippo
It doesn’t compare every lender
Hippo compares its participating partners rather than every credit provider in South Africa.
This is probably the most important limitation to understand.
Hippo doesn’t control the final offer
Approval, rates, terms and loan amounts ultimately come from the credit provider.
Calculator results are illustrative
The calculator’s assumed rate shouldn’t be mistaken for the interest rate you’ll actually receive.
Your information may be passed to a provider
The comparison process is designed to connect interested consumers with participating providers. Read the relevant privacy and consent information so you understand how your details may be used and who may contact you.
Comparing doesn’t guarantee approval
Receiving comparison results or using the calculator doesn’t mean a lender is required to approve your application.
Is Hippo Legit?
Hippo is an established South African comparison business rather than an anonymous loan website.
Hippo.co.za says it launched in 2007. The website is operated by Hippo Comparative Services (Pty) Ltd, company registration number 1979/007029/07, and the company states that it is an authorised financial services provider with FSP number 16357.
Hippo states that the personal-loan providers on its panel are registered credit providers and financial services providers.
That doesn’t mean every loan displayed will be suitable or affordable for every borrower.
You should still verify the identity of the lender making an offer and carefully review the final credit agreement.
Is Hippo a Registered Credit Provider?
This is where terminology matters.
Hippo’s role is to provide the comparison platform, not to extend the personal loan itself.
Hippo Comparative Services states that it is an authorised financial services provider (FSP 16357). The credit itself is provided by the participating lender whose offer you ultimately accept.
You should therefore check the credentials and National Credit Regulator registration of the actual credit provider when considering a loan.
Hippo Loans vs DirectAxis
DirectAxis is currently one of the personal loan providers available through Hippo.
The difference is straightforward:
Hippo helps consumers compare participating providers.
DirectAxis provides personal loans directly.
Hippo currently lists DirectAxis loans of up to R350,000, with repayment periods of 24 to 72 months and rates of up to 28%.
If you’re considering this option, read our full DirectAxis Loans review for a closer look at the lender itself.
Hippo Loans vs WesBank CashPower
WesBank CashPower is another provider currently included on Hippo’s personal-loan panel.
Hippo currently lists CashPower personal loans from R5,000 to R350,000, with terms of 24 to 72 months and advertised rates starting from 18% p.a.
CashPower is a WesBank personal-loan product and is administered and managed by DirectAxis, a business unit of FirstRand Bank.
We’ve covered the product separately in our WesBank CashPower Personal Loan Review, including its current rates, requirements, fees and application process.
Who Might Hippo Loans Suit?
Using Hippo may be worth considering if you:
- want to explore more than one personal loan provider
- don’t already have a specific lender in mind
- want an initial comparison in one place
- understand that the results are limited to participating providers
- are prepared to compare the final loan costs carefully before accepting an offer
It may be less useful if you’ve already decided on a particular lender or want to research providers outside Hippo’s current panel.
And if you’re struggling to meet existing debt repayments, taking another personal loan isn’t automatically the right solution.
Borrowing should solve a genuine financial need without creating repayments that your budget can’t sustain.
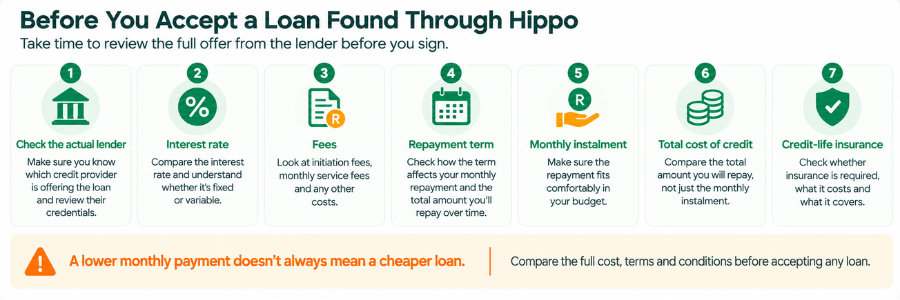
What Should You Compare Before Accepting a Loan?
Don’t choose a loan simply because it offers the highest amount or lowest monthly repayment.
Look at the complete agreement.
Pay particular attention to:
Interest rate: A lower rate can substantially affect the cost of a longer-term loan.
Repayment period: Extending the term can reduce the monthly repayment while increasing the amount you repay over time.
Initiation fee: Check the once-off fee included in the agreement.
Monthly service fee: Small monthly fees add up over a multi-year loan.
Credit-life insurance: Check whether insurance applies, what it costs and what it covers.
Monthly instalment: Make sure the repayment comfortably fits your budget.
Total cost of credit: This is one of the most useful figures when comparing offers because it shows the bigger picture rather than just the monthly repayment.
A R2,500 monthly repayment isn’t necessarily a better deal than R3,000 per month if you’re making the smaller payment for considerably longer.
Frequently Asked Questions About Hippo Loans
Is Hippo a lender?
No. Hippo.co.za is a comparison platform. If you proceed with a personal loan found through Hippo, the loan itself is provided by the participating credit provider.
How much can I borrow through Hippo?
Hippo currently compares providers offering personal loans of up to R400,000, although maximum amounts differ between providers. The amount you personally qualify for depends on the lender’s credit and affordability assessment.
Which banks and lenders does Hippo compare?
As of September 2026, Hippo advertises seven personal-loan partners: DirectAxis, African Bank, Nedbank, Sanlam, Old Mutual Finance, WesBank CashPower and Fincheck. The panel can change.
Does Hippo charge for comparing personal loans?
Hippo says its service is free for consumers to use. It earns revenue by charging partners a fee when a consumer chooses to find out more about a product.
Does using Hippo affect my credit score?
Hippo states that comparing personal loans through Hippo.co.za uses a soft credit check, which does not affect your credit score. A provider may perform the necessary credit checks if you proceed with an application.
Are Hippo loan calculator results guaranteed?
No. Hippo says its personal-loan calculator is illustrative only. Actual rates, repayments and offers depend on the provider, credit approval and your individual risk profile.
Compare Personal Loan Options
Hippo is one way to compare personal loans, but it isn’t the only comparison service available in South Africa.
FatCat Loans also allows you to submit one online request to explore personal loan options from participating providers.
We’re not a lender, and submitting a request doesn’t guarantee that a loan will be available. Any offer you receive will depend on the participating credit provider’s eligibility, affordability and credit assessment.
Before accepting any loan, compare the interest rate, fees, monthly repayment, repayment period and total cost.
Final Verdict: Is Hippo Worth Using for Personal Loans?
Hippo offers a convenient way for South Africans to explore personal loan options without starting separately with every lender.
Its biggest strength is straightforward: comparison.
As of September 2026, Hippo advertises seven personal-loan providers and publishes useful information about their indicative loan amounts, interest rates and repayment periods. The comparison service is free for consumers, and Hippo states that using the comparison itself doesn’t affect your credit score.
But Hippo isn’t a lender, and its comparison is limited to the providers participating on its panel rather than every personal-loan provider in South Africa.
Any option shown during the comparison process still needs to be assessed by the relevant credit provider, and an illustrative quote or calculator result shouldn’t be treated as guaranteed approval.
For borrowers, the sensible approach is to use comparison tools as research tools rather than focusing only on how much money is available.
Compare the final offers carefully, check who the actual lender is and make sure the repayments remain affordable throughout the full loan term.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.