Barko Loans South Africa Review 2026: Fees, Requirements & How It Works
September 10, 2026
Barko Loans Review: What You Need to Know
Last Updated: September 2026
If you’re considering Barko loans in South Africa, the first thing to understand is that Barko specialises in relatively small, short-term loans rather than the larger personal loans commonly repaid over several years.
Barko currently advertises short-term loans from R300 to R8,000. Its loans are generally designed to meet short-term cash-flow needs and are repaid in one instalment, rather than through monthly repayments over several years.
That repayment structure matters.
A small loan may look manageable when you apply, but interest, initiation fees, service fees and credit-life insurance can make the total amount you need to repay considerably higher than the amount you receive.
This Barko Loans review looks at the lender’s current loan amounts, interest rates, fees, eligibility requirements, application process, credit checks and repayment structure, as well as what borrowers should consider before accepting an offer.
Important: FatCat Loans is a loan comparison service and not a lender. Barko Financial Services is a separate credit provider and is not affiliated with FatCat Loans. Approval, amounts and costs depend on Barko’s assessment and your individual circumstances.
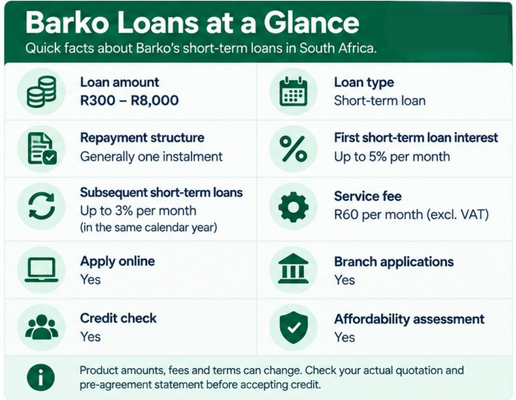
Barko Loans at a Glance
| Feature | Barko Loans |
|---|---|
| Loan type | Short-term loan |
| Advertised amount | R300–R8,000 |
| Repayment structure | Generally one instalment |
| First short-term loan interest | Up to 5% per month |
| Subsequent short-term loans in same calendar year | Up to 3% per month |
| Service fee | R60 per month excluding VAT |
| Initiation fee | Applies |
| Credit-life insurance | Included where applicable; cost varies |
| Online applications | Yes |
| Branch applications | Yes |
| Credit check | Yes |
| Affordability assessment | Yes |
| Credit provider | Barko Financial Services (Pty) Ltd |
| NCR registration | NCRCP 1764 |
| FSP number | 45614 |
Product amounts, fees and terms can change. Check your actual quotation and pre-agreement statement before accepting credit.
What Is Barko Loans?
Barko Financial Services is a South African credit provider specialising in short-term lending.
Unlike a comparison platform such as FatCat Loans or Hippo, Barko provides the credit itself.
If Barko approves your application and you accept its offer, your credit agreement is therefore with Barko.
The lender currently provides access through both digital and physical channels, including:
- online applications
- physical branches
- online support
- telephone customer service
Barko Financial Services states that it is registered with the National Credit Regulator under NCRCP 1764 and is an authorised Financial Services Provider under FSP 45614.
How Much Can You Borrow From Barko?
Barko currently advertises loans ranging from R300 to R8,000.
The R8,000 figure is the product maximum rather than an amount every applicant will necessarily qualify for.
Your available amount can depend on factors such as:
- your income
- regular expenses
- existing credit repayments
- other financial commitments
- credit history
- affordability
This is particularly important with short-term borrowing.
Being able to borrow R8,000 does not mean an R8,000 loan is necessarily appropriate for your budget.
Because Barko loans are generally repaid over a short period and in one instalment, you need to consider whether you’ll actually have enough disposable income to meet the full repayment when it becomes due.
If you’re trying to understand how lenders determine your borrowing capacity, read our guide to how much you can borrow in South Africa.
What Interest Rate Does Barko Charge?
Barko currently states that the maximum interest applicable to its short-term credit is:
First short-term loan during a calendar year:
Up to 5% per month
Subsequent short-term loans during the same calendar year:
Up to 3% per month
This is an important distinction from conventional personal loans, where consumers are more accustomed to seeing annual interest rates.
And interest isn’t the only cost.
A Barko loan can also include:
- an initiation fee
- monthly service fee
- VAT on applicable fees
- credit-life insurance
That means the total amount you repay can be significantly higher than the amount borrowed.
What Fees Does Barko Charge?
Initiation fee
An initiation fee can be charged when the loan is established.
Barko’s published information describes the initiation-fee structure as being subject to the limits permitted under South African credit regulations.
The exact fee applicable to your loan should appear in your quotation.
Monthly service fee
Barko currently publishes a service fee of:
R60 per month excluding VAT.
For a short-term agreement, even relatively small fixed fees can have a significant effect when compared with the amount borrowed.
Credit-life insurance
Credit-life cover can also form part of the borrowing cost.
Barko publishes rates for credit-life cover calculated according to the amount borrowed, with different cover levels potentially available.
Don’t treat insurance as a miscellaneous fee.
Check:
- what the policy covers
- exclusions
- whether there is a waiting period
- the premium
- what happens if you lose your job or become unable to work
- whether alternative qualifying cover can be supplied
How Much Does a Barko Loan Actually Cost?
This is one of the most useful ways to understand short-term borrowing.
Barko publishes a worked example based on a R1,000 loan over 31 days.
Its example shows:
| Cost | Example |
|---|---|
| Loan amount | R1,000.00 |
| Initiation fee | R150.00 |
| Deferred amount | R1,150.00 |
| Service fee | R60.00 |
| VAT on applicable fees | R31.50 |
| Credit-life cover | R6.33 |
| Interest | R59.42 |
| Total repayment | R1,307.24 |
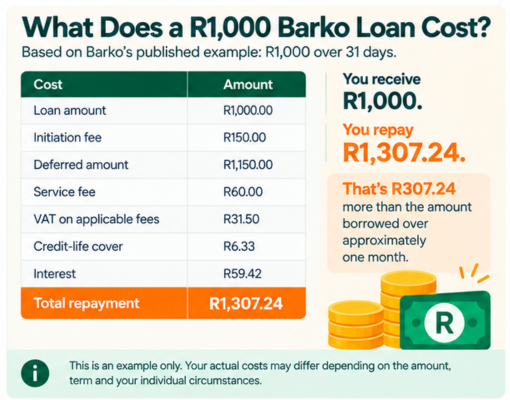
So in Barko’s example:
You receive R1,000.
You repay R1,307.24.
That’s R307.24 more than the amount borrowed over approximately one month.
This doesn’t mean every Barko R1,000 loan will cost exactly R1,307.24. The amount will depend on the agreement and applicable charges.
But it illustrates an important point:
The interest rate alone doesn’t tell you what a short-term loan really costs.
Initiation fees, service charges, VAT and insurance can make up a substantial part of the total repayment.
Why Does Barko’s Calculator Sometimes Show Different Costs?
Barko provides an online loan calculator that can give you an estimated repayment.
But the calculator shouldn’t be treated as a guaranteed quote.
The final cost can depend on:
- amount borrowed
- repayment date
- number of days the loan remains outstanding
- applicable interest rate
- initiation fee
- service fee
- credit-life insurance
- whether it’s your first short-term loan during that calendar year
Always rely on the final pre-agreement statement and quotation rather than an online estimate.
Is 5% Per Month the Same as 5% APR?
No.
This is an important distinction.
Barko’s published maximum for a first short-term loan is expressed as 5% per month, not 5% per year.
And even that interest rate doesn’t represent the full cost of credit because other permitted charges can apply.
That’s why short-term loans are often easier to compare using:
Amount borrowed → total amount repayable → repayment date
rather than focusing on one percentage alone.
Who Can Qualify for a Barko Loan?
Barko’s current application information indicates that applicants generally need to:
- be at least 18 years old
- be a South African citizen
- have a stable source of income
- have valid identification
- provide proof of income
- have an active bank account
- pass the required affordability and credit assessments
Meeting these basic requirements does not guarantee approval.
Barko still needs to decide whether the loan is appropriate based on your financial circumstances.
What Documents Do You Need for Barko Loans?
Depending on the application, you may need:
South African identification
Barko needs to verify who you are.
Proof of income
This may include a recent payslip or other accepted income evidence.
Bank statements
Barko’s application information refers to recent bank statements, commonly covering approximately three months.
Bank account information
You’ll need an active bank account for receiving the funds and arranging repayment.
Having the documents ready can help prevent unnecessary delays, but it doesn’t guarantee that credit will be approved.
How to Apply for a Barko Loan
Step 1: Choose how you want to apply
You can begin a Barko application online or seek assistance through one of its branches.
Step 2: Enter your details
The application requires personal and contact information, including identification and mobile details.
Step 3: Provide financial information
You’ll need to provide information about your income and other relevant financial circumstances.
Step 4: Credit and affordability assessment
Barko states that its lending is subject to a credit check and mandatory affordability assessment.
This helps determine whether credit can be granted and what amount may be affordable.
Step 5: Review the offer
If Barko approves your application, review the complete offer before accepting.
Check:
- amount borrowed
- interest rate
- initiation fee
- service fee
- insurance
- repayment date
- total amount repayable
Step 6: Approve the repayment arrangement
Barko repayments are generally arranged through a debit order, and a DebiCheck mandate may be used to confirm the debit.
Step 7: Receive the money
If the application is approved and all requirements are completed, funds can be paid into your bank account.
Can You Apply for a Barko Loan Online?
Yes.
Barko accepts online applications from South African borrowers.
Customers can also use branches if they prefer face-to-face assistance.
That gives borrowers more choice than lenders that operate exclusively online.
An online application can be convenient, but don’t confuse a fast application process with guaranteed approval.
The lender still needs to complete the necessary assessment and verification.
How Quickly Can You Get a Barko Loan?
Barko promotes a relatively quick application and decision process, and qualifying customers may receive approval rapidly.
However, it’s better to avoid describing Barko loans as guaranteed instant cash.
Actual timing can depend on:
- completing the application correctly
- document verification
- affordability assessment
- credit checks
- banking arrangements
- acceptance of the credit agreement
A fast application does not mean every borrower will receive funds immediately.
Does Barko Perform a Credit Check?
Yes.
Barko states that applications are subject to a credit check and affordability assessment.
This means searches such as:
“Barko loan without a credit check”
or
“guaranteed Barko loans”
should be treated cautiously.
They don’t accurately describe Barko’s published lending process.
If you’re unsure what happens when lenders access credit information, see our guide to soft vs hard credit checks in South Africa.
Can You Get a Barko Loan With Bad Credit?
Possibly, but there is no guaranteed bad-credit approval.
Barko needs to assess each application according to its lending criteria and affordability requirements.
Your result may depend on:
- credit repayment history
- existing debts
- recent applications
- income
- expenses
- affordability
A weaker credit profile could affect whether you’re approved or how much credit is available.
But there isn’t one credit-score number that automatically tells you whether Barko will approve or decline your application.
If you’ve already had a loan application declined, repeatedly applying to several more lenders isn’t necessarily the best response. It may be better to understand the reasons first.
How Are Barko Loans Repaid?
Barko’s short-term product is generally structured around one repayment rather than instalments spread across several years.
That means affordability needs to be approached differently.
Imagine you borrow R3,000 and your total repayment ends up substantially higher once interest, fees and insurance are included.
You need to be confident that the full amount can leave your bank account when it becomes due without preventing you from paying rent, food, transport or other essential expenses.
If making the repayment would leave you needing another short-term loan immediately afterwards, the original loan may not be solving your financial problem.
What Happens if You Can’t Repay a Barko Loan?
If you think you’re going to struggle with the repayment, contact Barko as early as possible.
Don’t simply ignore the debit or wait for the account to become seriously overdue.
Missed repayments can potentially result in:
- arrears
- additional permitted charges
- collection activity
- negative credit-bureau information
- damage to your credit profile
- further recovery action
Also be cautious about taking another expensive short-term loan simply to repay Barko.
That can create a borrowing cycle where more and more of your income is being used to service old debt.
If you’re consistently relying on credit to meet everyday expenses, another short-term loan may not be the appropriate solution.
Barko Loans vs Longer-Term Personal Loans
Barko’s loans serve a very different purpose from conventional personal loans.
| Barko short-term loan | Longer-term personal loan |
|---|---|
| Currently R300–R8,000 | Potentially much larger |
| Short repayment period | Repaid over months or years |
| Generally one repayment | Regular monthly instalments |
| Short-term monthly interest structure | Usually annual interest rate |
| Suitable for smaller temporary needs | Can finance larger expenses |
| Fees can be significant relative to amount borrowed | Costs spread over longer period |
Neither structure is automatically cheaper or better.
A longer-term loan can reduce the monthly repayment but may mean paying interest for years.
A short-term loan clears the debt sooner but can place substantial pressure on one pay cycle.
If you’re looking for a larger amount or want to spread repayments over a longer period, compare personal loans in South Africa before deciding.
Barko Loans vs Other Short-Term Loans
If you’re comparing Barko with other short-term loan options in South Africa, don’t focus only on which provider advertises the largest loan or quickest payout.
Compare:
Total repayment
How much will you repay in rand?
Interest rate
What rate applies to your specific agreement?
Initiation fee
What once-off cost is charged?
Service fee
Are monthly service fees added?
Insurance
Does credit-life insurance apply and how much does it cost?
Repayment date
When does the full amount need to be repaid?
Affordability
Can you make that repayment without needing to borrow again?
That final question is particularly important.
A loan isn’t affordable merely because a lender is willing to approve it.
Is Barko Legit?
Barko Financial Services is a South African financial-services business and registered credit provider. Consumers can verify credit providers through the National Credit Regulator (NCR).
The company publishes:
Company: Barko Financial Services (Pty) Ltd
Registration: 1999/022139/07
NCR registration: NCRCP 1764
FSP: 45614
Head office: Menlyn Woods Office Park, 291 Sprite Avenue, Faerie Glen, Pretoria
These details can help consumers distinguish the genuine company from people or websites impersonating legitimate lenders.
Always obtain contact and application information from Barko’s official channels rather than relying on unsolicited WhatsApp, SMS or social-media loan offers.
Barko Loans Contact Details
Barko currently publishes:
Toll-free: 080 777 3777
Head office: 087 980 5002
Customer care: [email protected]
General enquiries: [email protected]
Barko also has a branch locator for customers who want to visit a physical location.
Contact details can change, so confirm them on Barko’s official website before providing sensitive personal information.
Advantages of Barko Loans
Small loan amounts
The R300 starting amount can be useful if you need a relatively small sum and don’t want to take a much larger personal loan.
Online and branch applications
Borrowers can start online or use physical locations.
Published cost information
Barko provides relatively detailed information about its interest, fees, insurance and example loan costs.
Registered provider
Its NCR and FSP details are publicly available.
Short borrowing period
Borrowers aren’t necessarily committing to several years of repayments.
Potential Drawbacks of Barko Loans
Costs can be high relative to the amount borrowed
Barko’s own R1,000 example results in a total repayment of R1,307.24 over 31 days.
One repayment can strain cash flow
The loan may need to be cleared from a single pay cycle rather than spread over many monthly instalments.
Limited loan size
R8,000 may not be sufficient for larger expenses.
Approval isn’t guaranteed
Applications remain subject to affordability and credit assessments.
Repeat use can become expensive
Repeated short-term borrowing can create a cycle where increasingly more income goes towards previous credit.
Who Might a Barko Loan Suit?
A Barko loan may be worth considering if you:
- need a relatively small amount
- have stable income
- understand exactly what the loan will cost
- can comfortably afford the full repayment
- want short-term rather than multi-year borrowing
It may be less suitable if:
- you need more than R8,000
- you want to spread repayments over a long period
- you’re already struggling with other debts
- you’re borrowing for routine living costs every month
- repaying Barko would force you to borrow again immediately
The question isn’t simply whether you can qualify for the loan.
It’s whether your budget can comfortably absorb the entire repayment.
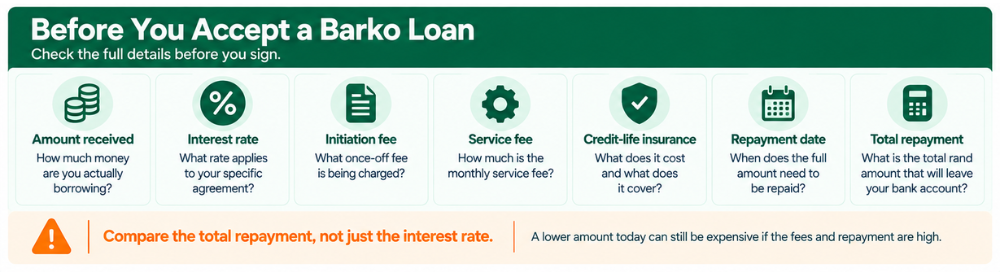
What Should You Check Before Accepting a Barko Loan?
Before signing, check the final quotation carefully.
Amount borrowed
How much money will you actually receive?
Interest
What rate applies to your agreement?
Initiation fee
What is the once-off charge?
Service fee
What service charge applies?
Credit-life insurance
How much does it cost and what does the policy cover?
Repayment date
Exactly when must the money be repaid?
Total repayment
What is the total rand amount that will leave your bank account?
This last number is often the most useful.
If you receive R1,000 but need to repay more than R1,300, that tells you more about the effect on your budget than simply being told the interest rate is 5% per month.
Frequently Asked Questions About Barko Loans
How much can I borrow from Barko?
Barko currently advertises short-term loans from R300 to R8,000. The amount available to you depends on Barko’s affordability and credit assessment.
What interest rate does Barko charge?
Barko states that short-term credit can carry interest of up to 5% per month for the first short-term loan in a calendar year and 3% per month for subsequent short-term loans during that year. Other permitted charges may also apply.
What do I need to apply for a Barko loan?
Basic requirements include being at least 18, having a stable source of income, valid identification, proof of income and an active bank account. Supporting bank statements may also be required.
Can I apply for a Barko loan online?
Yes. Barko accepts online applications and also provides assistance through physical branches.
Does Barko check your credit?
Yes. Barko states that applications are subject to a credit check and mandatory affordability assessment.
Is Barko registered with the NCR?
Yes. Barko Financial Services identifies itself as a registered credit provider under NCRCP 1764 and an authorised financial services provider under FSP 45614.
Compare Loan Options in South Africa
Barko specialises in relatively small short-term loans, but that isn’t the only borrowing structure available.
If you want to explore other possibilities, FatCat Loans allows you to submit one online request to see whether options may be available from participating providers.
We’re not a lender, and submitting a request doesn’t guarantee approval. Any available offer depends on the participating lender’s eligibility, affordability and credit assessment.
Before accepting any loan, compare:
- interest
- fees
- repayment period
- repayment amount
- insurance
- total cost of credit
Final Verdict: Is Barko Worth Considering?
Barko is a South African credit provider specialising in small, short-term loans from R300 to R8,000.
That makes it fundamentally different from lenders offering large personal loans that are repaid over several years.
One positive feature is Barko’s relatively transparent approach to costs. The lender publishes information about interest, initiation and service fees, credit-life insurance and worked borrowing examples.
But those examples also demonstrate why borrowers need to look carefully at the total cost.
In Barko’s own 31-day example, R1,000 borrowed results in R1,307.24 being repayable after interest, fees, VAT and insurance.
For someone already experiencing a cash-flow shortage, finding that additional R307.24 only a few weeks later could be significant.
Barko may therefore be worth considering if you need a genuinely small amount for a short-term expense and can comfortably afford the entire repayment when it falls due.
It may be less suitable if you’re looking for a large loan, need a long repayment period or are already struggling to keep up with existing debts.
Whatever borrowing option you consider, don’t judge it solely by how quickly you can get the money.
Compare what you receive, what you’ll repay, when repayment is due and whether your budget can comfortably handle the full cost.
The FatCat Loans Editorial Team delivers clear, accurate, and unbiased guidance on loans, credit, and personal finance in South Africa, in compliance with the National Credit Act. Our writers follow strict editorial standards to ensure every article is trustworthy, well-researched, and easy to understand, helping readers make confident financial decisions.