Ackermans Loans Review South Africa (2026): Fees & Requirements

Thinking about Ackermans loans in South Africa? Learn how they work, what they cost, and whether better alternatives are available before you apply.

Ackermans Loans Review South Africa

Published March 2026

Ackermans is one of South Africa’s most established retail brands — but how do Ackermans loans South Africa actually work, and are they a good option if you need cash?

In this detailed Ackermans loans review South Africa, we break down how Ackermans credit works, who qualifies, the fees involved, and whether there are better alternatives.

Ackermans loans are typically offered through a third-party credit provider, making them more similar to personal loans than basic store credit.

If you’re comparing lenders, you can also read our full PEP loans review South Africa to see how similar retail credit options compare.

If you’re exploring different options, you can also view personal loans in South Africa to compare more flexible alternatives.

Quick answer: Ackermans loans offer accessible borrowing options with higher loan limits than most retail lenders, but costs and approval requirements may be higher than basic store credit.

Explore other personal loan options with FatCat Loans.


Quick Verdict: Is Ackermans Loans Worth It?

Best for: Medium-sized loans with retail accessibility
Not ideal for: Lowest-cost borrowing or highly flexible terms

Pros

  • Higher loan limits than typical retail credit
  • Fast approval process
  • Available in-store across South Africa
  • Structured repayment terms

Cons

  • Requires proof of income
  • Interest and fees can be high
  • Less flexible than some online lenders
  • Approval depends on affordability

Bottom line: Ackermans loans are a step up from basic store credit, but they are still more expensive than many traditional loan options.


What Are Ackermans Loans?

Ackermans offers access to loans through a registered credit provider, typically Capfin, rather than directly issuing loans itself.

This means Ackermans loans are closer to unsecured personal loans than standard retail accounts.

Typical features:

  • Loan amounts from around R1,000 up to R50,000
  • Repayment terms between 6 and 24 months
  • Monthly instalment payments
  • No collateral required

Compared to store-only credit, this makes Ackermans loans more flexible for broader financial needs.

Ackermans Loans vs Capfin: What’s the Difference?

While you apply through Ackermans, the loan is typically provided by Capfin, a registered credit provider. You can read our full Capfin loans review South Africa to understand how the lending process works in more detail.

This means:

  • Ackermans acts as the access point
  • Capfin handles approval and lending
  • Terms and conditions are set by the lender

Understanding this helps clarify who is responsible for your loan agreement.


What It’s Like to Apply for an Ackermans Loan

Applying for an Ackermans loan is designed to be fast and accessible.

Typical process:

  1. Visit an Ackermans store or apply online
  2. Provide ID and proof of income
  3. Submit bank statements or payslips
  4. Receive a decision (often within minutes)

Many borrowers choose Ackermans because of its wide store network and quick approval process.


How Ackermans Loans Work

Ackermans loans are structured as instalment loans rather than payday loans.

Key features:

  • Fixed monthly repayments
  • Longer loan terms than payday loans
  • Loan amounts based on affordability
  • Funds deposited into your bank account

Unlike smaller retail credit products, these loans can be used for broader expenses like bills, emergencies, or school fees.


Ackermans Loans Fees & Costs

Understanding the cost of Ackermans loans South Africa is essential before applying.

Costs may include:

  • Interest (based on your credit profile)
  • Initiation fees
  • Monthly service fees
  • Credit life insurance

Interest rates are personalised based on your risk profile, meaning better credit may result in lower costs.

Important: Always check your total repayment amount before accepting a loan offer.

Many unsecured personal loans in South Africa can carry significantly higher total repayment costs depending on risk profile and term length.


Real Cost Example (Illustration)

  • Loan amount: R10,000
  • Term: 12 months
  • Total repayment: ~R13,000–R15,000 (varies)

Key takeaway: Longer terms reduce monthly payments but increase total cost.


Example Monthly Repayments

Loan Amount Estimated Fees Total Repayment Monthly Payment
R5,000 R1,000 R6,000 R500 x 12 months
R10,000 R3,000 R13,000 R1,083 x 12 months
R20,000 R8,000 R28,000 R2,333 x 12 months

How Much Should You Borrow?

Just because you qualify for a certain loan amount doesn’t mean you should take the maximum.

  • Keep repayments under 30% of your disposable income
  • Allow room for unexpected expenses
  • Avoid borrowing for non-essential purchases

Choosing a smaller loan amount can reduce financial pressure and total interest paid.


Why Many Borrowers Choose Ackermans Loans

Borrowers often choose Ackermans loans because they provide access to mid-sized loans in South Africa with relatively simple requirements.

  • Accessible through physical stores
  • Higher loan amounts than store credit
  • Fast approval process
  • Structured repayment plans

They are especially useful for borrowers who need more than small retail credit but still want accessible lending options.

For many borrowers, this type of loan fills a gap when traditional credit isn’t an option.


Risks to Be Aware Of

  • Higher costs than bank loans
  • Strict affordability checks
  • Potential fees if payments are missed
  • Debt risk if overused

For many borrowers, understanding these risks upfront can help prevent long-term financial strain.


What Happens If You Miss a Payment?

If you miss a repayment on an Ackermans loan, you may face:

  • Late payment fees
  • Negative impact on your credit record
  • Collection activity if payments are missed repeatedly

It’s important to contact your lender early if you’re struggling — many providers may offer alternative arrangements.


Ackermans Loans Requirements

To qualify, you typically need:

  • South African ID
  • Proof of income (payslips or bank statements)
  • Active bank account
  • Stable employment

Approval is based on affordability and your ability to repay the loan.


What Actually Affects Approval for Ackermans Loans?

While basic requirements are simple, approval is based on a deeper affordability assessment.

  • Your monthly income vs expenses
  • Existing debt obligations
  • Your repayment history
  • Bank account activity

Key insight: Even if you meet the basic requirements, approval depends on whether the loan fits within your budget.


Is Ackermans Loans Legit & Safe?

Yes — Ackermans loans are offered through a registered credit provider and must comply with South Africa’s National Credit Act (NCA), which ensures responsible lending practices.

This includes:

  • Affordability assessments
  • Transparent fees
  • Consumer protection regulations

Ackermans Loans vs Other Lenders

Feature Ackermans Loans PEP Loans Bank Loans
Loan Amount Medium–High Low Medium–High
Approval Speed Fast Fast Slower
Credit Requirements Medium Low High
Flexibility Medium Low High

Key takeaway: Ackermans offers higher loan amounts than PEP, but with stricter requirements.


Better Alternatives to Ackermans Loans

1. Online Lenders

Platforms like FatCat Loans allow you to compare multiple lenders and find better options.

2. Bank Loans

Offer lower interest rates and more flexibility.

3. Retail Alternatives

Retail credit options like PEP may offer easier access for smaller loans.

You can also compare loan options in South Africa to find better alternatives.


Best Use Cases for Ackermans Loans

  • Covering short-term financial gaps
  • Paying for school fees or essentials
  • Managing unexpected expenses
  • Consolidating small debts

When Should You Use Ackermans Loans?

  • You need a medium-sized loan
  • You can meet affordability requirements
  • You want structured repayments

When to Avoid Ackermans Loans

  • You need the lowest interest rates
  • You have access to bank loans
  • You are already struggling with debt

When Ackermans Loans May Not Be the Right Choice

  • Funding non-essential purchases
  • Covering ongoing monthly shortfalls
  • Repaying other high-interest debt repeatedly

If you’re unsure whether Ackermans is the right option, you can compare loan options in South Africa to find a better fit.


Ackermans Loans Review South Africa: Final Verdict

Ackermans loans offer more flexibility and higher limits than most retail credit options, making them a useful middle-ground between store credit and traditional loans.

Final Rating: 4/5

  • Best for: Medium loan amounts with fast access
  • Not ideal for: Lowest-cost borrowing

From a financial perspective, instalment loans like those offered through Ackermans should be used carefully and only when repayments are manageable within your budget.


Final Thoughts

Ackermans loans can be a useful option if you need easy access to credit with structured repayments.

However, it’s always worth comparing lenders before applying.

Before applying, take a moment to compare loan options in South Africa to find the most affordable option.

Explore other personal loan options with FatCat Loans.


Ackermans Loans FAQs

Does Ackermans offer personal loans in South Africa?

Ackermans offers access to loans through a third-party credit provider rather than issuing large traditional bank-style loans directly. These loans are generally structured as unsecured instalment loans with fixed monthly repayments.

How much can you borrow from Ackermans?

Loan amounts depend on your income, affordability assessment, and credit profile. In general, Ackermans loans offer higher borrowing limits than basic retail credit, making them more suitable for medium-sized expenses.

Do you need good credit for Ackermans loans?

You do not necessarily need perfect credit, but approval is based on affordability and your overall financial profile. Borrowers with stable income and a reasonable repayment history are more likely to qualify.

How fast is approval for Ackermans loans?

Approval is usually quick, often within minutes once your documents and affordability checks have been completed. Funding speed may vary depending on the lender and verification process.

Are Ackermans loans safe?

Yes — Ackermans loans are offered through a registered credit provider and are regulated under South Africa’s National Credit Act. This means lenders must follow rules around affordability checks, transparency, and responsible lending.

Are Ackermans loans better than PEP loans?

Ackermans loans generally offer higher loan amounts and more structured repayment terms than PEP loans. However, PEP loans may be easier to access for smaller borrowing needs. The better option depends on how much you need and what you can comfortably afford to repay.

Can you use Ackermans loans for emergencies?

Yes, Ackermans loans can be used for emergency expenses, school fees, bills, or other short-term financial needs. However, it’s important to make sure the monthly repayments fit your budget before applying.

PEP Loans Review South Africa (2026): Fees & Requirements

Looking at PEP loans in South Africa? Learn how they work, the real costs, and whether better alternatives are available.

PEP Loans Review South Africa

Last Updated: September 2026

If you’re searching for PEP loans in South Africa, the loan you can apply for through PEP is provided by Capfin, a registered South African credit provider.

Capfin currently offers personal loans of up to R50,000, with repayment terms of 6, 12 or 24 months. You can apply online through Capfin or submit an application through participating PEP stores.

When you apply at PEP, the store scans your South African ID and supporting income documents and sends the application to Capfin. Capfin performs the credit and affordability assessment, makes the lending decision and finalises the loan.

This review explains how PEP loan applications work, current Capfin loan amounts, repayment terms, requirements, costs and payout times. You can also compare other providers in the FatCat Loans lender network before deciding which option suits your needs.

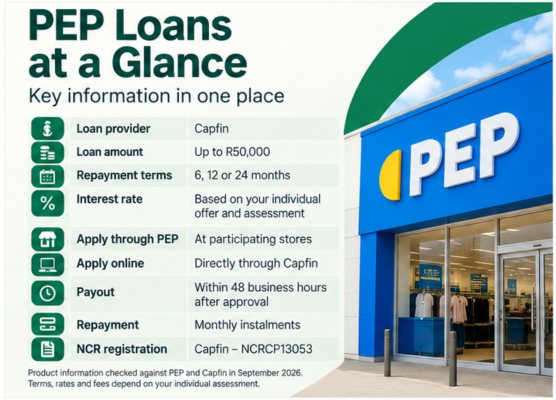
PEP Loans at a Glance

Loan provider Capfin
Loan amount Up to R50,000
Repayment terms 6, 12 or 24 months
Interest rate Fixed rate based on your individual loan offer and assessment
Application through PEP Available at participating PEP stores
Online application Available directly through Capfin
Payout Within 48 business hours after approval
Repayment Monthly instalments by debit order
Credit provider Capfin – NCRCP13053

Product information checked against PEP and Capfin in September 2026. The amount, term, rate and repayment offered depend on Capfin’s credit and affordability assessment.

What Are PEP Loans?

“PEP Loans” commonly refers to Capfin personal loans that customers can apply for through participating PEP stores. PEP provides an application channel, while Capfin is the credit provider responsible for assessing and providing the loan. If you want more detail about the lender itself, including its loan structure, costs and eligibility requirements, read our full Capfin loans review

Capfin is a division of Pepkor Trading (Pty) Ltd and is registered with the National Credit Regulator under NCRCP13053.

This distinction is important because your loan agreement, interest rate, fees, repayments and affordability assessment are ultimately with Capfin, rather than a separate PEP-branded lender.

What It’s Like to Apply for a PEP Loan

Applying for PEP credit is designed to be simple and accessible.

Typical process:

  1. Visit a PEP store or apply through available channels
  2. Provide ID and proof of income
  3. Complete a short application
  4. Receive a decision (often quickly)

Many borrowers choose PEP because of:

  • Accessibility
  • Minimal paperwork
  • Fast approvals

This makes it appealing for borrowers who may not qualify for traditional bank loans.

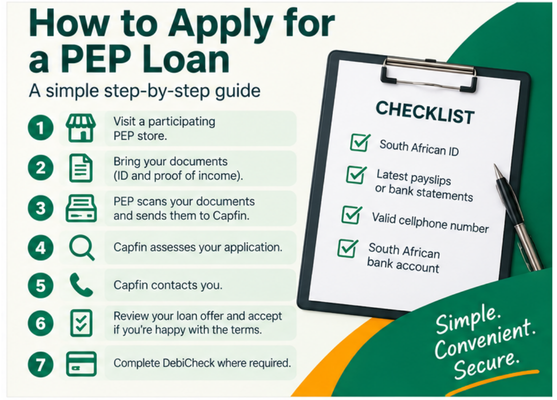
How to Apply for a Capfin Loan at PEP

You can submit a Capfin loan application through a participating PEP store.

  1. Visit a participating PEP store.
  2. Bring your documents. You will need your valid South African ID and either your three latest payslips or three latest bank statements.
  3. PEP scans your documents. The store uses its document-scanning process to send the application information to Capfin.
  4. Capfin assesses your application. Your income, expenses, credit profile and payment behaviour can form part of the affordability and credit assessment.
  5. Capfin contacts you. If your application progresses, Capfin will contact you to finalise the process.
  6. Review your loan offer. Check the approved amount, interest rate, fees, monthly instalment and total repayment before accepting.
  7. Complete DebiCheck. Where required, approving the debit-order mandate is part of finalising the loan.

You can also apply directly through Capfin online or via its other available application channels.

Steps to apply for a PEP loan

PEP Loan Interest Rates, Fees and Repayments

The cost of a loan applied for through PEP is determined by Capfin. Your actual interest rate, fees and monthly instalment are shown in the pre-agreement statement and quotation provided for your application.

Capfin states that its personal loans use a fixed interest rate. Your repayment also includes applicable fees and Capfin Credit Life.

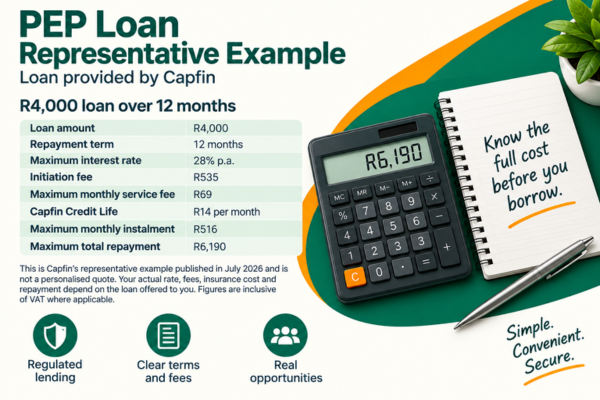
Capfin Representative Repayment Example

Capfin currently publishes the following example for a R4,000 loan over 12 months:

Loan amount R4,000
Repayment term 12 months
Maximum interest rate 28% p.a.
Initiation fee R535
Maximum monthly service fee R69
Capfin Credit Life R14 per month
Maximum monthly instalment R516
Maximum total repayment R6,190

This is Capfin’s representative example published in July 2026 and is not a personalised quote. Your actual rate, fees, insurance cost and repayment depend on the loan offered to you. Figures are inclusive of VAT where applicable.

PEP Loan Requirements

According to PEP and Capfin, applicants generally need:

  • A valid South African ID
  • Your three latest payslips or three latest bank statements
  • Permanent employment and a monthly salary
  • A valid cellphone number
  • A valid South African bank account supported by Capfin

Providing these documents does not guarantee approval. Capfin considers factors including your income, expenses, credit profile and payment behaviour as part of its affordability and credit assessment.

Why Many Borrowers Choose PEP Loans

PEP loans are often used by borrowers looking for loans for low income earners in South Africa, especially when access to traditional banking products is limited.

Common reasons:

  • Limited access to traditional credit
  • Need for small, quick loans
  • Convenience of in-store applications
  • Trusted retail brand

Many borrowers choose PEP because of its accessibility and fast approval process, especially if they are looking for same-day loans in South Africa or loans for bad credit in South Africa.

For many borrowers, this type of credit isn’t a first choice — it’s often the only option available at the time.

Does Capfin Perform a Credit Check?

Yes. Capfin states that the amount you may qualify for is subject to its affordability assessment and additional credit checks. Factors considered can include your income, expenses, credit profile and payment behaviour.

A weaker credit profile does not automatically tell you whether you will qualify. Approval and the amount offered depend on Capfin’s overall assessment of your application.

Risks to Be Aware Of

Like any form of credit, there are risks.

Key risks:

  • Higher costs compared to bank loans
  • Limited flexibility
  • Risk of repeat borrowing
  • Budget strain from repayments

While PEP loans are helpful, they should be used carefully and only when necessary.

For many borrowers, understanding these risks upfront can help prevent long-term financial strain.

PEP Loans Requirements

PEP aims to make credit accessible, so requirements are generally straightforward.

You’ll typically need:

  • South African ID
  • Proof of income
  • Active contact details

Approval is often based on:

  • Income
  • Affordability assessment

This makes PEP loans accessible for borrowers with limited credit history.

Are PEP Loans Legitimate?

Yes. The personal loan available through PEP is provided by Capfin, a division of Pepkor Trading (Pty) Ltd. Capfin is registered with South Africa’s National Credit Regulator under NCRCP13053.

Capfin credit agreements are subject to the National Credit Act and include a pre-agreement statement and quotation setting out the terms specific to the loan offered to you.

Being registered does not mean a particular loan is affordable for your circumstances. Review the interest rate, fees, insurance cost, monthly instalment and total repayment before accepting an offer.

PEP loan amounts, terms and requirements

How Long Does a PEP Loan Take to Pay Out?

Capfin states that approved loans are paid into the nominated bank account within 48 business hours after approval.

Funding can take longer if there is a delay in approving the required DebiCheck mandate with your bank. The 48-business-hour timeframe should therefore be treated as Capfin’s stated payout timeframe rather than a guarantee that every borrower will receive funds at exactly the same time.

What Happens If You Cannot Make a Capfin Repayment?

If you expect to miss a payment, contact Capfin as soon as possible rather than ignoring the repayment.

Capfin’s loan terms state that instalments are normally collected by debit order. If there are insufficient funds, Capfin may represent the payment instruction when funds become available. Falling into arrears can also result in additional costs and collection or legal action under the credit agreement.

Capfin advises customers who miss a payment to contact its support team to discuss how to bring the account up to date.

PEP loan repayment and fee example

Comparing PEP Loans With Other Personal Loans

Applying through PEP can be convenient if you prefer submitting documents in-store, but the loan itself is still a Capfin personal loan. Before accepting an offer, compare the personalised interest rate, fees, insurance cost, monthly repayment and total amount repayable with other regulated lenders.

If you need to compare alternatives, you can explore personal loans in South Africa or review other providers available through FatCat Loans.

Do not compare loans using the monthly instalment alone. A longer repayment period can lower the monthly payment while increasing the total amount you repay.

PEP Loans Review South Africa: Final Verdict

PEP loans provide accessible credit for everyday needs, especially for borrowers who may not qualify elsewhere.

However, the trade-off is higher costs and limited flexibility.

Final Rating: 3.5/5

Use PEP if:

  • You need quick, small credit
  • You value convenience

Avoid if:

  • You need larger or lower-cost loans

Sources & Verification

Product information in this review was checked against official PEP and Capfin information in September 2026.

Loan amounts, rates, fees, requirements and processing times can change. Check the current terms and your personalised pre-agreement quotation before accepting credit.

Final Verdict: What to Know Before Applying for a PEP Loan

A loan applied for through PEP is a Capfin personal loan, rather than a separate loan issued by PEP. The in-store application option may be useful for borrowers who prefer having their documents scanned at a PEP store instead of completing the entire process online.

Capfin currently offers loans of up to R50,000 with repayment terms of 6, 12 or 24 months. However, the amount, interest rate and repayment offered to you depend on Capfin’s affordability and credit assessment.

Before accepting a loan, check your pre-agreement quotation carefully. Pay particular attention to the interest rate, initiation fee, monthly service fee, Credit Life premium, monthly instalment and total amount repayable.

It is also worth comparing your personalised Capfin offer with other regulated loan options before deciding which borrowing arrangement best fits your budget.

Frequently Asked Questions About PEP Loans

Does PEP offer personal loans?

You can apply for a Capfin personal loan through participating PEP stores. PEP provides the in-store application channel, while Capfin is the registered credit provider responsible for assessing, approving and providing the loan.

How much can I borrow through PEP?

Capfin currently offers personal loans of up to R50,000. The amount you qualify for depends on your income, expenses, credit profile, payment behaviour and affordability assessment.

How long do I have to repay a PEP loan?

Capfin currently offers repayment terms of 6, 12 or 24 months, depending on the loan offer and your assessment.

What documents do I need to apply for a PEP loan?

You generally need a valid South African ID, your three latest payslips or three latest bank statements, a valid cellphone number and a supported South African bank account. Capfin also states that applicants must be permanently employed and earning a monthly salary.

Does Capfin perform a credit check?

Yes. Capfin considers your credit profile as part of its assessment and may perform additional credit checks before finalising the amount you qualify for.

How long does a PEP loan take to pay out?

Capfin states that approved loans are paid into your nominated bank account within 48 business hours after approval. Delays in approving the required DebiCheck mandate can delay payment.

Are PEP loans legitimate?

Yes. The personal loan available through PEP is provided by Capfin, a registered South African credit provider under NCRCP13053.

Can I apply for a PEP loan online?

You can apply for the Capfin personal loan directly online through Capfin. Applications can also be submitted through participating PEP stores and other application channels made available by Capfin.

Boodle Loans Review South Africa

A complete 2026 review of Boodle loans in South Africa, including interest rates, fees, requirements, risks and better alternatives.

Boodle Loans Review South Africa (2026)

Last Updated: September 2026

If you’re considering a Boodle loan in South Africa, it’s important to understand the amount you may be able to borrow, the repayment period and the total cost before applying.

Boodle is an online short-term credit provider offering loans from R500. According to Boodle, new customers may qualify for up to R5,000, while returning customers may qualify for up to R8,000, subject to affordability and application assessment. Repayment terms range from 1 to 6 months.

Before applying directly to one lender, you may also want to compare options from our lender network. FatCat Loans is a loan comparison service, not a lender, and Boodle may not be one of the lenders available through our network.

In this Boodle Loans review, we look at its current loan amounts, interest and fees, eligibility requirements, application process, repayment terms and the factors to consider before taking out short-term credit.

Boodle Loans at a Glance

Credit provider Boodle (Pty) Ltd
NCR registration NCRCP5361
Loan amount R500–R5,000 for new customers; returning customers may qualify for up to R8,000
Repayment term 1–6 months
Maximum APR 60%
Application Online
Security Unsecured

Loan amounts, terms and approval depend on Boodle’s assessment and affordability requirements. Always review the pre-agreement statement and quotation for the actual cost of your loan.

What Is Boodle?

Boodle (Pty) Ltd is a South African online credit provider specialising in small, short-term loans that do not require an asset as security.

Boodle is registered with the National Credit Regulator under NCRCP5361 and is also a registered financial services provider, FSP 50848.

The application process is completed online. Boodle states that applicants undergo credit and affordability checks before a lending decision is made.

Unlike a traditional personal loan that may be repaid over several years, Boodle loans are designed for shorter borrowing periods of between 1 and 6 months.

Compare loan options with FatCat Loans

Is Boodle Legit in South Africa?

Yes. Boodle (Pty) Ltd identifies itself as a registered South African credit provider under NCRCP5361. You can verify a credit provider’s registration using the National Credit Regulator’s register.

NCR registration means a credit provider must operate within South Africa’s credit regulatory framework, including requirements relating to affordability assessments and disclosure of credit costs.

However, registration does not mean that a particular loan is suitable or affordable for every borrower. Before accepting credit, review the interest, fees, repayment term, instalments and total repayment amount shown in your pre-agreement statement and quotation.

How Do Boodle Loans Work?

Boodle provides unsecured short-term loans through an online application process. You choose the amount and available repayment term, complete the application and provide the information Boodle needs to assess your application.

The process generally involves:

  1. Choose your loan: Select the amount you want to borrow and an available repayment term.
  2. Complete your details: Provide your personal, employment and income information and link your online banking account where required.
  3. Verification and assessment: Boodle verifies your details and carries out credit and affordability checks.
  4. Review your offer: If approved, you receive an offer showing the applicable repayment terms and costs.
  5. Accept the agreement: Once you accept and sign the agreement, approved funds are paid into your bank account.

Boodle says its average online application takes less than three minutes from start to finish. This refers to the application process and should not be interpreted as guaranteed approval or payout within three minutes.

Boodle Loan Amounts and Repayment Terms

The amount available depends partly on whether you are a new or returning Boodle customer and the outcome of your application.

Feature Current Boodle Information
New customer loan amount R500–R5,000
Returning customer maximum Up to R8,000, subject to assessment
Repayment term 1–6 months
Loan type Unsecured short-term loan
Maximum APR 60%

Returning customers are not automatically entitled to R8,000. Boodle states that the amount available depends on factors including repayment history, affordability and the result of the application assessment.

Boodle Interest Rates and Fees

The cost of a Boodle loan can include interest, an initiation fee, a monthly service fee and credit life insurance where applicable. The actual cost should be shown in your quotation before you accept the loan.

Interest

Boodle currently states a maximum annual percentage rate (APR) of 60%. The rate and cost applicable to your loan should be confirmed in your individual quotation.

Initiation Fee

An initiation fee may be charged when the credit agreement is entered into. The amount can vary according to the size of the loan and should be included in the quotation provided to you.

Monthly Service Fee

Boodle’s current representative example includes a R69 monthly service fee. The fee applicable to your own agreement should be confirmed in your quotation.

Credit Life Insurance

Credit life insurance may also form part of the cost of the loan. Boodle’s current representative example includes an insurance charge, so check whether insurance applies to your agreement and how much it adds to your repayment.

Important: Don’t compare a Boodle loan using the interest rate alone. Look at the monthly instalment and the total amount repayable, including applicable fees and insurance.

Boodle Loan Repayment Example

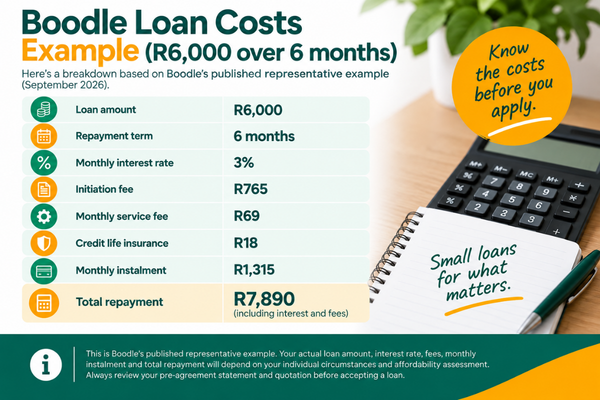
Boodle currently provides the following representative example on its website for a R6,000 loan:

Example Amount
Loan amount R6,000
Repayment term 6 months
Monthly interest rate 3%
Initiation fee R765
Monthly service fee R69
Credit life insurance R18
Monthly instalment R1,315
Total loan repayment R7,890

Boodle R6,000 loan repayment cost example

In this example, borrowing R6,000 results in a total repayment of R7,890 over six months. That is R1,890 more than the amount borrowed.

This is Boodle’s representative example and is not a personalised quotation. Your actual interest, fees, insurance, instalments and total repayment may differ depending on the loan and Boodle’s assessment.

What to Compare Before Accepting a Boodle Loan

Before accepting the loan, compare the quotation with other suitable options and look at:

  • the amount you will actually receive
  • the interest rate and applicable fees
  • credit life insurance, where applicable
  • the monthly repayment
  • the repayment term
  • the total amount you will repay

A longer repayment term may reduce the monthly instalment but can increase the total cost of borrowing. The most important question is whether the repayments are affordable alongside your existing expenses and debt commitments.

If you want to compare different borrowing structures, you can also read about personal loans in South Africa before deciding whether a short-term loan suits your needs.

Boodle Loan Requirements

According to Boodle, applicants need to meet the following basic requirements:

  • Be 18 years or older.
  • Have a valid South African ID.
  • Have access to internet banking.
  • Have verifiable income for the previous 90 days.

Boodle also carries out credit and affordability checks before deciding whether to offer a loan.

Meeting the basic requirements does not guarantee approval. The final decision depends on Boodle’s assessment of your application and affordability.

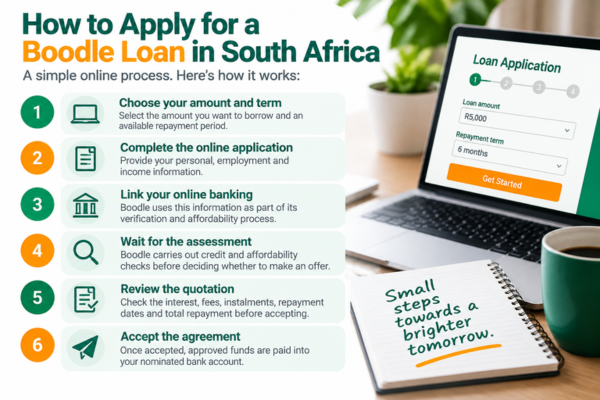
How to Apply for a Boodle Loan

Boodle’s loan application is completed online.

  1. Choose your amount and term: Select the amount you want to borrow and an available repayment period.
  2. Complete the online application: Enter your personal, employment and income information.
  3. Link your online banking: Boodle uses this information as part of its verification and affordability process.
  4. Wait for the assessment: Boodle carries out credit and affordability checks before deciding whether to make an offer.
  5. Review the quotation: If approved, check the interest, fees, instalments, repayment dates and total repayment before accepting.
  6. Accept the agreement: Once accepted, approved funds are paid into your nominated bank account.

How to apply for a Boodle loan online

How Quickly Does Boodle Pay Out?

Boodle states that customers using its fully automated process may receive approved funds within 10 minutes after accepting the quotation. Applications that require manual handling can take up to 2 hours.

These are Boodle’s stated processing times and are not a guarantee for every application, as verification and banking processes can affect timing.

Boodle Contact Details

If you need help with an application or an existing Boodle loan, the lender currently provides the following contact options:

Customer support 0861 266 353
WhatsApp 081 713 8111
Email [email protected]
Registered address 19 Ameshoff Street, Braamfontein, Johannesburg, 2001

Contact details checked against Boodle’s official website in September 2026. Contact information can change, so confirm the latest details on Boodle’s website.

Boodle Login: How to Access Your Account

If you’re an existing Boodle customer, you can sign in to your Boodle account through the official Boodle website. Your account allows you to return to an application that is still in progress and manage information relating to your Boodle loan.

How to Log In to Boodle

  1. Go to the official Boodle website.
  2. Select the option to sign in to your existing account.
  3. Enter the details requested to access your profile.
  4. Complete any security or OTP verification required by Boodle.

Boodle refers to its OTP as your Boodle Pin and states that a one-time pin may be sent when you update your profile or apply for a Boodle loan.

Can I Continue an Unfinished Boodle Application?

Yes. Boodle states that if you don’t complete the sign-up process, you can return later, sign in and continue where you left off.

If you’re having trouble accessing your account, contact Boodle on 0861 266 353, WhatsApp 081 713 8111 or email [email protected].

Security tip: Only enter your Boodle login or banking information through Boodle’s official website. Avoid signing in through links received from unfamiliar websites, messages or social media accounts.

When Comparing Boodle With Other Loan Options

Boodle is a short-term lender, so it is useful to compare its quotation with other credit options that may offer different loan amounts, repayment periods or cost structures.

Before deciding, compare:

  • the amount you need to borrow
  • the repayment term
  • the monthly instalment
  • the total amount repayable
  • interest and fees
  • whether the repayment fits your budget

Boodle vs Wonga, Capfin and Bayport

Boodle is one of several credit providers available in South Africa, but these lenders do not all offer the same type of loan. Comparing the loan amount, repayment period and total cost can help you understand the differences before applying.

You can also read our individual reviews of Wonga, Capfin and Bayport for more detailed information about each provider.

Lender Loan Type Loan Amount Repayment Term
Boodle Short-term loan R500–R5,000 for new customers; returning customers may qualify for up to R8,000 1–6 months
Wonga Short-term loan Check current lender terms Check current lender terms
Capfin Personal loan Up to R50,000 6, 12 or 24 months
Bayport Personal loan Check current lender terms Check current lender terms

Loan products and limits can change. Eligibility, available amounts, repayment terms and costs depend on the lender’s current criteria and your individual application. Check the lender’s latest quotation before accepting credit.

What Is the Main Difference?

The main difference is the type and duration of borrowing. Boodle focuses on relatively small, short-term loans, while personal-loan providers may offer larger amounts with longer repayment periods.

A longer repayment term can reduce the size of each instalment, but it can also affect the total amount repaid. A shorter loan is not automatically cheaper, and a longer loan is not automatically more affordable.

For a meaningful comparison, use the actual quotations available to you and compare the total cost of credit, repayment term and instalment rather than choosing a lender based on the advertised loan amount alone.

Compare Loan Options Before Applying

Loan amounts, repayment terms and costs can differ considerably between credit providers. Comparing options before submitting an application can help you understand what may be available without focusing on a single lender.

When comparing loans, look at:

  • the amount you need to borrow
  • the interest rate and fees
  • the repayment term
  • the monthly instalment
  • the total amount repayable
  • whether the repayments are affordable for your budget

FatCat Loans is a loan comparison service, not a lender. You can compare loan options before deciding whether to apply. Boodle may not be one of the lenders available through our network.

Compare loan options with FatCat Loans

Does a Boodle Loan Affect Your Credit Profile?

Yes. Taking out and repaying a Boodle loan can form part of your credit history.

Boodle states that repaying a loan on time can have a positive effect on your credit history. However, this does not mean that taking out a Boodle loan will automatically increase your credit score, as credit bureaus use a range of information when calculating credit scores.

Late or missed repayments can negatively affect your credit profile and may make it more difficult to access credit in the future.

If you’re trying to protect your credit record, only accept a repayment amount that you are confident you can afford alongside your other financial commitments.

What Happens If You Can’t Repay a Boodle Loan?

If you cannot make a repayment on time, contact Boodle as soon as possible rather than ignoring the missed payment.

According to Boodle, if a debit order fails, it may attempt to collect the repayment again. If the repayment remains outstanding, its collections team may contact you to discuss a payment arrangement.

Boodle currently states that a default administration fee of R75 excluding VAT may be charged when an account falls into arrears. Interest and applicable service fees may also continue while the account remains outstanding.

Continued non-payment can negatively affect your credit profile and may eventually result in the account being referred for external legal collection, which can lead to additional costs.

If you know you will struggle to make a payment, contact Boodle before the repayment date to discuss the options available to you.

How Are Boodle Loans Repaid?

Boodle states that repayments are collected by debit order from the bank account authorised during the loan application and agreement process.

The repayment amount, repayment dates and applicable costs should be shown in your loan agreement. Make sure sufficient funds are available on the agreed repayment date to avoid a failed debit order and possible additional charges.

Final Thoughts on Boodle Loans

Boodle is a registered South African credit provider offering small, unsecured short-term loans. New customers may qualify for between R500 and R5,000, while returning customers may qualify for up to R8,000, subject to Boodle’s assessment. Repayment terms range from 1 to 6 months.

Before accepting a Boodle loan, look beyond the amount you can borrow and compare the interest, fees, insurance where applicable, monthly instalment and total repayment amount shown in your quotation.

If the repayment would make it difficult to cover your normal living expenses or existing debt commitments, taking on additional credit may worsen your financial position.

FatCat Loans is a loan comparison service, not a lender. Boodle may not be one of the lenders available through our network.

See loan options with FatCat Loans

Frequently Asked Questions

Is Boodle legit in South Africa?

Yes. Boodle (Pty) Ltd is a registered credit provider with the National Credit Regulator under NCRCP5361. Boodle also identifies itself as a registered financial services provider under FSP 50848.

How much can I borrow from Boodle?

New Boodle customers may qualify for between R500 and R5,000. Returning customers who have borrowed and repaid successfully may qualify for up to R8,000, subject to affordability, repayment history and Boodle’s application assessment.

How long do I have to repay a Boodle loan?

Boodle currently offers repayment terms ranging from 1 to 6 months, depending on the loan option available to you.

How quickly does Boodle pay out?

Boodle states that its automated process can pay approved funds within around 10 minutes after a quotation has been accepted, while applications requiring manual handling may take longer. This is not a guaranteed payout time, as verification and banking processes can affect timing.

Can I get a Boodle loan with bad credit?

Boodle assesses applications on a case-by-case basis and carries out credit and affordability checks. A poor credit profile does not automatically determine the outcome, but Boodle states that applications may be declined where the applicant’s credit position or affordability does not support further borrowing.

Can I have more than one Boodle loan at a time?

No. Boodle currently states that customers can only have one Boodle loan at a time.

What happens if I miss a Boodle payment?

A missed repayment can negatively affect your credit profile and may result in additional charges. Boodle currently states that a default administration fee of R75 excluding VAT may apply while an account is in arrears. Contact Boodle as soon as possible if you are unable to make an agreed repayment.

How do I log in to my Boodle account?

Existing Boodle customers can sign in through Boodle’s official website. Boodle states that customers can return to an unfinished application by signing in and continuing where they left off. For security, only access your account through Boodle’s official website.

How do I contact Boodle?

Boodle currently provides customer support by telephone on 0861 266 353, WhatsApp on 081 713 8111 and email at [email protected]. Check Boodle’s official website for the latest contact details before sharing personal or financial information.

Sources & Verification

We checked the information in this Boodle Loans review against current lender information and South African consumer-credit sources. Key sources include:

Loan amounts, repayment terms, rates, fees, requirements, payout information and contact details were checked in September 2026. Product information can change. Always check Boodle’s latest information and review your individual quotation before accepting credit.

Editorial disclosure: This article is for general information only and does not constitute financial advice. FatCat Loans is a loan comparison service, not a lender. Boodle may not be one of the lenders available through our network. Loan amounts, rates, fees, repayment terms and eligibility can change and depend on the credit provider and your individual circumstances. Always check the lender’s latest information and review your pre-agreement statement and quotation before accepting credit.

Bayport Loans Review South Africa: Rates, Requirements & Pros (2026)

Looking for a Bayport loan in South Africa? Our expert review explains interest rates, fees, requirements, and whether Bayport is the right lender for you.

Bayport Loans Review South Africa

Updated April 2026

If you’re considering a Bayport loan in South Africa, it’s important to understand how the lender works before applying.

Bayport Financial Services is one of the country’s largest non-bank lenders. It offers unsecured personal loans designed primarily for salaried employees.

But is Bayport the right lender for you?

In this review, we cover everything you need to know about Bayport loans, including interest rates, requirements, fees, advantages, potential drawbacks, and safer borrowing alternatives.

This guide is designed to help South African borrowers make informed financial decisions—especially when taking on any form of debt.

This review is based on publicly available lender information, regulatory guidance, and independent research into South African personal loan providers.

Quick Verdict: Is Bayport a Good Lender?

Bayport Financial Services is a well-known non-bank lender in South Africa that provides unsecured personal loans primarily to salaried employees. The lender is registered with the National Credit Regulator (NCR) and operates under the National Credit Act, which helps protect borrowers through affordability checks and transparent loan terms.

Bayport may be a suitable option for borrowers who need accessible personal loans and have stable employment, particularly if they do not qualify for traditional bank financing. Loan amounts can reach up to R250,000, with repayment terms of up to 84 months.

However, because Bayport is a non-bank lender, interest rates and fees may be higher than those offered by traditional banks, especially for borrowers with strong credit profiles.

Before applying, it is recommended that borrowers compare multiple lenders, review the full repayment cost, and ensure the loan fits comfortably within their monthly budget.

Overall Rating: ★★★★☆ (4/5)

Best for:

  • Salaried borrowers
  • Applicants with stable employment
  • Borrowers seeking unsecured personal loans

What Is Bayport Financial Services?

Bayport Financial Services is a global financial services company founded in 2004, with a strong presence across South Africa and several emerging markets.

The company focuses primarily on unsecured lending, offering credit solutions to individuals who may not qualify for traditional bank loans.

Bayport’s lending model typically targets:

  • Salaried employees
  • Government workers
  • Teachers and healthcare professionals
  • Workers with stable employment but limited credit history

Unlike traditional banks, Bayport often provides loans through payroll-based repayment structures, where loan payments may be deducted directly from the borrower’s salary.

This model can make loan approvals easier for some borrowers but also requires careful financial planning.

Explore other personal loan options with FatCat Loans in South Africa.

Is Bayport a Legitimate Lender?

Yes, Bayport Financial Services is a legitimate and regulated credit provider in South Africa.

The company is registered with the National Credit Regulator (NCR) and must comply with the National Credit Act (NCA).

This regulation ensures lenders must:

  • Conduct affordability assessments
  • Provide transparent loan agreements
  • Disclose all fees and interest charges
  • Avoid reckless lending practices

Borrowers are legally protected under South African consumer credit laws, which help ensure fair treatment when applying for personal loans.

Before applying with any lender, it’s always advisable to verify their NCR registration to avoid scams or illegal lending operations.

What Types of Loans Does Bayport Offer?

Bayport primarily provides unsecured personal loans, meaning you do not need to provide collateral such as a vehicle or property.

These loans are commonly used for:

  • Debt consolidation
  • Home improvements
  • Medical expenses
  • Education costs
  • Emergency financial needs

Because these loans are unsecured, lenders rely heavily on a borrower’s income stability and affordability rather than assets.

Many borrowers use personal loans for debt consolidation, which involves combining multiple debts into a single monthly repayment.

Bayport Loan Amounts, Terms and Interest Rates

Bayport loan terms vary depending on your financial profile, employment stability and credit history.

Typical loan details include:

Loan Feature Details
Minimum Loan Approximately R1,000
Maximum Loan Up to R250,000
Repayment Terms 6 – 84 months
Loan Type Unsecured personal loan
Collateral Not required

Interest rates depend on credit risk and are regulated by the National Credit Act.

In general, borrowers may see:

  • Interest rates from roughly 11% to 28%
  • Annual percentage rates (APR) potentially reaching 30%+ depending on fees

Borrowers with stronger credit profiles or higher income may receive better loan terms.

Interest rates for personal loans in South Africa vary depending on credit risk, loan size and repayment term, so borrowers should always compare several lenders before applying.

Your credit profile plays an important role in determining the interest rate and loan amount you may qualify for.

The loan term refers to the length of time you have to repay the loan, which can affect both your monthly payment and total interest costs.

Bayport Loan Fees Explained

In addition to interest charges, borrowers should understand the additional costs associated with personal loans.

Common Bayport fees include:

Initiation Fee

A once-off loan initiation fee may be charged when the loan is approved. This fee can be up to approximately R1,200, depending on the loan size.

Monthly Service Fee

South African lenders may charge a monthly service fee, typically around R60–R69 per month.

Credit Life Insurance

Many lenders require credit life insurance, which protects the loan in case of death, disability or job loss.

While useful in some situations, this insurance also increases the total loan cost.

Late Payment Fees

Missing repayments may result in penalty charges and could negatively impact your credit score.

Understanding the total cost of borrowing, not just the interest rate, is essential when evaluating loan offers.

Borrowers should always consider the total cost of borrowing, including interest, fees and insurance charges.

Bayport Loan Requirements

To qualify for a Bayport personal loan, applicants typically must meet several basic criteria.

Basic Eligibility Requirements

Applicants usually must:

  • Be 18 years or older
  • Be a South African citizen
  • Have a valid South African ID
  • Be permanently employed
  • Earn a regular monthly income
  • Have an active bank account

Required Documents

Borrowers typically need to provide:

  • 3 months of payslips
  • 3 months of bank statements
  • Proof of residence
  • Valid identification

The lender will also conduct a credit check and affordability assessment before approving the loan.

These checks are required under the National Credit Act to prevent borrowers from taking on debt they cannot afford.

South African lenders are legally required to conduct an affordability assessment to ensure borrowers can reasonably repay the loan.

Lenders review your credit history to evaluate how reliably you have repaid previous loans or credit accounts.

How to Apply for a Bayport Loan

Applying for a Bayport loan can be done through several channels.

Borrowers may apply through:

  • The Bayport website
  • A mobile loan consultant
  • Bayport branch offices
  • Telephone applications

Typical Application Process

  1. Submit a loan application
  2. Provide income and identification documents
  3. Complete affordability assessment
  4. Receive loan offer
  5. Sign loan agreement
  6. Receive funds

Approval times vary depending on documentation and verification, but some borrowers may receive funding within a few days.

Advantages of Bayport Loans

Bayport offers several features that make it appealing for certain borrowers.

Accessible Lending

Bayport may approve applicants who struggle to qualify for traditional bank loans.

Larger Loan Amounts

Borrowers may qualify for loans up to R250,000, which is higher than many online lenders.

Flexible Repayment Terms

Loan terms of up to 84 months allow borrowers to spread repayments over longer periods.

No Collateral Required

Because the loans are unsecured, borrowers do not need to risk personal assets.

Potential Drawbacks of Bayport Loans

While Bayport offers accessible credit, there are also some potential disadvantages.

Higher Interest Rates

Non-bank lenders often charge higher interest rates than traditional banks.

Employment Requirements

Stable employment is typically required for approval.

Insurance Costs

Credit life insurance may increase the total loan repayment.

Payroll Deduction Structure

Salary-deducted repayments may reduce flexibility for some borrowers.

Understanding these limitations helps borrowers decide whether the lender is suitable for their financial situation.

Example Bayport Loan Repayment Cost

Understanding the real cost of borrowing is important before accepting any loan offer.

The example below shows how interest and fees can affect the total repayment amount over time.

Loan Amount Interest Rate Term Estimated Monthly Payment Total Repayment
R50,000 22% 48 months ~R1,560 ~R74,880

In this example, a R50,000 loan could result in a total repayment of approximately R74,880 over four years.

This means the borrower would pay nearly R25,000 in interest and fees over the loan term.

What affects your actual repayment?

Actual repayments may vary depending on:

  • your credit profile
  • the loan term
  • the interest rate offered
  • additional charges (such as service fees or credit life insurance)

Always review the full loan agreement and total repayment amount before accepting a loan.

Important to consider

Longer loan terms can reduce monthly repayments. However, they may increase the total amount of interest paid over time.

Bayport vs Traditional Bank Loans

When comparing lenders, it’s useful to understand how non-bank lenders like Bayport differ from traditional banks.

Feature Bayport Traditional Banks
Approval Speed Usually faster Often slower due to stricter checks
Credit Requirements Moderate Usually higher credit requirements
Loan Amount Up to R250,000 Often higher depending on income
Interest Rates Typically higher Usually lower for strong credit
Collateral Not required Sometimes required for larger loans

Non-bank lenders such as Bayport may offer more accessible credit, especially for borrowers who may not meet strict bank lending criteria. However, traditional banks often provide lower interest rates for borrowers with strong credit profiles.

For this reason, it is always recommended to compare several lenders before choosing a loan provider.

Bayport Customer Reviews and Reputation

Customer reviews for Bayport vary depending on individual experiences.

Positive feedback commonly mentions:

  • Helpful customer service
  • Straightforward application process
  • Accessible credit options

Negative reviews sometimes reference:

  • High borrowing costs
  • Strict repayment enforcement
  • Delays in loan processing

As with any financial product, borrower experiences can vary widely.

Reading independent reviews and comparing lenders is always recommended before applying.

Who Should Consider a Bayport Loan?

Bayport loans may be suitable for individuals who:

  • Have stable employment
  • Need unsecured personal credit
  • Want to consolidate existing debt
  • Do not qualify for bank loans

However, borrowers with strong credit profiles may qualify for lower interest rates with traditional banks or other lenders.

Who Should Avoid Bayport Loans?

While Bayport loans may be suitable for some borrowers, they may not be the best option for everyone. In certain situations, alternative lenders or financial solutions could provide better value.

You may want to consider other options if:

You Qualify for a Bank Loan

Traditional banks often offer lower interest rates for borrowers with strong credit histories and stable income. If you qualify for bank financing, you may be able to reduce the total cost of borrowing compared to many non-bank lenders.

You Already Have High Debt

If you already have significant existing debt, taking on another loan could increase financial pressure and make repayments difficult. In these situations, it may be better to focus on reducing existing debt before applying for additional credit.

You Need Very Short-Term Credit

Bayport loans are typically designed for medium to longer repayment periods. Borrowers who need short-term solutions may find alternative financial products more suitable.

You Are Struggling With Monthly Expenses

If your monthly budget is already tight, adding another loan repayment could create financial stress. Responsible lenders conduct affordability checks, but borrowers should also carefully assess their own financial situation before applying.

Understanding whether a loan fits your financial circumstances is an important part of responsible borrowing.

Bayport Loan Alternatives in South Africa

Before choosing any lender, it’s always wise to compare loan providers or explore a broader network of trusted lenders to find the best rates and repayment terms for your situation. While Bayport offers accessible unsecured loans, there are several other lending options available in South Africa.

Traditional Banks

Major banks such as Standard Bank, Absa, Nedbank and FNB offer personal loans with competitive interest rates for borrowers with strong credit histories.

Bank loans may provide:

  • Lower interest rates
  • Larger loan limits
  • Flexible repayment terms

However, approval requirements are often stricter, and the application process may take longer than with non-bank lenders.

Online and Non-Bank Lenders

Several online lenders and financial service providers also offer unsecured personal loans. These lenders often focus on faster approval times and simplified application processes.

Non-bank lenders may be suitable for borrowers who:

  • Need faster loan approvals
  • Have moderate credit histories
  • Prefer online applications

However, interest rates may be higher compared with traditional banks, so comparing offers carefully is important.

Credit Unions and Cooperative Financial Institutions

Credit unions and cooperative financial institutions sometimes provide personal loans with competitive rates and more flexible lending criteria.

These institutions may offer:

  • Lower fees
  • Community-focused lending
  • Personalised service

Availability depends on membership requirements and location.

Comparing Loan Options

Regardless of the lender you choose, always compare the following factors before applying:

  • Interest rates
  • Total repayment cost
  • Loan fees and service charges
  • Repayment terms
  • Customer reviews and lender reputation

Taking the time to compare loan options can help you find a lender that offers the most suitable terms for your financial needs.

Responsible Borrowing Tips

Personal loans can be useful financial tools, but they must be used responsibly.

Before applying, consider these important guidelines.

Borrow Only What You Need

Taking larger loans than necessary increases interest costs.

Compare Multiple Lenders

Loan rates and fees vary significantly across providers.

Understand Total Repayment Costs

Always calculate the total loan cost over the full repayment term.

Protect Your Credit Score

Making repayments on time helps build a strong credit history.

Responsible borrowing helps ensure loans remain helpful financial tools rather than long-term financial burdens.

Understanding loan affordability is essential to ensure that repayments fit comfortably within your monthly budget.

This article is for informational purposes only and should not be considered financial advice. Borrowers should carefully review loan terms and consult financial professionals if necessary before taking on new debt.

Final Verdict: Is Bayport a Good Lender?

Bayport Financial Services is a well-established and regulated lender in South Africa, offering unsecured personal loans to a wide range of borrowers.

The lender may be a good option for individuals who need accessible credit and have stable employment.

However, because interest rates and fees can vary, borrowers should always compare multiple lenders before making a final decision.

Carefully reviewing loan terms and understanding the total cost of borrowing will help ensure you choose the best financial option for your needs.

Explore other personal loan options with FatCat Loans in South Africa.

Common Questions About Bayport Loans

Is Bayport a registered lender in South Africa?

Yes. Bayport Financial Services is a registered credit provider regulated by the National Credit Regulator (NCR) in South Africa. This means the lender must comply with the National Credit Act, which requires affordability assessments, transparent loan agreements and responsible lending practices designed to protect borrowers.

How long does it take to get a Bayport loan?

Loan approval times vary depending on documentation and verification requirements. In many cases, applicants may receive a loan decision within a few hours to a few days after submitting the required documents and completing the affordability assessment.

What is the maximum loan amount from Bayport?

Bayport personal loans can reach up to approximately R250,000, depending on factors such as income, credit history, affordability and employment stability.

Does Bayport check your credit record?

Yes. Like all regulated lenders in South Africa, Bayport performs a credit check and affordability assessment before approving a loan. This helps determine whether the borrower can realistically repay the loan and what interest rate may apply.

Frequently Asked Questions

How much can I borrow from Bayport?

Bayport personal loans generally range from R1,000 to R250,000, depending on your affordability assessment and credit profile.

Is Bayport registered with the National Credit Regulator?

Yes. Bayport is a registered credit provider regulated by the National Credit Regulator (NCR) in South Africa.

How long does Bayport take to approve a loan?

Loan approvals may take from a few hours to several days, depending on documentation and verification requirements.

Can I repay a Bayport loan early?

Yes, South African lending regulations allow borrowers to settle loans early, although settlement amounts may vary depending on the agreement.

South Africa Public Holidays 2026: Dates & Long Weekends

South Africa Public Holidays 2026: Official Dates

Last Updated: September 2026

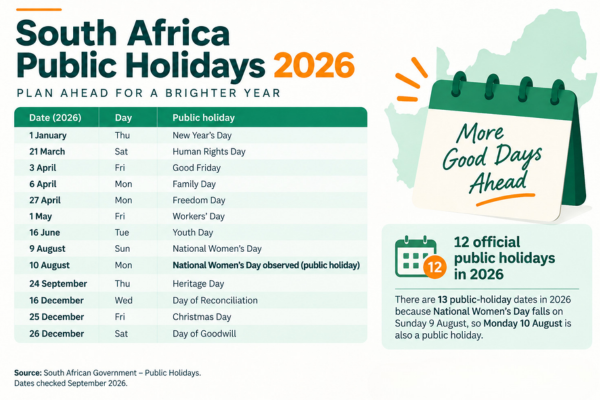
South Africa has 12 official public holidays in 2026, including Human Rights Day, Freedom Day, Workers’ Day, Youth Day, Heritage Day and the December holidays.

There are actually 13 public-holiday dates in 2026 because National Women’s Day falls on Sunday 9 August. Under the Public Holidays Act, when a public holiday falls on a Sunday, the following Monday is also a public holiday. This makes Monday 10 August 2026 a public holiday too.

Below you’ll find the complete South Africa public holidays 2026 calendar, plus the best long weekends, annual-leave opportunities, public-holiday pay rules and practical tips for planning your budget.

South Africa public holidays 2026 dates and calendar

Complete 2026 Public Holidays Calendar

The table below lists every official public-holiday date in South Africa for 2026, including Monday 10 August, which becomes a public holiday because National Women’s Day falls on a Sunday.

Date (2026) Day Public holiday
1 January Thu New Year’s Day
21 March Sat Human Rights Day
3 April Fri Good Friday
6 April Mon Family Day
27 April Mon Freedom Day
1 May Fri Workers’ Day
16 June Tue Youth Day
9 August Sun National Women’s Day
10 August Mon Additional public holiday – National Women’s Day
24 September Thu Heritage Day
16 December Wed Day of Reconciliation
25 December Fri Christmas Day
26 December Sat Day of Goodwill

Source: South African Government – Public Holidays. Dates checked September 2026.

Best Long Weekends in South Africa in 2026

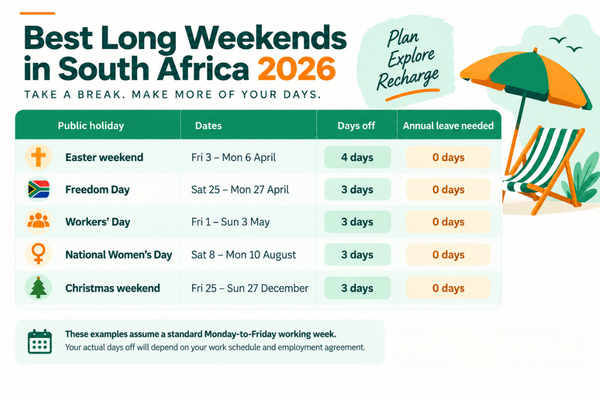
Several public holidays create long weekends in 2026 without needing to use annual leave. The examples below assume you normally work Monday to Friday.

Public holiday Dates Days off Annual leave needed
Easter weekend Friday 3 – Monday 6 April 4 days 0 days
Freedom Day Saturday 25 – Monday 27 April 3 days 0 days
Workers’ Day Friday 1 – Sunday 3 May 3 days 0 days
National Women’s Day Saturday 8 – Monday 10 August 3 days 0 days
Christmas weekend Friday 25 – Sunday 27 December 3 days 0 days

These examples assume a standard Monday-to-Friday working week. Your actual days off will depend on your work schedule.

Best Days to Take Annual Leave in 2026

If you want to stretch your annual leave further, some 2026 public holidays can be combined with weekends and a few leave days to create a longer break.

April and May: 9 Days Off Using 3 Leave Days

Freedom Day falls on Monday 27 April and Workers’ Day falls on Friday 1 May. If you normally work Monday to Friday, taking annual leave from Tuesday 28 April to Thursday 30 April gives you nine consecutive days away from work from Saturday 25 April to Sunday 3 May, using only three days of annual leave.

September: 4 days off using 1 leave day

Heritage Day falls on Thursday 24 September. Take Friday 25 September as annual leave and you can create a four-day break from Thursday to Sunday.

December: Extend the Christmas break

Christmas Day falls on Friday 25 December. Depending on your workplace schedule, taking leave in the days before or after Christmas can extend the festive break. Plan early, as December is a popular period for annual-leave requests.

Annual leave arrangements are subject to employer approval and your employment agreement.

Best long weekends in South Africa in 2026

What Happens When a Public Holiday Falls on a Weekend?

This is where people get caught out—especially around Sundays.

If a Public Holiday Falls on a Sunday

Under the Public Holidays Act, when a public holiday falls on a Sunday, the following Monday is also a public holiday.

In 2026, National Women’s Day falls on Sunday 9 August. This means Monday 10 August 2026 is also a public holiday.

If a Public Holiday Falls on a Saturday

There is no equivalent rule automatically making the following Monday a public holiday when a public holiday falls on a Saturday. How the holiday affects you will depend on your normal work schedule and employment arrangements.

Can a public holiday be moved?

The Public Holidays Act allows a public holiday to be exchanged for another day by agreement between employer and employee.
This matters for shift workers and industries that operate 24/7.

Public Holiday Pay in South Africa

Public-holiday pay is governed by Section 18 of the Basic Conditions of Employment Act (BCEA). The amount you should receive depends partly on whether the public holiday falls on a day you would ordinarily work.

If the Public Holiday Is a Day You Normally Work

If you do not work on the public holiday, you must generally be paid at least the wage you would ordinarily have received for working that day.

If you do work, the BCEA provides that you must be paid:

  • at least double the wage you would ordinarily have received for that day; or
  • if greater, your ordinary day’s wage plus the amount earned for the time worked on the public holiday.

If You Would Not Normally Work That Day

If you work on a public holiday that falls on a day you would not ordinarily work, Section 18 provides for payment equal to your ordinary daily wage plus the amount earned for the work performed on that day.

Can Your Employer Require You to Work on a Public Holiday?

Under the BCEA, an employer may not require an employee to work on a public holiday except in accordance with an agreement.

Employment contracts, collective agreements and individual circumstances can affect how these rules apply. This information is a general guide and is not legal advice. If you are unsure about your pay, check your employment agreement or seek advice from the Department of Employment and Labour.

How to Plan Your Budget Around Public Holidays

Long weekends and holiday periods can increase spending on travel, fuel, groceries, entertainment and family activities. Planning for these costs in advance can help you enjoy the break without putting unnecessary pressure on your normal monthly budget.

Set Aside a Holiday Spending Buffer

If you know you’ll be travelling or entertaining family, consider setting aside a small amount each month before the holiday. Even a modest buffer can help cover fuel, groceries and other additional costs.

Check Debit Orders and Repayment Dates

Public holidays can affect normal business and banking schedules. If you have upcoming debit orders or loan repayments, check when they are due and make sure enough money is available in your account.

Avoid Borrowing for Non-Essential Holiday Spending

A long weekend lasts only a few days, but debt can take months to repay. Where possible, avoid using credit for entertainment, travel or other non-essential holiday expenses if the repayments could put pressure on your budget afterwards.

If you’re considering borrowing for an essential expense, compare the total repayment cost before applying. You can use our loan repayment calculator to estimate repayments and understand the potential cost before making a decision.

Frequently Asked Questions About South Africa Public Holidays 2026

How many public holidays are there in South Africa in 2026?

South Africa has 12 official public holidays. However, there are 13 public-holiday dates in 2026 because National Women’s Day falls on Sunday 9 August, making Monday 10 August a public holiday as well.

What are the public holidays in South Africa in 2026?

The 2026 public holidays include New Year’s Day, Human Rights Day, Good Friday, Family Day, Freedom Day, Workers’ Day, Youth Day, National Women’s Day, Heritage Day, Day of Reconciliation, Christmas Day and Day of Goodwill. Monday 10 August is also a public holiday because National Women’s Day falls on a Sunday.

If a public holiday falls on a Sunday, is Monday a public holiday?

Yes. Under the Public Holidays Act, when a public holiday falls on a Sunday, the following Monday is also a public holiday.

Do we get Monday off if a public holiday falls on a Saturday?

Not automatically. The Public Holidays Act’s following-Monday rule applies when a public holiday falls on a Sunday, not a Saturday. Your normal work schedule and employment arrangements may affect how a Saturday public holiday applies to you.

Can my employer require me to work on a public holiday?

Under Section 18 of the BCEA, an employer may not require an employee to work on a public holiday except in accordance with an agreement.

How much should I be paid for working on a public holiday?

If the public holiday falls on a day you would ordinarily work, the BCEA generally requires at least double the wage you would ordinarily receive for that day, or your ordinary day’s wage plus the amount earned for the time worked if that amount is greater. Different rules apply when the public holiday falls on a day you would not ordinarily work.

Sources & Verification

This guide was reviewed against official South African government and employment-law sources, including:

Public-holiday dates and employment rules can be affected by legislative changes or official announcements. Information checked September 2026.

Unifi Loans Review South Africa (2026): Fees & Requirements

Unifi offers short-term instalment loans with fast payouts, but costs can be high once initiation, monthly fees and APR are included. Here’s how to compare safely.

Unifi Loans

Last Updated: September 2026

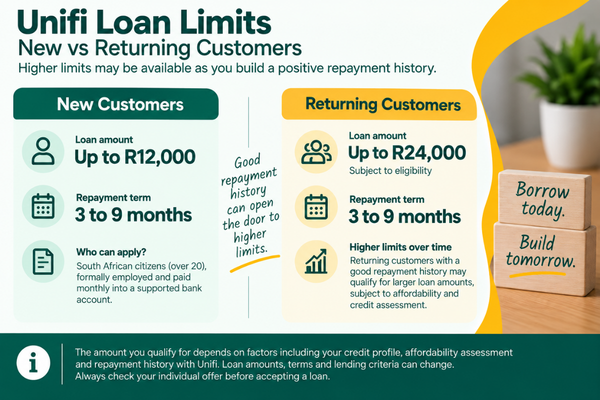
Unifi Credit is a South African online credit provider offering short-term loans with repayment terms of 3 to 9 months. New customers can currently apply for up to R12,000, while returning customers may qualify for up to R24,000.

This Unifi loans review covers loan amounts, repayment terms, fees, requirements, payout times, contact details and what to check before accepting an offer.

Unifi currently offers new customers loans of up to R12,000, with repayment terms from 3 to 9 months. Returning customers may qualify for higher limits of up to R24,000.

You can also explore other providers in the FatCat Loans lender network before choosing a loan.

Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.

Unifi Loans at a Glance

New customer loan amount Up to R12,000
Returning customer limit Up to R24,000, subject to eligibility
Repayment term 3 to 9 months
Application Online
Credit and affordability assessment Yes
Minimum age Over 20
Employment Formally employed and paid monthly
NCR registration NCRCP4849

The amount you qualify for depends on factors including affordability and your credit profile. Returning customers with a good repayment history may qualify for higher limits over time.

Unifi loan limits for new and returning customers

Is Unifi Legitimate and Registered in South Africa?

Yes. Unifi Credit (Pty) Ltd is a registered South African credit provider under the National Credit Act. Its current credit provider registration number is NCRCP4849.

Unifi’s current company information lists:

  • Company: Unifi Credit (Pty) Ltd
  • NCR registration: NCRCP4849
  • Company registration: 2010/019713/07

You can independently verify registered credit providers through the National Credit Regulator.

How Unifi Loans Work (Step-by-Step)

  1. Apply online and choose a loan amount and term.
  2. Verify income and banking (Unifi describes a “Superfast” option for automatic bank statement sharing, or manual uploads).
  3. Get a decision and, if approved, receive funds into the bank account where your salary is paid.
  4. Repay by instalments via debit order (and/or other payment options Unifi supports).

Unifi Loan Amounts and Repayment Terms

New Unifi customers can currently apply for loans of up to R12,000. Unifi states that returning customers may qualify for loans of up to R24,000, depending on factors such as affordability and credit history.

Repayment terms currently range from 3 to 9 months. Your approved amount, repayment term and monthly instalment will be shown before you accept the loan.

Who Can Apply for a Unifi Loan?

Unifi currently states that applicants must:

  • Be over 20 years old
  • Be a permanent South African citizen
  • Be formally employed
  • Earn a monthly salary
  • Have their salary paid into a supported bank account

Unifi currently supports ABSA, Standard Bank, FNB, Capitec, Nedbank, African Bank and TymeBank.

How Much Does a Unifi Loan Cost? (Fees + APR Explained)

Unifi’s website provides a transparent example that includes fees and APR — which is exactly what borrowers should look at.

Table 1: Unifi example pricing (as published)

Example Item Published Example What It Means
Loan amount R8,000 Your principal (amount borrowed)
Term 6 months Monthly instalments over the term
Monthly repayment R1,730 What leaves your account each month
Total repayment R10,344 Total you repay (principal + costs)
Initiation fee R995 Upfront fee added to total cost
Monthly fee R69 Monthly service/administration fee
Interest (monthly) 3% Interest rate shown as monthly interest
APR 95.9% (min) to 121.1% (max) The “all-in” annualised cost including fees

Unifi R8,000 loan repayment and fee example

Key takeaway: When loans are short-term and fee-heavy, the APR can look very high even if the rand cost is “manageable” month-to-month. The safest way to compare is to focus on total repayment and whether the instalments fit your budget.

How Fast Does Unifi Pay Out?

Unifi states payouts can happen within hours if you use its automated bank statement sharing (“Superfast”), and up to 24 hours if you upload documents manually.

If speed is your top priority, you can also compare same-day loan options to understand how payout timing can differ by lender and bank processing windows.

My Unifi Login: How to Access Your Account

Existing customers can access their account through My Unifi on the official Unifi website.

Through My Unifi, customers can check information such as their application status and account balance, upload required information and access account details.

Always access My Unifi through the official Unifi South Africa website rather than through links received from unknown sources.

Unifi Contact Details

Customer service 021 110 0600
Email [email protected]
Website unifi.credit/za/

Contact details checked against Unifi’s official website in September 2026. Contact information can change, so confirm the latest details directly with Unifi.

Unifi Repayments and DebiCheck

Unifi uses DebiCheck to authorise repayments. If a loan application is not approved, Unifi states that the DebiCheck mandate will be cancelled.

Unifi also explains that debit timing may change when a salary date falls on a public holiday or Monday. Borrowers should check the repayment dates shown in their loan agreement and contact Unifi if their salary timing changes.

If you are struggling to make a payment, contact Unifi as early as possible rather than ignoring a scheduled repayment.

Can I Get a Unifi Loan If I’m Blacklisted?

Unifi’s current FAQ states that people who are blacklisted can still apply. However, this does not guarantee approval. Unifi assesses factors including affordability and credit information before deciding whether to offer a loan and how much an applicant may qualify for.

Unifi also states that it does not currently assist customers who are under debt review or insolvent.

If poor credit is limiting your options, you can also read about bad credit loan options in South Africa.

Unifi Loan Scams and Fraud Warning

Loan scams can involve people pretending to represent legitimate lenders. Unifi states that it does not charge upfront fees. If someone claiming to represent Unifi asks you to pay a fee before your loan is released, treat this as a warning sign.

To help protect yourself:

  • Do not pay upfront fees: Unifi states that it does not charge upfront fees before providing a loan.
  • Use the official website: Apply or access My Unifi through the official Unifi website rather than links received from unknown sources.
  • Verify contact details: Unifi’s current customer-service number is 021 110 0600 and its customer-service email is [email protected].
  • Check NCR registration: Unifi Credit (Pty) Ltd is listed by Unifi as registered credit provider NCRCP4849. You can independently verify credit providers through the National Credit Regulator.
  • Be cautious with banking information: Do not send personal documents or banking information to unverified numbers, email addresses or social-media accounts.

If you suspect someone is impersonating Unifi or asking you to pay an upfront fee, contact Unifi directly on 021 110 0600 before sending money or personal information.

Final Thoughts

Unifi Credit offers short-term online loans to qualifying South African borrowers, with new customers currently able to apply for up to R12,000 and repayment terms from 3 to 9 months.

Before accepting an offer, check the monthly instalment, interest, fees, repayment dates and total amount repayable shown in your individual agreement. Approval, loan amounts and terms depend on Unifi’s affordability and credit assessment.

If you want to consider alternatives, FatCat Loans can help you compare loan options from multiple South African lenders before you apply.

Learn more about Unifi Loans South Africa review with FatCat Loans.

Frequently Asked Questions About Unifi Loans

How much can I borrow from Unifi?

New Unifi customers can currently apply for loans of up to R12,000. Unifi states that returning customers may qualify for higher limits of up to R24,000. The amount you qualify for depends on factors including your credit profile and affordability assessment.

How long do I have to repay a Unifi loan?

Unifi currently offers repayment terms ranging from 3 to 9 months. Your individual loan agreement will show your repayment term, monthly instalment and total amount repayable before you accept the loan.

What are the requirements for a Unifi loan?

Unifi currently states that applicants must be over 20 years old, be a permanent South African citizen, be formally employed and earn a monthly salary paid into a supported bank account. Supported banks currently include ABSA, Standard Bank, FNB, Capitec, Nedbank, African Bank and TymeBank.

How do I log in to My Unifi?

Existing customers can access their account through My Unifi on the official Unifi website. My Unifi can be used to check your application status and account balance, upload information and access account details such as statements and settlement quotes.

What are the Unifi contact details?

You can contact Unifi South Africa on 021 110 0600 or email [email protected]. Always confirm contact details through the official Unifi website before sharing personal or banking information.

How fast does Unifi pay out?

Unifi states that customers using its Superfast automatic bank-statement sharing option may receive approved funds within a few hours. If documents are uploaded or emailed manually, the process can take up to 24 hours. Actual timing can still depend on the application and banking process.

Can I apply for a Unifi loan if I’m blacklisted?

Yes. Unifi’s current FAQ states that people who are blacklisted can still apply. This does not guarantee approval, as the amount offered depends on factors including affordability and credit information. Unifi also states that it does not currently assist customers who are under debt review or insolvent.

Is Unifi registered with the NCR?

Yes. Unifi Credit (Pty) Ltd lists its National Credit Regulator registration as NCRCP4849. Its company registration number is 2010/019713/07. Borrowers can independently check credit-provider registrations through the National Credit Regulator.

Sources & Verification

We checked the information in this Unifi loans review against current Unifi information and South African consumer-credit sources. Key sources include:

Loan amounts, repayment terms, fees, eligibility information, contact details and other product information were checked in September 2026. Credit products and lending criteria can change. Always check your individual quotation and Unifi’s official website before accepting a credit agreement.

Capfin Loans Review: Rates, Fees, Eligibility, Risks & Analysis

Comprehensive Capfin personal loan review covering loan limits, regulated fees, repayment terms, credit impact and expert borrowing guidance.

Capfin Personal Loan Review

Last Updated:  September 2026

Reviewed by: FatCat Loans South Africa Editorial Team

Regulatory Status: Capfin is registered with the National Credit Regulator (NCRCP13053).

This guide is informational only and does not constitute financial advice. Always review your full pre-agreement statement and credit agreement before accepting any loan.

How We Evaluate Personal Loan Providers

Our reviews are based on publicly available information, regulatory disclosures, and standardised comparison criteria.

When assessing lenders like Capfin, we evaluate:

  • Regulatory registration and compliance under the National Credit Act
  • Transparency of fees and total cost disclosure
  • Loan structure and repayment flexibility
  • Credit impact and affordability safeguards
  • Suitability for different borrower profiles

We do not rank lenders based on approval speed alone.

Our focus is long-term affordability, sustainability, and regulatory compliance.

Executive Summary

Capfin is one of South Africa’s most recognised unsecured personal loan providers.

Capfin currently offers personal loans from R1,000 up to R50,000, with repayment terms of 6, 12 or 24 months, subject to its credit application and affordability assessment.

Unlike payday lenders that require lump-sum repayment within 30–49 days, Capfin provides structured monthly instalment loans.

That structural difference reduces immediate repayment pressure but increases total interest exposure over time.

Capfin may suit borrowers who:

  • Need more than R8,000
  • Prefer predictable monthly repayments
  • Have stable employment income
  • Want structured medium-term credit

However, total cost includes:

  • Risk-based interest
  • Initiation fee
  • Monthly service fee
  • VAT on applicable fees
  • Capfin Credit Life, where applicable

If you are evaluating structured unsecured credit, you can compare regulated options in our personal loans hub.

Who Is Capfin?

Capfin is a division of Pepkor Trading (Pty) Ltd and operates as a registered credit provider under South Africa’s National Credit Act (NCA), with NCR registration NCRCP13053.

It forms part of the Pepkor group and distributes loans through:

  • Online digital channels
  • SMS application processes
  • PEP retail stores
  • Ackermans retail stores

This hybrid retail-digital structure provides nationwide accessibility, including for borrowers without consistent internet access.

Capfin specialises in unsecured personal loans. This means:

  • No collateral is required
  • Approval depends on credit and affordability
  • Interest rates are typically higher than secured loans
  • Repayment is structured in fixed monthly instalments

Understanding this product category is important before evaluating suitability.

Learn more about other loan options with FatCat Loans.

Capfin Loan Details at a Glance

Feature Details
Loan Amount R1,000 – R50,000
Repayment Term 6, 12 or 24 months
Interest Fixed rate based on your application and risk profile
Initiation Fee Applies; disclosed in your quotation
Monthly Service Fee Up to R69 incl. VAT in Capfin’s current examples
Credit Life Cost included in Capfin’s published repayment examples

Capfin personal loan amounts, terms, fees and requirements

How Capfin Personal Loans Work

Step 1: Application

Applicants must provide:

  • Valid South African ID
  • Active bank account in their name
  • Proof of income
  • Recent bank statements (typically 3 months)

Applications can be completed online or in-store.

Step 2: Affordability & Credit Assessment

Under the National Credit Act, lenders must assess:

  • Income vs expenses
  • Existing debt commitments
  • Credit bureau profile
  • Bank account behaviour

Approval depends on affordability, not just credit score.

If your debt-to-income ratio is too high, you may be declined.

Step 3: Pre-Agreement Disclosure

Before accepting the loan, Capfin must provide a pre-agreement statement outlining:

  • Loan amount
  • Interest rate
  • Initiation fee
  • Monthly service fee
  • Total cost of credit
  • Monthly instalment
  • Repayment schedule

This document is legally required.

Never accept credit without reviewing total repayment in rand.

Capfin Loan Topup: Can Existing Customers Borrow More?

If you’re searching for a Capfin loan topup, it’s important to understand that additional borrowing is not automatically available simply because you already have a Capfin loan.

Capfin’s current loan terms refer to new loans being granted to existing customers. However, any new loan remains subject to Capfin’s approval process and your current financial circumstances.

This means your affordability, income, existing commitments and credit profile may be reassessed before additional credit is offered.

Existing customers can use Capfin’s self-service tools to access and manage their loan account and check the options currently available to them.

A previous Capfin approval does not guarantee another loan or a higher loan amount. If you’re offered additional credit, check the interest rate, fees, repayment term, monthly instalment and total repayment before accepting it.

How Capfin Loan Interest and Fees Work

Personal loans fall under regulated unsecured credit categories under the NCA.

Capfin’s total cost of credit may include:

Capfin Interest Rates

Capfin uses fixed interest rates, with the rate offered depending on factors such as your loan term, credit profile, affordability and risk assessment.

Capfin’s current website advertises fixed interest rates of between 5% and 28% per annum for loans repayable over 6 to 24 months. However, Capfin also publishes different maximum-rate examples for particular loan structures, so the rate that matters is the one shown in your own pre-agreement statement and quotation.

Your interest rate is fixed for the duration of the credit agreement and interest is calculated on the daily outstanding balance and capitalised monthly.

Always check your personalised interest rate and total repayment before accepting the loan.

Initiation Fee

A once-off fee charged when the loan is granted.

This fee is capped by regulation but increases total repayment.

Monthly Service Fee

Capfin’s current published examples include a maximum monthly service fee of R69, inclusive of VAT. Because this fee is charged monthly, it contributes to the overall cost of borrowing over the loan term.

VAT

VAT applies to applicable fees (not interest).

Borrowers often underestimate how VAT increases total repayment.

How Personal Loan Pricing Is Regulated in South Africa

Understanding how Capfin structures its pricing requires understanding the National Credit Act (NCA). Many review sites mention “regulated” but do not explain what that actually means.

The National Credit Act was introduced to promote responsible lending and prevent reckless credit extension in South Africa.

Under the NCA, unsecured personal loans fall into a specific pricing category. Lenders may legally charge:

  • Interest (subject to maximum caps depending on category)
  • An initiation fee (once-off)
  • A monthly service fee
  • VAT on applicable fees

These are not arbitrary.

They are legally defined components of “Total Cost of Credit.”

Interest Rate Caps

For unsecured personal loans, the maximum interest rate is determined by regulatory formulas linked to the repo rate and prescribed caps.

This means:

  • Interest cannot exceed a legal maximum.
  • Risk-based pricing is permitted within those limits.
  • Higher-risk borrowers may receive higher rates (but still within caps).

Regulation protects against unlimited interest — but it does not guarantee low-cost credit.

Initiation Fee Structure

The initiation fee is a once-off cost charged when the loan is granted.

Under the NCA, this fee is capped and structured according to loan size.

Example structure (illustrative):

  • Base fee + percentage of loan amount (subject to cap)
  • VAT applied

For larger loans (e.g., R50,000), the initiation fee can meaningfully increase total repayment — even though it is charged once.

Monthly Service Fee Cap

The NCA allows lenders to charge a regulated monthly service fee.

This fee:

  • Applies regardless of interest rate
  • Is capped
  • Continues throughout the loan term
  • Has VAT applied

Monthly service fees contribute to the total cost throughout the repayment period, so check the service fee shown in your own quotation rather than looking at the interest rate alone.

Borrowers often underestimate this cost component.

Early Settlement Rights

Under the National Credit Act:

You have the right to settle your loan early.

If you repay early:

  • Future interest must be reduced proportionally.
  • Certain costs may decrease.
  • You cannot be penalised unfairly.

This right exists even if not heavily marketed.

Affordability Assessments

The NCA requires lenders to assess:

  • Gross income
  • Net disposable income
  • Existing obligations
  • Living expenses

If a lender grants credit recklessly without proper assessment, that may constitute “reckless lending.”

However, approval does not mean the loan is affordable for your lifestyle.

Borrowers remain responsible for evaluating sustainability.

Capfin Loan Repayment Example

Capfin currently provides the following representative example on its website for a R4,000 loan over 12 months:

  • Loan amount: R4,000
  • Repayment term: 12 months
  • Maximum interest rate: 28% per annum
  • Initiation fee: R535
  • Monthly service fee: R69
  • Maximum monthly instalment: R516
  • Maximum total repayment: R6,190

Capfin states that the example includes its Credit Life cover and VAT where applicable.

Your own repayment amount may be different. The amount you qualify for, interest rate and repayment terms depend on your application and affordability assessment.

Capfin vs Other Loan Types

Feature Capfin Payday Loan Bank Loan
Max Loan ± R50k < R8k Higher
Term 6–24 months 30–49 days 12–60 months
Repayment Monthly Lump sum Monthly
Interest Higher than banks High short-term Lower
Approval Moderate Fast Slower

Capfin occupies the mid-market unsecured lending segment in South Africa. It offers larger loan amounts and structured instalments compared to payday lenders, but generally at higher cost than traditional bank personal loans.

To compare Capfin against a wider range of regulated providers, you can also review FatCat Loans’ lender network before applying.

That positioning makes it suitable for borrowers who may not qualify for bank credit but need more structured repayment than short-term microloans provide.

Understanding the True Cost of a Capfin Loan

Most borrowers focus on:

“What is the interest rate?”

But that is the wrong question.

The correct question is:

“What is my total repayment amount, and can I comfortably afford the instalment?”

Let’s break this down more clearly.

Why Longer Terms Increase Total Cost

A 24-month loan:

  • Lowers monthly instalment
  • Increases total interest exposure

A 12-month loan:

  • Raises monthly instalment
  • Reduces total interest paid

Borrowers often choose longer terms for comfort — but pay more overall.

This trade-off should be understood before signing.
Tips for managing a Capfin personal loan responsibly

APR vs Real-World Cost

APR (Annual Percentage Rate) can look high.

But what matters most is:

  • Instalment amount
  • Total repayment
  • Cash flow impact

Percentages don’t pay loans. Monthly cash flow does.

Debt Consolidation Considerations

Some borrowers use Capfin to consolidate smaller microloans.

Potential benefits:

  • One structured instalment
  • Simplified repayment
  • Reduced default risk

Risks:

  • Total interest may increase
  • Extended repayment period
  • Possible new debt accumulation

Always calculate total cost before consolidating.

Credit Score Impact Analysis

On-Time Repayment

  • Builds positive repayment history
  • Improves credit behaviour record
  • Demonstrates instalment discipline

Missed Payments

  • Bureau listing
  • Reduced future approval probability
  • Potential collections
  • Legal escalation

Your credit behaviour affects long-term borrowing power.

Repayment behaviour may be reported to major South African credit bureaus such as TransUnion, Experian or Compuscan, depending on the lender’s reporting arrangements.

What Happens If You Miss a Payment?

  • Debit order failure
  • Bank penalty fees
  • Default interest
  • Collections activity
  • Credit bureau listing
  • Possible legal action

Contact the lender before missing payments.

The Hidden Risk of Instalment Credit

Instalment loans feel safer than payday loans because:

  • Payments are smaller
  • Repayment is structured
  • Approval feels manageable

However, instalment loans carry a different risk:

They create long-term financial commitment.

If your income changes, your obligation remains.

Common Risk Patterns

  1. Borrowing for lifestyle expenses instead of emergencies
  2. Using new loans to repay older ones
  3. Extending terms repeatedly
  4. Overestimating monthly surplus

Capfin’s structure reduces lump-sum shock but increases long-term exposure.

Debt Consolidation Trap

While consolidation may simplify payments, it can:

  • Extend repayment period
  • Increase total interest paid
  • Encourage new borrowing behaviour

Consolidation is helpful only if spending behaviour changes.

Borrower Profiles

Stable Income Borrower

Regular salary, clear surplus.
Capfin may be manageable.

Debt Consolidator

Multiple microloans.
Must compare total cost carefully.

Overextended Borrower

High debt ratio.
May be declined under affordability rules.

When Capfin May Be Suitable

✔ Need structured instalment
✔ Moderate loan size
✔ Predictable income
✔ Clear repayment plan

When to Consider Alternatives

✖ Already financially strained
✖ Seeking lowest interest possible
✖ Using credit to cover essentials
✖ Planning repeat borrowing

In these situations, it may be worth reviewing other regulated personal loan options with different repayment structures and eligibility criteria.

Responsible Borrowing Framework

Before signing:

  • Review total repayment
  • Stress-test your budget
  • Factor inflation & expenses
  • Avoid overlapping credit
  • Confirm early settlement terms

Learn more about other loan options with FatCat Loans.

Frequently Asked Questions

Is Capfin registered with the NCR?

Yes. Capfin, a division of Pepkor Trading (Pty) Ltd, is registered with the National Credit Regulator under NCRCP13053. As a registered credit provider, Capfin must comply with South Africa’s National Credit Act and applicable credit regulations. Registration does not mean a loan is automatically affordable, so always review the costs and repayment terms before accepting credit.
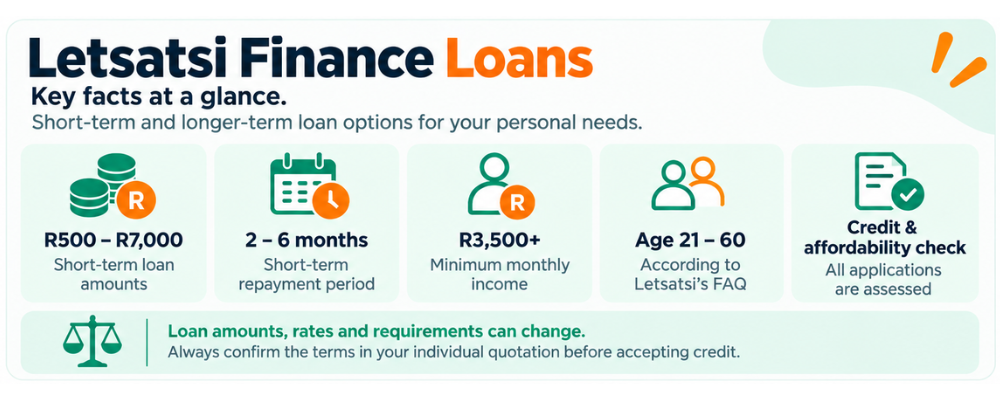
How much can I borrow from Capfin?

Capfin typically offers unsecured personal loans ranging from approximately R1,000 up to R50,000. The exact amount you qualify for depends on your income, existing debt obligations, credit bureau profile and overall affordability assessment. First-time borrowers or applicants with higher risk profiles may qualify for lower limits, while established borrowers with stable income may access higher amounts.

What repayment terms does Capfin offer?

Repayment terms usually range between 6 and 24 months. Your approved term depends on the loan amount and your affordability profile. Shorter terms increase your monthly instalment but reduce total interest paid. Longer terms lower your monthly payment but increase the total cost of credit over time. Always review the full repayment schedule before accepting.

Does Capfin perform credit checks?

Yes. Capfin is legally required to perform affordability and credit bureau checks before granting a loan. This includes reviewing your credit profile, income level, existing debt commitments and recent bank statement activity. Approval is based on whether the loan fits within your verified affordability — not just your credit score alone.

Can I repay my Capfin loan early?

Yes. Under the National Credit Act, you have the right to settle your loan early. Early repayment may reduce the amount of future interest charged, although certain fees may still apply depending on the structure of your agreement. If you are considering early settlement, request a formal settlement quote to understand the updated total amount payable.

Are Capfin’s fees disclosed upfront?

Yes. Before accepting the loan, you must receive a pre-agreement statement outlining the total cost of credit. This includes the interest rate, initiation fee, monthly service fee, VAT (where applicable), total repayment amount and instalment schedule. You should never accept a loan without reviewing this documentation carefully.

How fast does Capfin pay out funds?

Capfin states that approved loans are paid into the nominated bank account within 48 business hours after approval. A delay in approving the DebiCheck mandate request from your bank may delay the transfer of the funds.

Can self-employed individuals apply?

Yes, self-employed applicants may apply, provided they can demonstrate consistent income through bank statements or supporting documentation. Because income variability can affect affordability calculations, approval decisions may depend heavily on documented financial stability.

Does Capfin offer debt consolidation loans?

Capfin loans can be used for debt consolidation purposes. Some borrowers choose to combine multiple smaller loans into one fixed instalment. However, consolidation should be evaluated carefully, as extending repayment over a longer period may increase total interest paid. Always compare total repayment before consolidating.

Will applying for a Capfin loan affect my credit score?

Submitting an application may result in a credit inquiry being recorded with credit bureaus. While a single inquiry typically has limited impact, multiple loan applications within a short period may affect your credit profile. Responsible borrowing and on-time repayment are more influential over the long term.

What documents are required to apply?

Applicants typically need a valid South African ID, proof of income (such as payslips), recent bank statements (often three months) and an active bank account in their name. Additional documentation may be requested depending on your employment status or financial profile.

Can I get a Capfin loan topup?

Existing Capfin customers may be able to apply for additional credit, but a Capfin loan topup is not automatically guaranteed. Capfin’s current terms refer to new loans being granted to existing customers, with approval remaining subject to the lender’s assessment. Your current income, affordability, existing commitments and credit profile may be considered before further credit is offered. Always review the costs and repayment terms of any new loan before accepting it.

What happens if I lose my job during repayment?

If your income changes, contact Capfin immediately to discuss your situation. Ignoring repayments can lead to collections activity and credit bureau listing. Early communication may allow discussion of possible arrangements, although approval of any accommodation is not guaranteed.

Is Capfin cheaper than payday lenders?

Capfin’s instalment structure generally reduces short-term repayment pressure compared to payday loans, which require lump-sum repayment. However, because Capfin loans extend over several months, total interest paid may still be significant. The “cheaper” option depends on your loan size, term and repayment ability.

How can I compare Capfin properly with other lenders?

The best way to evaluate Capfin is by comparing total repayment amounts, monthly instalments, eligibility requirements and term flexibility against other regulated providers.

Focus on affordability and sustainability — not just speed of approval.

Capfin vs African Bank

African Bank typically offers:

  • Longer repayment terms (up to 60 months)
  • Potentially lower interest rates
  • Stricter credit requirements

Capfin:

  • Faster application
  • Retail accessibility
  • Shorter maximum terms

African Bank typically caters to borrowers with stronger credit profiles and may offer longer repayment terms of up to 60 months. While this can reduce monthly instalments, extended terms also increase total interest exposure. Approval criteria may be stricter, and application processes may take longer compared to Capfin’s retail-assisted model.

Capfin vs Letsatsi Finance

Letsatsi Finance:

  • Often smaller loan amounts
  • May serve lower-income segments

Capfin:

  • Higher maximum limits
  • Broader retail distribution

Capfin vs Payday Lenders

Payday lenders:

  • Lump-sum repayment
  • Short term (30–49 days)
  • High short-term cost pressure

Capfin:

  • Instalment structure
  • Larger amounts
  • Longer commitment

The most significant structural difference lies in repayment mechanics. Payday lenders require full repayment within a single pay cycle, creating higher immediate cash flow pressure. Capfin’s instalment model distributes repayment across multiple months, reducing short-term strain but increasing long-term interest exposure.

The decision between the two depends less on approval speed and more on cash flow sustainability.

Practical Example: Is a Capfin Loan Affordable?

Consider a borrower earning R18,000 net per month.

Existing expenses and obligations total R14,500.
This leaves a monthly surplus of R3,500.

If this borrower takes a R30,000 loan over 24 months at an estimated instalment of R2,100 per month:

New monthly surplus becomes R1,400.

This may appear manageable initially. However, any unexpected expense — medical, transport, inflation — could quickly eliminate that buffer.

This example illustrates why affordability is not about whether you can qualify, but whether you can absorb financial variability over the full repayment term.

Final Expert Verdict

Capfin is a legitimate, NCR-regulated personal loan provider offering unsecured credit with structured monthly repayments and loan amounts up to R50,000.

It operates within South Africa’s regulated unsecured lending framework and provides medium-term credit with predictable instalments.

Its core strength is accessibility combined with predictable repayments.

For borrowers with stable income who need medium-term funding and can comfortably afford the monthly instalment, Capfin can be a structured alternative to high-pressure payday lending.

However, this is not low-cost credit.

Over 12 to 24 months, interest, initiation fees, and service fees can significantly increase the total repayment amount.

Longer terms reduce monthly pressure but increase total interest exposure. This trade-off should be clearly understood before signing.

Capfin is most suitable when:

  • The expense is necessary, not discretionary
  • Your income is stable and verified
  • The instalment fits comfortably within your monthly budget
  • You are not using new credit to service existing debt

It may not be suitable if:

  • You are already financially stretched
  • You are managing multiple loans
  • You are borrowing to cover recurring monthly shortfalls

The most important decision is not whether you can get approved — but whether the repayment remains sustainable across the full loan term.

Structured credit can be useful when used deliberately and within verified affordability limits.

However, unsecured personal loans should always be evaluated against long-term financial stability, not short-term urgency.

The most financially sound decision is one that remains sustainable — not just this month, but across the full term of the agreement.

Sunshine Loans South Africa Review: Fees, Legal Costs & Risks

Thinking of applying for Sunshine Loans? Read our 2026 expert review covering fees, legal costs under the NCA, repayment risks, comparisons and safer alternatives first.

Sunshine Loans South Africa Review

Published February 2026 | Last reviewed September 2026

Reviewed by: FatCat Loans South Africa Editorial Team

Regulatory Status: Sunshine Loans is registered with the National Credit Regulator (NCRCP14110).
Company: MoneySpot Finance SA (Pty) Ltd, trading as Sunshine Loans.

This guide is informational only and not financial advice. Always review your loan agreement carefully before accepting credit.

Executive Summary

Sunshine Loans is a South African short-term credit provider offering loans from R500 to R4,000, repayable over 4 to 49 days.

It is:

  • Fully online
  • NCR registered
  • Designed for short-term emergency borrowing

However, the short repayment period can place considerably more pressure on your budget than a longer-term instalment loan. Check your quotation carefully to confirm whether your approved loan will be collected in one payment or more than one instalment.

If you need more than R4,000, longer than 49 days to repay, or lower monthly repayment pressure, structured options like instalment loans may be worth comparing first.

Compare instalment loan options with FatCat Loans

Who Is Sunshine Loans?

Sunshine Loans operates as a short-term credit provider under South Africa’s National Credit Act (NCA). Their product is designed for small, urgent cash needs such as:

  • Emergency car repairs
  • Medical co-payments
  • School fees
  • Utility shortfalls
  • Temporary cash gaps before payday

They are not a long-term financing solution.

Loan Details at a Glance

Feature Details
Loan Amount R500 – R4,000
Repayment Term 4 – 49 days
Application Online
Credit Check Yes (affordability required)
Funding Speed Sunshine says funding can take place within one business day, subject to approval and bank processing times
Regulation National Credit Regulator

Sunshine Loans amounts, terms and NCR registration

How Sunshine Loans Works

Step 1: Online Application

You complete a digital application including:

  • South African ID
  • Bank account details
  • Income information
  • Recent bank statements

Step 2: Affordability & Credit Check

Under the National Credit Act, lenders must perform affordability assessments. Sunshine Loans checks:

  • Income stability
  • Recent transaction behaviour
  • Credit bureau data
  • Existing obligations

Step 3: Approval Decision

If approved, you receive a pre-contract statement outlining:

  • Loan amount
  • Initiation fee
  • Service fee
  • Interest
  • Total repayment
  • Repayment date

Step 4: Payout

If an application is approved and the agreement is completed, Sunshine Loans says funding may take place by the end of the business day. The actual arrival time can depend on when the application is approved and the receiving bank’s processing times.

Sunshine Loans online application and approval process

How Sunshine Loans Costs Are Regulated in South Africa (NCA + NCR)

Before looking at repayment examples, it’s important to understand how short-term loan pricing works in South Africa.

Sunshine Loans, like all registered credit providers, must comply with the National Credit Act (NCA) and is overseen by the National Credit Regulator (NCR).

This legislation regulates how lenders structure fees, interest, and total repayment amounts.

However, “regulated” does not mean “low cost.” It means the pricing components are legally defined and capped.

Understanding these components helps you:

  • Identify what you’re being charged for
  • Compare lenders accurately
  • Avoid unexpected costs
  • Evaluate whether the loan fits your budget

1️⃣ Initiation Fee (Once-Off Charge)

For short-term credit agreements, lenders are allowed to charge a once-off initiation fee when the loan is granted.

This fee:

  • Is capped under the NCA
  • Is charged once per agreement
  • Is separate from interest
  • May have VAT applied

Even on smaller loans (for example, R1,000), this fixed fee represents a meaningful percentage of the amount borrowed.

It is not refunded after the loan is disbursed.

2️⃣ Monthly Service Fee

Lenders may also charge a monthly service fee for administering the account.

This fee:

  • Is capped under the NCA
  • May apply even if the loan term is only 30 days
  • Is separate from interest
  • May have VAT applied

For short-term loans, this service fee can make up a noticeable portion of the total repayment.

3️⃣ Interest on Short-Term Loans

Short-term loans have regulated interest caps under South African law.

Interest:

  • Is calculated on the principal amount
  • Is applied according to the loan category
  • Is disclosed before acceptance

Because these loans are short-term (often under 49 days), the cost may look high relative to the amount borrowed. This is due to the compressed repayment period.

The key number to focus on is not the percentage rate — it is the total repayment amount in rand.

4️⃣ VAT on Certain Fees

VAT (Value Added Tax) may be applied to:

  • Initiation fees
  • Service fees

It is generally not applied to the interest portion itself.

Many borrowers forget to factor VAT into the final total, which can make the repayment amount higher than expected.

5️⃣ Pre-Agreement Disclosure Requirements

Before you accept the loan, the lender must legally provide:

  • A pre-agreement statement
  • A quotation
  • Full breakdown of fees
  • Total repayment amount
  • Repayment date

You should never accept a loan without reviewing this documentation carefully.

If anything is unclear, request clarification before signing.

6️⃣ Early Settlement Rights

Under the National Credit Act, borrowers have the right to settle their loan early.

If you repay early:

  • Interest should be reduced proportionally
  • The total cost of credit may decrease

This right exists whether or not it is heavily advertised.

7️⃣ What Regulation Does NOT Protect You From

While pricing is regulated, the law does not protect you from:

  • Borrowing more than you can comfortably repay
  • Cash flow pressure from a short repayment schedule
  • Repeated short-term borrowing cycles
  • Multiple simultaneous short-term loans

Affordability assessments reduce risk, but they do not eliminate it.

You remain responsible for evaluating whether the loan is sustainable within your monthly budget.

Understanding this regulatory structure makes the next section — where we break down real repayment examples — much easier to evaluate.

Now let’s look at what Sunshine Loans may actually cost in practice.

The Real Cost of Sunshine Loans (Detailed Breakdown)

Under the National Credit Act, short-term loans may include:

  • Initiation fee (capped)
  • Service fee
  • Interest (monthly rate limit applies)
  • VAT on applicable fees

Sunshine Loans Repayment Example

Sunshine Loans currently provides the following representative example on its official website:

  • Amount borrowed: R2,800
  • Repayment period: 27 days
  • Interest and fees: R607.63
  • Total repayment: R3,407.63

This example is provided for general guidance and may not represent the terms offered to you. Your actual cost will depend on the amount borrowed, repayment period, whether you have borrowed before and the terms contained in your quotation.

Before accepting a loan, check the pre-agreement statement for the exact interest, fees, repayment dates and total amount repayable.

Why Payday Loans Feel Affordable (But Aren’t)

Short-term loans feel manageable because:

  • The amount is small
  • The term is short
  • Approval is quick

Because the repayment period is short, one or more repayments may fall within the next few pay cycles. Depending on the terms offered, this can create:

  • Cash flow shock
  • Next-month shortage
  • Repeat borrowing cycle

For borrowers who need more breathing room, comparing flexible online loan options may provide better repayment structure.

Sunshine Loans vs Other South African Short-Term Lenders (Detailed Comparison)

Many short-term lenders in South Africa operate under the same National Credit Act caps. That means the legal maximum fees and interest structures are similar across providers.

However, the real differences typically appear in:

  • Approval strictness
  • Maximum loan limits
  • Customer experience
  • Repeat borrowing policies
  • Transparency
  • Flexibility during financial hardship

Below is a deeper breakdown comparing Sunshine Loans with common competitors such as Wonga, Boodle, and Lime Loans.

You can also review FatCat Loans’ lender network to compare Sunshine Loans with a wider range of regulated providers before applying.

1️⃣ Loan Amount Limits

Lender Maximum Loan
Sunshine Loans R4,000
Wonga SA R3,000
Boodle Up to R5,000 for new customers and R8,000 for existing customers
Lime Loans R4,500

What This Means

  • If you need R3,000 or less, most lenders are viable.
  • If you need above R4,000, Sunshine Loans may not meet your requirement.
  • Boodle may suit borrowers needing slightly higher short-term limits.

However, remember:
Higher loan limits also mean higher total repayment pressure.

2️⃣ Repayment Term Comparison

Repayment terms differ between providers. Sunshine Loans offers terms of 4 to 49 days, while some competing lenders now provide longer repayment periods.

Lender Maximum Term
Sunshine Loans 49 days
Wonga SA 49 days
Boodle 1–6 months
Lime Loans 49 days

When comparing repayment periods, the key question is:

Can you afford every scheduled repayment without falling short on essential expenses?

If not, a longer-term product may be safer than switching between short-term lenders.

3️⃣ Approval Criteria & Affordability Checks

All NCR-registered lenders must conduct affordability assessments.

However, approval models vary.

Sunshine Loans

  • Reviews income stability
  • Assesses recent bank transaction behaviour
  • Evaluates existing obligations

Wonga SA

  • Automated digital credit decisioning
  • Strong reliance on internal risk scoring

Boodle

  • May approve slightly higher limits for repeat borrowers

Lime Loans

  • Focuses on short-term affordability windows

Important:

No reputable lender guarantees approval.
If any lender claims “100% guaranteed approval,” treat that as a red flag.

4️⃣ Repeat Borrowing Policies

Short-term lenders often allow repeat borrowing after successful repayment.

However:

  • Some gradually increase limits
  • Others maintain strict caps
  • Some may reduce approval if repayment patterns appear strained

Repeat borrowing is one of the largest risk factors in payday-style lending.

If you find yourself borrowing every month, the issue is likely structural cash flow — not lender selection.

5️⃣ Customer Experience & Transparency

Key areas to compare:

  • Clarity of pre-agreement disclosure
  • Ease of contacting support
  • Hardship flexibility
  • Complaint handling

Under the National Credit Act, lenders must provide clear breakdowns of total cost before you accept.

Always check:

  • Is the repayment amount clearly stated?
  • Are all fees listed?
  • Is the debit order date specified?

Transparency is more important than marketing claims.

6️⃣ Which Lender Is Best for Which Situation?

Here’s a practical breakdown:

Situation Most Suitable Type of Lender
Small emergency under R2,000 Any regulated short-term lender
Need above R4,000 Higher-limit short-term provider
Already financially stretched Consider instalment alternative
First-time borrower Lower limit may reduce risk
Ongoing monthly shortfall Structured longer-term product

The best lender is not necessarily the one that approves you fastest.

It is the one whose repayment structure you can sustain.

Key Takeaway From This Comparison

Under South Africa’s regulated credit environment:

  • Pricing structures are broadly similar
  • Maximum limits vary slightly
  • Approval algorithms differ
  • The real risk lies in repayment pressure

Costs may differ between lenders depending on the loan category, amount, term, fees and individual offer.

Choosing between a very short repayment period and a longer instalment structure may make an even greater difference to your monthly cash flow.

That is the more important financial decision.

Expert Insight

Many borrowers compare lenders horizontally:

“Which payday lender is cheapest?”

But the more impactful comparison is vertical:

“Is a payday structure right for my situation?”

If you can repay comfortably in one cycle, short-term lending can function as an emergency bridge.

If not, comparing structured online loan options with extended repayment may reduce risk significantly.

If you want to see how Sunshine Loans compares side-by-side with other regulated lenders across loan limits, repayment terms, and approval criteria, you can review our full loan comparison hub where multiple providers are evaluated using consistent criteria.

What Happens If You Miss a Payment?

If you miss repayment:

  1. Debit order fails
  2. Bank may charge penalty fee
  3. Lender may apply default interest
  4. Account may be handed to collections
  5. Credit bureau listing may occur

Late payment impacts your credit profile and future borrowing ability.

If you expect repayment difficulties, contact the lender before the due date.

How a Sunshine Loan May Affect Your Credit Record

Sunshine Loans may use credit-bureau information when assessing an application. Applying for credit, taking out a new loan and making or missing repayments can all form part of your broader credit record.

Repaying according to the agreement may help you avoid adverse payment information. However, taking out a Sunshine loan does not guarantee that your credit score will improve.

If you miss payments, the consequences may include:

  • Adverse information being reported to a credit bureau
  • Greater difficulty qualifying for future credit
  • Possible collection activity

If you are working on rebuilding credit, structured bad credit loan comparisons may offer more manageable repayment options.
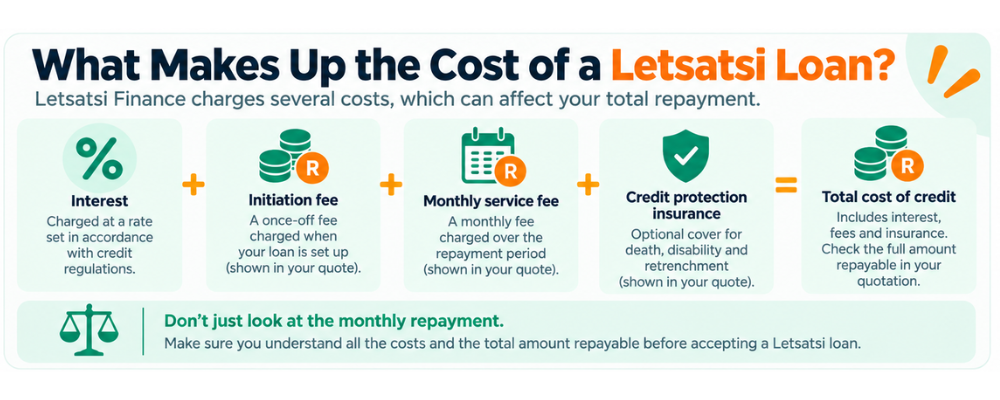
When Sunshine Loans May Be a Good Choice

  • Short-term emergency
  • Stable salary
  • One-time borrowing
  • Clear repayment plan

When You Should Consider Alternatives

  • Multiple existing loans
  • Already short each month
  • Need more than 49 days to repay
  • Need over R4,000

Short-term loans are designed for temporary gaps — not ongoing financial pressure. If you are already managing multiple debts, regularly running short before payday, or relying on borrowing each month to cover essentials, a short repayment schedule can worsen the cycle rather than solve it. In these situations, the issue is often cash flow imbalance, not access to credit. Choosing a longer-term product with structured monthly repayments may reduce repayment shock and help stabilise your budget. The key question is not “Can I get approved?” but “Will this repayment leave me financially stable next month?”

Decision Framework Before Borrowing

Ask yourself:

  1. Can I repay in full without borrowing again?
  2. Is this expense urgent or emotional?
  3. Have I compared longer-term alternatives?
  4. Will this affect rent or essential bills?
  5. Am I using more than one short-term lender?

If unsure — pause.

Responsible Borrowing Checklist

☑ Confirm total repayment
☑ Confirm debit order date
☑ Understand late fees
☑ Check early settlement options
☑ Ensure post-repayment affordability

Short-term loan checks to complete before borrowing

Data Security & Privacy Considerations

Sunshine Loans collects:

  • ID information
  • Bank details
  • Income data

Ensure:

  • Website is secure (HTTPS)
  • You are on official domain
  • You understand privacy policy

Never share login credentials.

Before making a final decision, here are answers to the most common questions South African borrowers ask about Sunshine Loans.

Frequently Asked Questions

Is Sunshine Loans a legitimate lender in South Africa?

Yes. MoneySpot Finance SA (Pty) Ltd, trading as Sunshine Loans, is registered with the National Credit Regulator under NCRCP14110. Registration does not guarantee that a loan will be affordable, so always check the full cost and repayment terms before accepting an offer.

How much can I borrow from Sunshine Loans?

Sunshine Loans currently offers short-term loans from R500 to R4,000. The amount offered will depend on your income, existing financial commitments, credit profile and affordability assessment.

What is the Sunshine Loans repayment period?

Sunshine Loans currently advertises repayment periods of 4 to 49 days. Your repayment schedule should be shown in the quotation and credit agreement provided before you accept the loan.

How much interest does Sunshine Loans charge?

The cost depends on the amount borrowed, repayment term and whether it is your first or a subsequent short-term loan. Your quotation should show the interest, applicable fees, VAT and total amount repayable in rand.

Does Sunshine Loans perform a credit check?

Sunshine Loans considers credit and financial information when assessing an application. It also conducts an affordability assessment based on factors such as your income, expenses, existing commitments and recent banking activity. Approval is not guaranteed.

How quickly does Sunshine Loans pay out?

Sunshine Loans says applications submitted during business hours are typically processed quickly and that approved funds may arrive by the end of the business day. The actual timing depends on verification, approval and your bank’s processing times.

What do I need to apply for a Sunshine loan?

You generally need to be over 18, live in South Africa, be employed and receive a regular income. You should also have your South African ID, bank details and recent bank statements available when applying.

Can I get a Sunshine loan with bad credit?

A perfect credit history is not necessarily required, but approval will depend on Sunshine Loans’ assessment of your recent repayment history and ability to afford the loan. Sunshine Loans does not guarantee approval for applicants with bad credit.

What happens if I miss a repayment?

A missed repayment could result in additional charges, collection activity and adverse information being reported to a credit bureau. Contact Sunshine Loans as soon as possible if you believe you will be unable to pay on the agreed date.

Can I extend a Sunshine loan?

You should contact Sunshine Loans directly to ask what options may be available for your particular agreement. Do not assume that a loan can automatically be extended, and remember that changing a repayment arrangement could increase the total cost.

Can I repay a Sunshine loan early?

South African consumers generally have the right to settle a credit agreement early. Ask Sunshine Loans for a settlement figure so that you know the exact amount required and whether early payment will reduce the remaining cost.

Will a Sunshine loan affect my credit score?

It could. Applying for credit, opening a new loan and making or missing repayments may all affect your broader credit profile. Paying on time does not guarantee that your score will improve, while missed payments could make future borrowing more difficult.

Is it safe to apply for Sunshine Loans online?

Only apply through the official sunshineloans.co.za website and check that the connection is secure before entering personal information. Never give your banking password, PIN or one-time PIN to someone claiming that they can arrange approval for you.

How does Sunshine Loans compare with an instalment loan?

Sunshine Loans offers small amounts over a short period of 4 to 49 days. Instalment loans generally spread repayments over a longer period and may offer larger amounts, although a longer term can increase the total interest paid.

Should I compare lenders before applying?

Yes. Compare the amount available, repayment schedule, total cost and eligibility requirements—not only application or payout speed. The most suitable option is one whose repayments fit comfortably within your budget.

Learn more about instalment loan options with FatCat Loans.

Final Expert Verdict

Sunshine Loans is a legitimate, NCR-registered short-term lender offering fast access to small emergency funds between R500 and R4,000. The application process is fully online, approval decisions are typically quick, and pricing structures operate within South Africa’s regulated National Credit Act framework.

However, legality does not equal affordability.

Because the repayment period is only 4 to 49 days, the real risk is not approval—it is whether the scheduled repayments will place too much pressure on your next pay cycle. For borrowers with stable income and a clear plan to repay on the agreed date, Sunshine Loans can function as a short-term emergency bridge. But for those already managing financial strain, juggling multiple debts, or experiencing recurring monthly shortfalls, this structure may increase stress rather than reduce it.

The most important factor is not speed of payout or marketing claims. It is whether the full repayment amount fits comfortably into your next pay cycle without forcing you to borrow again.

If you can repay confidently and the expense is genuinely urgent, Sunshine Loans may be suitable.

If you need more time, more flexibility, or lower monthly pressure, comparing structured alternatives before committing could provide greater long-term financial stability.

Borrow deliberately. Review the full pre-agreement statement. Understand the total cost in rand. And make a decision based on sustainability — not urgency.

TymeBank Loans Review (2026): Rates, Fees, Requirements & How to Apply

TymeBank loan review for South Africa. Learn how TymeBank loans work, eligibility requirements, fees, repayment terms, and how to apply digitally.

TymeBank Loans Review

Last Updated:  September 2026

TymeBank is one of South Africa’s leading digital banks, built around low fees, app-based banking, and branchless convenience. Unlike traditional banks, TymeBank operates almost entirely online, which influences how its credit products work and who they’re best suited for.

If you’re considering a TymeBank loan, this review explains what TymeBank offers, how their lending works, who qualifies, what it costs, and how it compares to other major banks like Capitec, FNB, Nedbank, and African Bank.

Important 2026 Update: TymeBank officially became GoTyme Bank in February 2026. It remains the same licensed South African bank, but customers now use the GoTyme Bank brand and app. We’ve retained references to “TymeBank loans” in this review because existing customers and borrowers may still know the bank by its former name.

If you’re comparing TymeBank with other borrowing options, you can also compare lenders in South Africa through FatCat Loans before deciding which type of loan may suit your needs.

Important: FatCat Loans is a loan comparison service and is not affiliated with, endorsed by or owned by TymeBank. GoTyme may not be one of the lenders available through our comparison service. Loan products, rates, fees and eligibility criteria can change, so always confirm the terms of your individual offer before accepting credit.

Quick verdict: is TymeBank a good loan option?

TymeBank can be a good option for borrowers who prefer a fully digital banking experience and want access to credit without visiting a branch. It is particularly convenient for existing TymeBank customers who already receive income into their account and manage finances through the app.

That said, TymeBank loans are often offer-based, meaning not every customer will automatically qualify. Loan amounts may also be lower than those offered by traditional banks, and interest rates depend heavily on your personal profile.

Borrowers who prefer a fully digital process may also want to explore fully online loan options before committing to a bank-based loan.

Explore other loan options with FatCat Loans in South Africa.

TymeBank loan overview (at a glance)

TymeBank credit products vary depending on customer eligibility and current product availability, but typical features include:

  • Digital application and account-linked repayments
  • Personalised loan offers based on affordability
  • Fixed monthly repayments (depending on product)
  • No physical branch visits required
  • Integration with your TymeBank account

Before applying, it’s a good idea to estimate your monthly loan repayments so you know what instalment fits comfortably into your budget.

TymeBank loan overview and affordability checks

Does TymeBank offer personal loans?

TymeBank does not always advertise a single, standard personal loan product in the same way traditional banks do. Instead, loan availability is often profile-based and may appear as an offer within the TymeBank app.

This means:

  • Some customers may see loan offers immediately
  • Others may not qualify until they build transaction history
  • Interest rates and limits can vary widely

If you already use TymeBank for salary deposits and daily banking, your account activity may work in your favour.

How much can you borrow from TymeBank?

The amount you can borrow depends on:

  • Your income and affordability
  • Your TymeBank account activity
  • Your credit score and repayment history
  • Existing debt obligations
  • The specific loan product offered

Even if you qualify for a higher amount, borrowing only what you need can significantly reduce interest costs and repayment pressure.

TymeBank repayment terms: what to expect

Repayment terms vary based on the loan offer and your profile. As with most personal loans, longer repayment periods reduce monthly instalments but increase the total cost of credit.

A common mistake is choosing the longest term simply to lower the monthly payment.

If you prefer borrowing with scheduled monthly repayments, you can also compare instalment loan options in South Africa before deciding which repayment structure suits your budget.

A safer rule:
Choose the shortest repayment term you can afford comfortably.

If you’re unsure, it helps to work out your loan repayment before applying and compare different terms side by side.

TymeBank interest rates: how competitive are they?

TymeBank loan interest rates are personalised. This means two borrowers can receive very different rates depending on:

  • Credit score and payment history
  • Income stability
  • Debt-to-income ratio
  • Recent credit applications
  • Overall affordability

Always compare the total repayable amount, not just the interest rate or monthly instalment.

If you’re concerned about approval due to your credit profile, it may be worth exploring alternatives if you have a low credit score before submitting multiple applications.

TymeBank fees and total loan cost

TymeBank loans may include the following costs, depending on the product:

Initiation fee

A once-off fee charged when the loan is granted.

Monthly service fee

A recurring monthly fee added to your instalment.

Credit life insurance

Some loans include insurance, while others offer it separately. Always confirm whether it’s optional or mandatory.

Total repayable amount

This is the most important figure to compare between lenders. It shows the true cost of the loan over time.

TymeBank loan requirements

Loan eligibility depends on affordability and credit checks. Typical requirements include:

  • South African ID
  • Minimum age of 18
  • Proof of income
  • Passing affordability assessment
  • Acceptable credit profile

Current GoTyme Bank requirements: GoTyme Bank’s personal loan page currently asks applicants for a South African ID, mobile number and email address, and three months’ bank statements. Applicants must also be at least 18 years old. The bank states that the latest bank statement should show the applicant’s last three salary deposits.

Because the current process is digital, supporting information and documents are generally submitted electronically through GoTyme Bank’s current channels.

Does TymeBank Perform a Credit Check?

Yes. TymeBank/GoTyme Bank assesses creditworthiness and affordability when considering a loan application.

A credit assessment can consider factors such as your repayment history, existing debts, income and other information relevant to whether additional credit is affordable.

This means approval isn’t guaranteed simply because you meet the basic application requirements.

If you’re unsure how lender enquiries work, read our guide to soft vs hard credit checks in South Africa.

How to apply for a TymeBank loan

If a loan is available to you, the process is usually app-based:

  1. Open the GoTyme Bank app
  2. Navigate to available credit offers
  3. Select your loan amount
  4. Choose a repayment term
  5. Review the full quote carefully
  6. Accept the agreement if satisfied
  7. Receive funds if approved

Existing GoTyme Bank customers can currently access Personal Loans through the GoTyme Bank app by selecting Personal Loans and then Apply Now.

For the latest application requirements and product information, check the official GoTyme Bank Personal Loans page.

Always take time to review the agreement before confirming.

Pros and cons of TymeBank loans

Advantages

  • Fully digital application and management
  • Convenient for existing GoTyme Bank customers
  • No branch visits required
  • Clear repayment structure
  • App-based control of finances

Disadvantages

  • Loan availability may be limited or offer-based
  • Loan amounts may be lower than traditional banks
  • Interest rates vary widely by profile
  • Limited in-person support

Who should consider a TymeBank loan?

TymeBank loans are well suited for borrowers who:

  • Prefer digital banking
  • Have stable income
  • Already use GoTyme Bank regularly
  • Want simple repayments without branch visits

They may also work for consolidation, provided the new loan improves affordability. In that case, it’s worth exploring debt consolidation options first.

Who should avoid a TymeBank loan?

TymeBank may not be ideal if:

  • You need a large loan amount
  • You prefer face-to-face service
  • You are already financially over-stretched

If you need money urgently, compare faster payout loan alternatives, but always be cautious of high-cost lenders.

TymeBank vs other South African banks

Loan comparison table

Feature TymeBank Capitec FNB Nedbank African Bank
Type of bank Digital-only Retail bank Retail bank Retail bank Retail bank
Loan availability Offer-based Widely available Widely available Widely available Widely available
Max loan amount Profile-based Up to R500,000 ±R300,000 ±R400,000 ±R350,000
Interest rates Personalised Personalised Personalised Personalised Personalised
Repayment terms Profile-based Up to 84 months Up to 60 months Up to 72 months Up to 72 months

Is TymeBank Legit?

Yes. TymeBank is a legitimate South African bank and officially changed its name to GoTyme Bank in February 2026. The rebrand did not create a new bank or change existing customer accounts.

GoTyme Bank Limited is a registered South African credit provider under NCRCP 10774 and an authorised financial services provider under FSP 49140.

Consumers can verify registered credit providers through the National Credit Regulator (NCR).

Be cautious of unsolicited loan offers claiming to represent TymeBank or GoTyme Bank. Use the bank’s official channels before providing ID numbers, banking information or other personal details.

How to compare loans correctly

Most borrowers compare loans by monthly instalment alone. A better approach is to compare:

  • Total repayable amount
  • Repayment term length
  • Fees and insurance
  • Approval likelihood

What to check before accepting a TymeBank loan

To get a clearer picture, it’s wise to compare personal loan options before committing.

TymeBank alternatives worth considering

If TymeBank isn’t the right fit, you may want to:

  • Compare loans from traditional banks
  • Explore online lending platforms
  • Consider alternatives based on your credit profile

You can also apply and compare loan offers through one process to see what you qualify for without committing upfront.

Responsible borrowing

Before taking any loan, ask yourself:

  • Can I afford this repayment long-term?
  • Do I understand the total cost?
  • Is this loan solving a real problem?

Always be alert to scams. Learn more about protecting yourself from loan scams before sharing personal or banking details online.

If you’d like to see how TymeBank’s loan offering compares with other South African lenders in terms of limits, repayment terms and eligibility requirements, you can explore our detailed loan comparison guide covering multiple regulated providers.

Explore other loan options with FatCat Loans in South Africa.

Final thoughts: should you apply for a TymeBank loan?

GoTyme Bank, formerly TymeBank, offers a modern, digital-first approach to borrowing that suits many South Africans. If you qualify for a competitive offer and prefer managing everything through an app, it can be a convenient option.

However, because pricing and availability are personalised, always compare your quote against other lenders before accepting.

Frequently Asked Questions About TymeBank Loans

Does TymeBank offer personal loans?

TymeBank may offer loan products depending on your profile and account activity, often visible directly in the app.

What interest rate does TymeBank charge?

Interest rates are personalised and depend on affordability and credit profile.

How do I apply for a TymeBank loan?

Applications are typically completed digitally through GoTyme Bank’s current channels if an offer is available.

Can TymeBank loans be used for debt consolidation?

A personal loan may potentially be used to repay existing debts, depending on the terms of the loan agreement. If you’re considering this, compare the new loan’s interest, fees, repayment term and total amount repayable with your existing debts before proceeding.

How long does approval take?

Approval time varies depending on verification and affordability checks.

Is TymeBank now GoTyme Bank?

Yes. TymeBank officially changed its name to GoTyme Bank in February 2026. It is a rebrand of the existing bank rather than a completely new bank, so references to TymeBank in this review relate to the bank that now operates as GoTyme Bank.

Does TymeBank perform a credit check?

Yes. TymeBank/GoTyme Bank assesses creditworthiness and affordability when considering loan applications. Meeting the basic eligibility requirements does not guarantee that your application will be approved.

Letsatsi Finance Loan Review (2026): Rates, Fees & Requirements

In-depth Letsatsi Finance review for South Africa covering loan limits, regulated fees under the NCA, repayment risks, eligibility requirements and smarter borrowing alternatives.

Letsatsi Finance Loans Review South Africa

Last Updated: September 2026

Letsatsi Finance and Loan (Pty) Ltd is a South African non-bank credit provider offering several types of personal credit, including one-month, short-term and longer-term loans. Letsatsi also advertises debt consolidation solutions for qualifying borrowers.

If you’re considering a loan from Letsatsi Finance, this review explains how their loans work, who they’re best suited for, what to watch out for, and how they compare to other options in the market.

If you’re comparing Letsatsi Finance with other borrowing options, you can also compare lenders in South Africa through FatCat Loans before deciding which type of loan may suit your needs.

Quick verdict: is Letsatsi Finance a good loan option?

Letsatsi Finance may be an option for borrowers looking for smaller short-term loans, structured instalments or other non-bank credit products. The right fit depends on the amount you need, the repayment period, the total borrowing cost and whether the instalment is affordable for your budget.

However, short-term credit can become expensive once interest, fees and credit protection insurance are included. These loans are best used carefully, for short-term needs, and only if the repayment fits comfortably into your budget.

Borrowers who want to compare alternatives should consider comparing personal loan options before committing.

Important: FatCat Loans is a loan comparison service and is not affiliated with, endorsed by or owned by Letsatsi Finance and Loan (Pty) Ltd. Letsatsi Finance may not be one of the lenders available through our comparison service. Loan amounts, rates, fees and eligibility criteria can change. Always confirm the terms of your individual quotation and pre-agreement statement before accepting credit.

Compare Letsatsi Finance loan options with alternative lenders

Letsatsi Finance Loans at a Glance

Letsatsi Loan Feature Details
Credit provider Letsatsi Finance and Loan (Pty) Ltd
NCR registration NCRCP895
FSP number 43543
Short-term loan amount R500 – R7,000
Short-term repayment period 2 – 6 months
Application assessment Credit and affordability checks apply
Minimum income R3,500 per month according to Letsatsi’s current FAQ
Employment Permanently employed for more than 6 months
Age 21 – 60 according to Letsatsi’s current FAQ
Funding Letsatsi’s FAQ states that approved borrowers receive funds within 24 hours; actual payout time can vary.

Letsatsi Finance loan amounts and requirements

Product limits, pricing and eligibility can change. Always confirm the terms shown in your individual Letsatsi quotation before accepting credit.

Is Letsatsi Finance Legit and Registered in South Africa?

Yes. Letsatsi Finance and Loan (Pty) Ltd states that it is a registered credit provider with the National Credit Regulator under NCRCP895 and an authorised financial services provider under FSP 43543.

The company’s published terms identify Letsatsi Finance and Loan (Pty) Ltd under registration number 2004/029710/07.

Being registered does not mean that every Letsatsi loan will be suitable or affordable for every borrower. You should still check the interest, fees, insurance costs, repayment period and total amount repayable shown in your own quotation.

Consumers can independently verify credit-provider information through the National Credit Regulator.

What Types of Loans Does Letsatsi Finance Offer?

Letsatsi Finance advertises several borrowing options rather than a single short-term loan product.

One-Month Loans

Letsatsi advertises one-month loans for unexpected expenses. Because repayment takes place over a very short period, check that the required repayment will fit alongside your normal monthly expenses before accepting the loan.

Short-Term Loans

Letsatsi currently advertises short-term loans from R500 to R7,000, with repayment periods of 2 to 6 months. These may be used for unexpected expenses where a smaller amount is required.

Borrowers comparing this type of credit can also explore short-term loans in South Africa before applying.

Long-Term Loans

Letsatsi also advertises longer-term lending for larger planned expenses. The amount, repayment period and cost available to an individual applicant will depend on the lender’s assessment and quotation.

Debt Consolidation

Letsatsi advertises debt consolidation as another option, intended to combine multiple qualifying credit commitments into one loan. Consolidation does not automatically reduce the overall cost of debt, so compare the new interest rate, fees, repayment term and total cost carefully.

You can learn more about debt consolidation loans in South Africa before deciding whether this approach is appropriate.

How Much Can You Borrow From Letsatsi Finance?

For its short-term loan product, Letsatsi currently advertises borrowing from R500 to R7,000.

The amount you are actually offered can depend on your income, existing credit commitments, credit profile and affordability assessment.

Letsatsi also advertises longer-term lending products, so not every Letsatsi loan is necessarily limited to the short-term R7,000 maximum. Check the specific product and your individual quotation rather than assuming the same limit applies to every Letsatsi loan.

Letsatsi Finance Repayment Terms

Repayment depends on the Letsatsi product you choose. Its current short-term loans are advertised with repayment periods of 2 to 6 months.

A shorter repayment term can reduce how long you remain in debt, but it can also result in a larger instalment relative to the amount borrowed. Before accepting an offer, check:

  • the number of repayments
  • the amount of each repayment
  • the first and final payment dates
  • the total amount repayable
  • whether fees and credit protection insurance are included

Do not judge affordability from the loan amount alone. The repayment needs to fit your budget after essential expenses and existing debt commitments.

Letsatsi Finance Interest Rates, Fees and Loan Costs

The cost of a Letsatsi loan is not limited to the interest rate. Depending on the product and agreement, the total cost may include interest, an initiation fee, a monthly service fee and credit protection insurance.

Letsatsi’s current loan calculator displays the following charges for the product shown on its portal:

  • Initiation fee: R165 on the first R1,000 advanced, plus 10% of the amount above R1,000, plus VAT, subject to the applicable cap.
  • Service fee: R69 per month including VAT.
  • Credit life insurance: R4.50 per R1,000 borrowed per month.
  • Interest: Letsatsi states that interest is charged in accordance with applicable credit regulations. The rate applicable to your loan should be confirmed in your quotation and pre-agreement statement.

Costs that can make up a Letsatsi Finance loan

These figures should not be treated as a guaranteed quotation. Your actual costs depend on the product, amount, repayment period and agreement offered to you.

Why the total repayment matters more than the advertised rate

A loan can appear manageable when you look only at the amount borrowed or interest rate. Fees and insurance can increase the total cost.

Before accepting a Letsatsi loan, compare:

  1. the amount you will actually receive
  2. the interest charged
  3. all initiation and service fees
  4. credit protection insurance
  5. the number and size of repayments
  6. the total amount you will repay

Your quotation and pre-agreement statement should be the final source for the cost of your particular loan.

Letsatsi Finance Loan Requirements

According to Letsatsi’s current FAQ, personal-loan applicants generally need to:

  • be a South African citizen
  • be between 21 and 60 years old
  • earn at least R3,500 per month
  • be permanently employed for more than 6 months
  • have their salary paid into a bank account
  • not be under debt review or administration

Meeting these basic requirements does not guarantee approval. Letsatsi still performs the required credit and affordability assessment before deciding whether to offer credit.

What Documents Do You Need for a Letsatsi Loan?

Letsatsi currently lists the following documents for personal-loan applications:

  • a valid South African ID
  • your latest 2 months’ payslips
  • your latest 3 months’ bank statements
  • proof of residence that is no more than 3 months old

Letsatsi’s published document requirements are not completely consistent across its website. Its FAQ and short-term loan page currently state 2 months’ payslips, while its general loans page refers to 3 months’ payslips. Check the requirements for your specific loan before applying.

Letsatsi’s FAQ distinguishes between document requirements for new and existing clients, so check its current instructions before submitting an application.

Does Letsatsi Finance Perform a Credit Check?

Yes. Letsatsi states that it performs credit checks and calculates affordability when assessing applications.

Having a judgement does not necessarily prevent you from submitting an application. Letsatsi’s FAQ says applicants with judgements may still apply, but the lender will perform the necessary credit and affordability checks before making a decision.

This does not mean that Letsatsi offers guaranteed approval or loans without credit checks.

If you’re concerned about your credit history, you can compare bad credit loan options in South Africa before making multiple applications.

How to apply for a Letsatsi Finance loan

Letsatsi accepts loan enquiries through its website, call centre and branch network. The exact process may depend on the product and whether you are a new or existing customer. A typical application involves:

  1. Completing an online or assisted application
  2. Submitting required documents
  3. Undergoing affordability and credit checks
  4. Reviewing your loan offer
  5. Accepting the agreement if satisfied
  6. Receiving funds if approved

If you prefer a digital application process, you can also compare online loan options in South Africa.

Because these loans are often processed quickly, it’s important to read the agreement carefully before accepting.

How Long Does a Letsatsi Loan Take to Pay Out?

Letsatsi advertises that loan applications can be approved within one hour and promotes same-day payment once the application has been approved, the contract signed and the required payment details captured.

Its FAQ separately states that approved borrowers receive the money within 24 hours.

These timeframes should not be treated as guaranteed. Verification, supporting documents, affordability checks, signing the agreement and banking processes can affect how quickly funds are received.

Pros and Cons of Letsatsi Finance Loans

Potential advantages

  • Several loan types, including short-term and longer-term options
  • Short-term borrowing from R500 to R7,000
  • Online, branch and call-centre application channels
  • Structured repayment periods
  • Same-day payout may be available after approval and completion of the required steps

Potential drawbacks

  • Interest, fees and credit protection insurance can increase the total cost of borrowing
  • Short repayment periods can result in relatively high instalments
  • Approval remains subject to credit and affordability checks
  • Repeated short-term borrowing can place pressure on your budget

Who should consider a Letsatsi Finance loan?

Letsatsi Finance may be suitable if you:

  • Need a small amount of money short-term
  • Prefer a non-bank lender offering short-term or structured credit
  • Have a clear repayment plan
  • Understand the full cost of the loan

These loans should be used cautiously and ideally as a temporary solution, not ongoing financial support.

Who should avoid Letsatsi Finance loans?

You should think carefully before applying if:

  • You already struggle with monthly expenses
  • The loan amount or repayment term offered does not suit your needs
  • You plan to use the loan repeatedly
  • You are borrowing to cover regular living costs

If speed is your main concern, compare faster payout loan alternatives, but always check the cost carefully.

Letsatsi Finance vs Bank Personal Loans

Letsatsi Finance and traditional banks can serve different borrowing needs.

Letsatsi offers several credit products, including smaller short-term loans, while banks such as Capitec and African Bank also offer larger personal loans that may be repaid over longer periods.

When comparing them, focus on:

  • the amount you actually need
  • the personalised interest rate offered
  • initiation, service and insurance costs
  • the repayment period
  • the monthly instalment
  • the total amount repayable

A larger loan limit or longer term does not automatically mean a cheaper or more suitable loan. Compare the actual quotation offered to you.

If you’re deciding between Letsatsi Finance and a traditional bank, you may also want to read our Capitec loans review and African Bank loans review to compare their loan amounts, repayment terms, eligibility requirements and borrowing costs.

Better alternatives to consider first

Before taking a short-term loan, it’s often worth checking:

  • Whether another personal loan offers a lower total cost
  • Whether debt consolidation could simplify existing repayments and whether the total cost would be lower
  • Whether delaying the expense is possible

You can also apply and compare loan offers to see what options you qualify for without committing upfront.

Does a Letsatsi Loan Include Credit Protection Insurance?

Letsatsi states that credit protection insurance is included in its loan contract. Its FAQ says the policy can cover events including death, permanent disability and retrenchment during the original loan term.

Letsatsi also says borrowers are free to use their own qualifying credit protection insurance, provided they supply proof of that cover.

The insurance premium adds to the cost of borrowing, so check the premium and cover shown in your agreement rather than looking only at the loan’s interest rate.

Can You Settle a Letsatsi Loan Early?

Letsatsi allows customers to request their current loan balance and a settlement letter. According to its FAQ, settlement-letter requests can be made through a branch or Head Office and the letter is generally issued within 3–5 working days.

Before making an early settlement payment, request an up-to-date settlement amount so you know exactly what is required to close the account.

Responsible borrowing

Short-term loans can solve immediate problems—but they can also create long-term debt if misused.

Before borrowing, ask yourself:

  • Can I repay this loan without borrowing again?
  • Do I understand the full cost?
  • Is this expense unavoidable?

Always be cautious of lenders requesting upfront payments or making unrealistic promises. Learn more about protecting yourself from loan scams before sharing personal details.

If you are already under debt review, Letsatsi’s current eligibility information says you cannot apply for a personal loan. Do not take additional credit to try to solve persistent repayment difficulty.

If you want to see how Letsatsi Finance compares with other South African loan providers across approval criteria, loan limits and repayment flexibility, you can review our side-by-side lender comparison page for a broader overview.

Final Verdict: Is a Letsatsi Finance Loan Worth Considering?

Letsatsi Finance offers several types of credit, including smaller short-term loans as well as longer-term and debt consolidation options.

It may be worth considering if the product matches the amount and repayment period you need and the full repayment fits comfortably within your budget.

Before accepting a loan, check the interest, fees, insurance costs, repayment schedule and total amount repayable shown in your quotation.

If you’re unsure, compare Letsatsi with other regulated lenders before committing to credit.

Sources & Verification

This page is maintained by the FatCat Loans South Africa Editorial Team and is reviewed against primary sources including:

  • Letsatsi Finance’s official loan and product information
  • Letsatsi Finance’s current application and eligibility FAQs
  • Letsatsi Finance’s loan calculator and published rates and charges
  • Letsatsi Finance’s published terms and conditions
  • National Credit Regulator information
  • South Africa’s National Credit Act

Loan amounts, rates, fees, insurance costs, eligibility and repayment terms can change. Your individual quotation and pre-agreement statement should be used to confirm the actual cost and terms offered to you.

Frequently Asked Questions About Letsatsi Finance Loans

Is Letsatsi Finance a legitimate lender?

Yes. Letsatsi Finance and Loan (Pty) Ltd states that it is registered with the National Credit Regulator under NCRCP895 and is an authorised financial services provider under FSP 43543. Being registered does not mean every loan will be suitable or affordable, so always check the terms of your individual quotation before accepting credit.

How much can I borrow from Letsatsi Finance?

Letsatsi currently advertises short-term loans from R500 to R7,000, with repayment periods of 2 to 6 months. Letsatsi also offers other credit products, including longer-term loans, so the amount available depends on the product, your affordability assessment and the offer made to you.

What are the requirements for a Letsatsi Finance loan?

According to Letsatsi’s current eligibility information, personal-loan applicants generally need to be a South African citizen aged 21 to 60, earn at least R3,500 per month, be permanently employed for more than 6 months, receive their salary into a bank account and not be under debt review or administration. Meeting these requirements does not guarantee approval.

What documents do I need to apply for a Letsatsi loan?

Letsatsi currently lists a valid South African ID, the latest 2 months’ payslips, the latest 3 months’ bank statements and proof of residence no more than 3 months old among the documents that may be required. Requirements can differ for new and existing customers, so check the latest application instructions before applying.

Does Letsatsi Finance perform a credit check?

Yes. Letsatsi states that it performs credit and affordability checks when assessing applications. Its FAQ also says that having a judgement does not necessarily prevent you from applying, but your application will still be assessed. Letsatsi does not offer guaranteed approval or loans without credit checks.

What interest and fees does Letsatsi Finance charge?

The cost depends on the product and your individual credit agreement. Letsatsi’s current loan calculator displays an initiation fee, a monthly service fee, interest and credit life insurance for the product shown. Because these costs can change and may differ between products, check the total amount repayable in your quotation and pre-agreement statement rather than comparing the interest rate alone.

How long does a Letsatsi loan take to pay out?

Letsatsi advertises that applications can be approved within one hour and promotes same-day payment after approval and completion of the required steps. Its FAQ also states that approved borrowers may receive funds within 24 hours. These timeframes are not guaranteed, as verification, documents, affordability checks, contract signing and banking processes can affect payout time.

Can I get a Letsatsi Finance loan with bad credit or a judgement?

A weaker credit history does not automatically determine whether Letsatsi will approve or decline an application. Letsatsi states that applicants with judgements may still apply, but credit and affordability checks are required. Approval depends on your individual circumstances and is not guaranteed. If your credit history is making borrowing difficult, you can also compare bad credit loan options in South Africa before applying.