Loans for Blacklisted Consumers in South Africa

Being “blacklisted” doesn’t mean you’re permanently blocked from credit in South Africa — but it can make borrowing more difficult and expensive. This guide explains what lenders look at, the safest loans for blacklisted consumers, how to avoid scams, and practical steps to improve your approval chances.

What “Blacklisted” Actually Means in South Africa

Last Updated: September 2026

In South Africa, being “blacklisted” does not mean you are on an official blacklist or permanently banned from borrowing. The term is commonly used when a credit report contains negative information such as missed payments, defaults or judgments.

Having negative credit information can make borrowing more difficult, but lenders consider more than your credit score alone. Registered credit providers must assess whether new credit is affordable and may also consider your income, existing financial obligations and credit history before making a decision.

If you are looking for loan options with a poor credit history, FatCat Loans can help you compare options from our lender network. FatCat Loans is a comparison service, not a lender, and approval is never guaranteed.

Quick answer: You may still be considered for credit if you have negative information on your credit report, but this depends on the lender’s criteria, your current financial position and an affordability assessment. Be cautious of anyone promising “guaranteed approval” or credit without the required checks.
Compare loan options with FatCat Loans

What Does “Blacklisted” Mean in South Africa?

The term “blacklisted” is widely used in South Africa, but it is not a formal loan category or permanent borrowing status. It generally refers to negative information recorded on your credit profile.

This may include:

  • Missed or late payments
  • Accounts in arrears or default
  • Judgments
  • Collection activity
  • Debt review status

Credit bureaus collect information about how consumers manage credit. When you apply for a loan, a credit provider may use your credit report alongside other information to assess the risk of lending to you.

However, a negative credit record does not automatically mean that every future application will be declined. Credit providers must also carry out an affordability assessment before granting credit.

How Can Negative Credit Information Affect a Loan Application?

Negative information on your credit report can affect whether a lender is willing to offer you credit, how much you may qualify for and the terms you are offered.

A recent default or missed payment may be viewed differently from an older issue that has since been resolved. Each lender has its own credit criteria, so having a poor credit history does not guarantee either approval or rejection.

How to Check Your Credit Record

If you are unsure what appears on your credit profile, check your credit report before applying for new credit. Your report can show payment history, defaults, judgments and other information that lenders may consider.

You can learn more about how to check your credit report in South Africa.

If information on your report is incorrect, you have the right to dispute it with the relevant credit bureau.

What Lenders Look At When You Apply for a Loan With Bad Credit

Having negative information on your credit report does not mean a lender will ignore your current financial situation. Credit providers consider several factors when assessing an application, including your credit history and whether you can afford the repayments.

Common factors include:

Your Income and Affordability

A lender will assess your income, regular expenses and existing debt commitments to determine whether you can reasonably afford another repayment.

A steady income may help demonstrate your ability to repay, but it does not guarantee approval.

Your Credit History

Lenders may review your payment history, outstanding debts, defaults and other information recorded on your credit report.

The type, severity and age of negative information can all form part of a lender’s assessment.

Your Existing Debt

Existing loan, credit card and other credit repayments can affect how much additional credit you can afford. Applying for more than your budget can support may reduce your chances of being approved.

Recent Credit Applications

Lenders may also consider recent credit enquiries or applications. Making several applications within a short period can result in multiple enquiries appearing on your credit profile, so it is generally better to compare suitable options before applying.
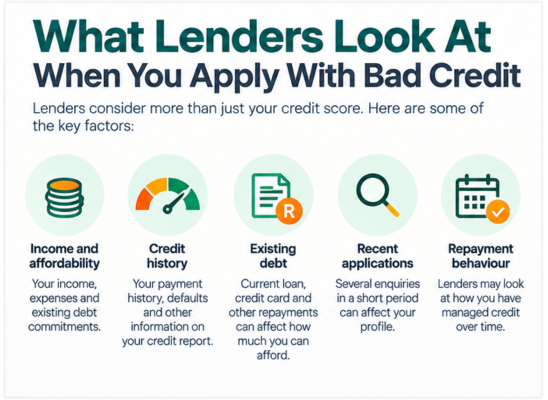
Factors lenders consider when assessing a bad credit loan

Can You Qualify for a Loan if You Are Blacklisted?

You may still be considered for credit if you have negative information on your credit report, but there is no single set of eligibility requirements for a “blacklisted loan”.

Each lender sets its own lending criteria and will assess your application before deciding whether to offer credit.

Depending on the lender and loan product, you may need to:

  • Be at least 18 years old.
  • Have a valid South African ID.
  • Have a regular, verifiable source of income.
  • Have an active South African bank account.
  • Provide the documents required to verify your income and financial position.
  • Pass the lender’s credit and affordability assessment.

Having a regular income does not automatically mean you will qualify. The lender must consider whether the proposed repayments are affordable alongside your existing financial obligations.

Important: If you are currently under debt review, taking on additional credit is generally restricted under the National Credit Act. Speak to your debt counsellor if you are unsure what applies to your situation.

Documents You May Need When Applying

The documents required vary by lender, but you may be asked to provide some or all of the following:

Requirements and Why They Matter

Document Why It May Be Requested
South African ID To verify your identity and age
Recent bank statements To help verify income, expenses and affordability
Proof of income This may include payslips or other evidence of regular income
Proof of address Some lenders may request this for verification purposes
Bank account details Required where approved funds are paid into your bank account

If your credit history is making it harder to find suitable borrowing options, you can also read our guide to bad credit loan options in South Africa.

How to Compare Loan Options With a Poor Credit History

If you have negative information on your credit report, comparing loan options before applying can help you avoid unnecessary applications and understand the costs involved.

When comparing loans, look at:

  • Total cost of credit: Consider the full amount you will repay, not only the monthly instalment.
  • Interest and fees: Check the interest rate and any initiation, service or other permitted charges.
  • Repayment term: A longer term may reduce the monthly repayment but can increase the total amount repaid.
  • Monthly repayment: Make sure the instalment is realistic alongside your existing expenses and debts.
  • Lender registration: Check that the credit provider is registered with the National Credit Regulator (NCR).
  • Loan conditions: Read the pre-agreement statement and quotation carefully before accepting an offer.

FatCat Loans allows you to compare loan options from our lender network. FatCat Loans is not a lender, and submitting an enquiry does not guarantee that you will receive a loan offer.
Compare loan options for poor credit histories

How to Apply for a Loan With a Poor Credit History

The application process varies between lenders, but it will generally involve the following steps:

  1. Check your credit record. Review your credit report and dispute any information you believe is incorrect.
  2. Work out what you can afford. Consider your income, essential expenses and existing debt repayments before deciding how much to apply for.
  3. Compare suitable loan options. Look at the total cost, repayment term, monthly instalment and lender requirements rather than applying to multiple lenders at once.
  4. Prepare your documents. You may need identification, proof of income and recent financial information so the lender can assess your application.
  5. Complete the application. Provide accurate information about your income, expenses and existing financial obligations.
  6. Review the offer carefully. If approved, read the pre-agreement statement and quotation before accepting the credit agreement.
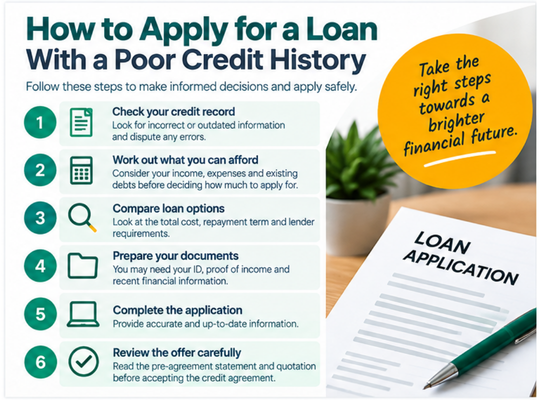
Steps to apply for a loan with a poor credit history

Remember: An application is not the same as approval. The credit provider must assess your application and affordability before deciding whether to offer credit.

Loan Options to Consider With a Poor Credit History

There is no single type of loan specifically for “blacklisted” consumers. Depending on your circumstances and the lender’s criteria, different forms of credit may be available.

Here are some common options and the risks to consider:

Loan Type How It Works Potential Advantage What to Consider
Personal loan A fixed amount repaid in instalments over an agreed term Can provide a structured repayment schedule Your rate, amount and term depend on the lender’s assessment and affordability
Short-term loan Usually a smaller amount repaid over a shorter period May suit a temporary, essential cash-flow need Short repayment periods can make instalments difficult to manage
Secured loan Credit is secured against an eligible asset Security may affect the lender’s risk assessment Your asset may be at risk if you fail to repay as agreed
Debt consolidation loan Existing qualifying debts are combined into one new loan Can simplify multiple repayments It only helps if the new loan is affordable and the overall cost makes sense

You can learn more about personal loans in South Africa, short-term loan options and debt consolidation loans before deciding which type of borrowing may suit your circumstances.
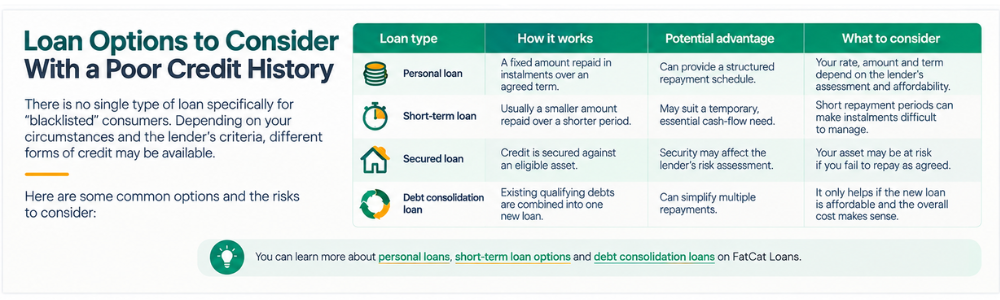
Loan options to consider with a poor credit history

How to Improve Your Chances Before Applying

No strategy can guarantee that a loan application will be approved. However, there are practical steps you can take before applying:

  • Check your credit report: Look for incorrect or outdated information and dispute errors with the relevant credit bureau.
  • Apply for a realistic amount: Consider what you can comfortably repay after your normal living expenses and existing debt commitments.
  • Reduce existing debt where possible: Lower financial commitments may improve your overall affordability.
  • Keep repayments up to date: Paying existing accounts as agreed can help prevent further negative information being added to your credit record.
  • Avoid multiple applications: Compare suitable options first rather than submitting applications to several lenders within a short period.
  • Provide accurate information: Make sure the income, expenses and debt information in your application is complete and correct.

Improving your credit profile takes time. Be wary of businesses or lenders that promise to remove legitimate negative information instantly or guarantee that you will qualify for credit.

How Much Can a Loan Cost if You Have Bad Credit?

Having a poor credit history does not create a separate set of loan charges. The cost of borrowing depends on the type of credit, the amount borrowed, the repayment term, the lender’s assessment and the fees permitted under the credit agreement.

Depending on the loan, your total cost may include:

  • Interest: The rate charged on the amount you borrow.
  • Initiation fee: A once-off fee that may apply when the credit agreement is entered into.
  • Service fee: An ongoing fee that may apply for administering the credit agreement.
  • Credit life insurance: This may apply to certain credit agreements and can add to the overall cost.

Do not compare loans using the monthly repayment alone. A lower monthly instalment over a longer repayment period can still result in a higher total amount repaid.

Before accepting a loan, review the pre-agreement statement and quotation so you understand the interest, fees, repayment amount, repayment term and total cost of credit.

Affordability matters: If a new repayment would leave you struggling to cover essential living costs or existing debt, taking another loan may make your financial position worse. Consider the full repayment obligation before accepting new credit.

How to Avoid Blacklisted Loan Scams

People searching for loans with a poor credit history can be particularly vulnerable to lenders or scammers promising easy approval. Be cautious of any loan offer that sounds too good to be true.

Warning signs can include:

  • Guaranteed approval: Legitimate credit providers must assess an application before granting credit.
  • “No checks” claims: Be wary of anyone promising credit without assessing your financial circumstances.
  • Upfront payments to release a loan: Do not pay money simply because someone claims it is required before approved funds can be released.
  • Pressure to act immediately: You should have an opportunity to understand the agreement and costs before accepting credit.
  • Unverifiable lender details: Check the credit provider’s details and NCR registration rather than relying only on a website, social media profile or WhatsApp message.
  • Requests for sensitive banking information: Never share your PIN, password or one-time PIN (OTP) with someone offering you a loan.

You can check whether a credit provider is registered using the National Credit Regulator’s register of credit providers.

FatCat Loans will never ask you to pay an upfront fee to access a loan. Read our fraud alert if you receive a suspicious message claiming to be from FatCat Loans.

What If Another Loan Is Not the Right Option?

A new loan is not always the best solution, particularly if you are already struggling with existing repayments.

Depending on your situation, alternatives may include:

  • Speaking to your existing creditors about repayment arrangements.
  • Reviewing your budget and prioritising essential expenses before taking on additional debt.
  • Considering debt consolidation only where the new arrangement is affordable and makes financial sense.
  • Seeking help from an NCR-registered debt counsellor if you are unable to keep up with your existing credit commitments.

If you are already under debt review, speak to your debt counsellor before considering any further credit.

How Long Does “Blacklisting” Last in South Africa?

There is no single period for being “blacklisted” because there is no official blacklist. Different types of information can remain on your credit report for different periods.

The retention period depends on the type of information recorded, such as payment history, adverse information, defaults or judgments. Some information may also need to be updated or removed when the underlying debt is paid or the legal requirements for removal are met.

This is why it is better to check your actual credit report rather than assume you will be unable to borrow for a fixed number of years.

If you have settled an account but your credit report has not been updated correctly, contact the credit provider or credit bureau and ask for the information to be investigated.
For current rules on credit information and consumer rights, refer to the National Credit Regulator or the relevant credit bureau.

Your Rights When Applying for Credit

Consumers in South Africa have protections under the National Credit Act. Having a poor credit history does not remove those rights.

When considering a loan:

  • Use a registered credit provider: Verify the provider’s NCR registration before borrowing.
  • Expect an affordability assessment: A lender should assess whether you can afford the proposed credit rather than simply promising approval.
  • Understand the cost: Review the interest, fees, repayment term and total repayment obligation before accepting an agreement.
  • Check your credit information: You have the right to access your credit report and dispute information you believe is incorrect.
  • Keep copies of your agreement: Save your quotation, credit agreement and relevant correspondence in case you need to refer to them later.

If you believe a credit provider has acted unlawfully or your rights have been breached, you can contact the National Credit Regulator for information about the appropriate complaints process.

Common Mistakes to Avoid When Applying With Bad Credit

When you need money urgently, it can be tempting to accept the first loan offer you receive. Before applying or accepting credit, avoid these common mistakes:

  • Applying to several lenders at once: Compare suitable options first rather than submitting multiple applications in a short period.
  • Focusing only on the monthly repayment: Check the interest, fees, repayment term and total amount you will repay.
  • Borrowing more than you need: A larger loan means a larger repayment obligation and potentially a higher overall cost.
  • Assuming approval is guaranteed: A poor credit history does not automatically prevent you from applying, but every application remains subject to the lender’s criteria and affordability assessment.
  • Ignoring warning signs: Verify the lender and never pay an upfront fee simply to have loan funds released.
See loan options with FatCat Loans

Final Thoughts on Loans for Blacklisted Consumers

Having negative information on your credit report does not mean you are permanently banned from applying for credit in South Africa. However, it can affect the options available to you, and approval will depend on the lender’s criteria, your credit profile and whether the repayments are affordable.

Before borrowing, check your credit report, compare the total cost of suitable options and verify that the credit provider is registered with the NCR. Never rely on promises of guaranteed approval or offers that claim the required affordability checks can be avoided.

If another loan would make your existing financial commitments harder to manage, consider speaking to your creditors or an NCR-registered debt counsellor before taking on additional debt.

Editorial disclosure: This article is for general information only and does not constitute financial advice. FatCat Loans is a loan comparison service, not a lender. Loan availability, rates, fees, terms and eligibility depend on the individual credit provider and your circumstances. Always review the lender’s pre-agreement statement and quotation before accepting credit.

Frequently Asked Questions

Can I get a loan if I am blacklisted in South Africa?

You may still be considered for credit if you have negative information on your credit report. Approval is not guaranteed and depends on the lender’s criteria, your credit history, income, existing financial obligations and affordability assessment.

What do lenders check if I have bad credit?

Lenders may consider your credit history, income, regular expenses, existing debt commitments and recent repayment behaviour. They must also assess whether you can afford the proposed repayments before granting credit.

Can I get a blacklisted loan without a credit check?

Be cautious of anyone advertising guaranteed loans with no checks. Registered credit providers are required to assess applications and affordability before granting credit. Having bad credit does not mean these checks can simply be skipped.

Can I get a loan while under debt review?

Access to further credit is generally restricted while you are under debt review. If you are currently under debt review and are unsure about your position, speak to your debt counsellor before applying for additional credit.

How long does blacklisting last in South Africa?

There is no single “blacklisting” period because South Africa does not have an official blacklist. Different types of information can remain on a credit report for different periods, so check your current credit report to see what information is recorded.

What documents might I need when applying?

Requirements vary by lender, but you may be asked for a valid South African ID, proof of income, recent bank statements or other financial information, proof of address and bank account details.

How do I check whether a lender is registered with the NCR?

You can search the National Credit Regulator’s register of credit providers using the lender’s name or NCR registration details. If you cannot verify a lender, investigate further before providing personal information or paying any money.

What should I do if information on my credit report is wrong?

Contact the credit bureau that supplied the report and dispute the information you believe is incorrect. Provide supporting documents where available and keep records of your correspondence while the dispute is investigated.
Bad Credit Consolidation Loans South Africa (2026 Guide)

Explore how consolidation loans with bad credit in South Africa can help you. Get all the details you need on our blog.

Can You Consolidate Debt With Bad Credit in South Africa?

Last Updated: October 2026

Having a poor credit history can make it harder to qualify for a new loan, especially when you already have several outstanding debts. However, bad credit does not automatically mean every credit provider will decline your application.

A debt consolidation loan may allow you to combine eligible existing debts into one new credit agreement. This can simplify repayments, but approval depends on your financial circumstances, and consolidation does not guarantee a lower interest rate or reduced borrowing costs.

This guide explains how bad credit consolidation loans in South Africa work, what lenders may consider, the costs and risks involved, and what alternatives are available if another loan is unsuitable.

What Are Bad Credit Debt Consolidation Loans?

Debt consolidation involves using a new credit agreement to settle eligible existing debts. Depending on the provider, these may include credit cards, store accounts, personal loans and other qualifying credit agreements.

For borrowers with poor credit histories, qualifying may be more difficult because lenders consider existing repayment commitments, credit information and affordability.

Consolidation does not erase debt or automatically improve your credit score. The new loan must still be repaid according to its agreed terms.

For a broader explanation of available products and requirements, visit our debt consolidation loans in South Africa page.

How Bad Credit Consolidation Loans Work in South Africa

Step 1 – Review Your Debts and Credit Information

Start by listing your existing debts, outstanding balances, monthly repayments, interest rates and settlement amounts.

You can also review your credit information through providers such as TransUnion or Experian. Check for errors and dispute inaccurate information through the appropriate channels.

Check your free credit report here with FatCat Loans.

Step 2 – Compare Available Options

Not every credit provider offers debt consolidation, and eligibility requirements differ. Review the interest rate, fees, repayment period and total cost before deciding whether a new agreement would help.

Borrowers with weaker credit histories can also explore our bad credit loan options page to understand the broader types of credit that may be available.

Step 3 – Apply and Complete Affordability Checks

Credit providers may request identification, income information, bank statements, existing debt details and other supporting documents.

The provider will assess your financial circumstances and affordability before deciding whether to approve the application. Having a regular income does not guarantee approval.

Step 4 – Settle Eligible Debts and Repay the New Loan

If approved, the settlement process depends on the credit provider and agreement. Some arrangements may involve direct settlement with existing creditors, while others require the borrower to settle specified debts.

Confirm which accounts have been settled and whether any remain open. You must then repay the new loan according to its agreed repayment schedule.

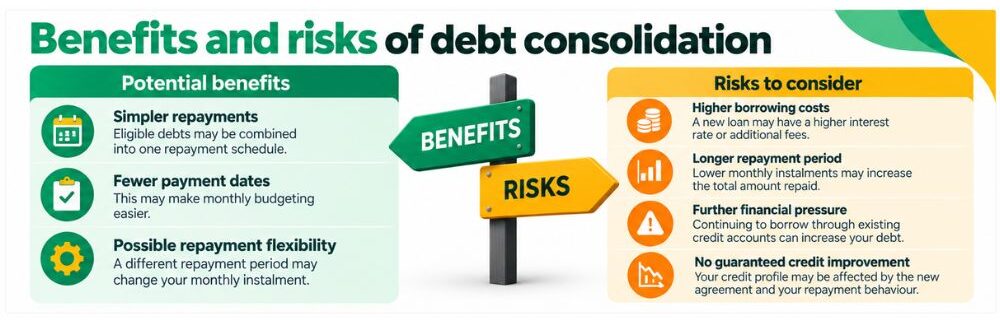
Benefits and risks of debt consolidation in South Africa

Potential Benefits and Risks of Consolidating Debt With Bad Credit

Debt consolidation may offer benefits, but it also carries risks, particularly when your existing financial commitments are already difficult to manage.

Potential Benefits

  • Simpler repayments: Eligible debts may be combined into one new repayment schedule.
  • Fewer payment dates: This may make monthly budgeting easier.
  • Possible repayment flexibility: A different repayment period may change your monthly instalment.

Risks to Consider

  • Higher borrowing costs: A new loan may have a higher interest rate or additional fees.
  • Longer repayment period: Lower monthly instalments may increase the total amount repaid.
  • Further financial pressure: Borrowing again through existing credit accounts can increase your debt.
  • No guaranteed credit improvement: Your credit profile may be affected by the new agreement and your repayment behaviour.

Before consolidating, compare the full cost of the proposed agreement with your existing debts.

Example: Consolidating Debt With a Poor Credit History

Imagine you have three outstanding debts:

  • Store account: R5,000
  • Credit card: R10,000
  • Personal loan: R15,000

Your total outstanding balance is R30,000.

If a credit provider approves a R30,000 consolidation loan and all three debts are eligible for settlement, the new agreement could replace those separate repayment obligations.

However, the monthly repayment and total borrowing cost would depend on the interest rate, fees and repayment period.

Important: If your credit history is poor, the terms offered may be less favourable than you expect. Compare the total repayment amount before accepting the agreement.

This is a hypothetical example for illustration only. It does not represent a specific lender offer or guarantee that these debts can be consolidated.

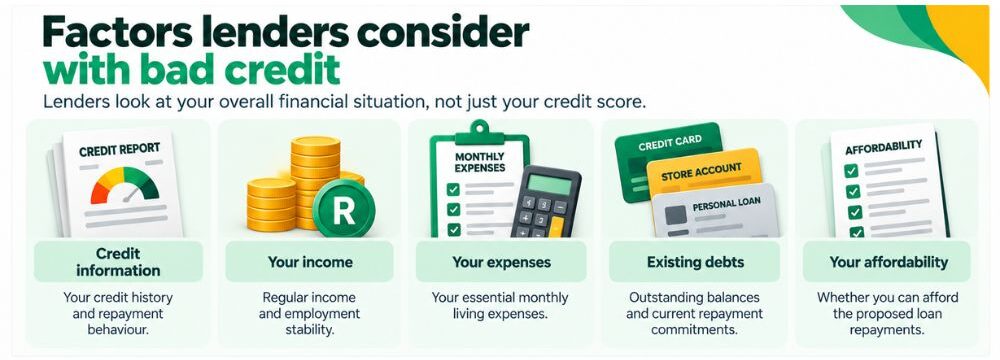
Factors lenders consider for bad credit consolidation loans

Can You Qualify for Debt Consolidation With Bad Credit?

Possibly. Having a poor credit history does not automatically prevent approval, but it may limit your available options.

Credit providers may assess:

  • Your income and regular expenses
  • Existing debts and monthly repayment commitments
  • Your credit information and repayment history
  • The amount you want to borrow
  • Your ability to afford the proposed repayments

There is no single credit score that guarantees approval across all South African credit providers. Each provider applies its own eligibility criteria within applicable legal requirements.

Important: Consumers under debt review are generally restricted from taking on further credit. If you are already under debt review, speak to your registered debt counsellor rather than applying for a new consolidation loan.

How to Compare Consolidation Loans for Bad Credit in South Africa

When comparing options, look at more than just the rate.

Interest Rates

Rates for these solutions are usually higher. However, they differ by lender. So, compare several offers before deciding.

Fees

Check if there are any extra costs, such as initiation or service fees. Always read your loan contract carefully.

Loan Term (Repayment Period)

A shorter repayment period may reduce total interest costs but require higher monthly instalments. A longer period may reduce monthly repayments while increasing the overall cost of borrowing.

Compare the total amount repayable, including applicable fees, rather than focusing only on the monthly instalment.

Monthly Instalments

Use the FatCat Loans calculator to estimate what you can afford.

How to Prepare Before Applying for Debt Consolidation With Bad Credit

Although no action guarantees approval, the following steps may help you assess your position before applying:

  • Check your credit report for inaccurate information.
  • Calculate your current debt repayments and essential monthly expenses.
  • Gather accurate income and existing debt information.
  • Avoid borrowing more than is needed to settle eligible debts.
  • Consider whether the new loan would genuinely improve your financial position.

If your existing repayments are already unaffordable, seeking debt advice may be more appropriate than applying for additional credit.

Common mistakes to avoid with consolidation loans for bad credit

  • Taking a longer loan term just to reduce monthly payments
  • Not comparing multiple lenders before applying
  • Borrowing more than needed during consolidation
  • Continuing to use credit after consolidating debt
  • Ignoring the total repayment amount

Alternatives to Bad Credit Debt Consolidation Loans

If you cannot qualify for an affordable consolidation loan, consider whether another approach may be more suitable.

  • Review your budget: Identify expenses that could be reduced to free up money for existing repayments.
  • Speak to your creditors: Ask whether repayment arrangements are available.
  • Prioritise higher-cost debt: Consider paying additional amounts towards expensive debts where affordable.
  • Seek debt counselling: A registered debt counsellor can assess your circumstances and explain the debt review process where appropriate.

Taking out another loan is not always the best way to manage existing debt.

How to Avoid Scams When Applying for Bad Credit Consolidation Loans South Africa

Borrowers with bad credit are often targeted by unregistered lenders. Therefore, protect yourself by:

  • Verifying that the lender is registered with the NCR.
  • Be cautious of guaranteed approval claims or demands for suspicious upfront payments before a loan is granted.
  • Check the lender’s identity, contact information and registration details. A secure website alone does not prove a lender is legitimate.
  • Comparing legitimate offers through FatCat Loans instead of unverified sources.

Find Consolidation loans with bad credit South Africa with FatCat Loans.

FAQs About Bad Credit Consolidation Loans in South Africa

Can I get a consolidation loan if I am under debt review?

Consumers under debt review are generally restricted from taking on further credit. Speak to your registered debt counsellor about your options before applying for a new loan.

Can debt consolidation improve my credit score?

Debt consolidation does not guarantee a better credit score. Your credit profile may be affected by the new agreement, existing account settlements and your repayment behaviour over time.

How long does approval take?

Application and approval times vary between credit providers. Additional affordability checks or document verification may be required, and approval is not guaranteed.

Do I need collateral for debt consolidation?

Requirements depend on the provider and the credit product. Some arrangements may be unsecured, while others may require security. Always check the terms before applying.

Conclusion: Is Debt Consolidation an Option With Bad Credit?

Debt consolidation may be an option for some South Africans with poor credit histories, but eligibility depends on the credit provider and your financial circumstances.

Before applying, compare the total cost of the proposed agreement with your existing debts. Consider whether the new repayments are affordable and whether consolidation would genuinely help you manage your obligations.

For more information about available products, explore our debt consolidation loan options page.

Disclosure: This article is for informational purposes only and does not constitute financial advice. FatCat Loans is a loan comparison platform, not a lender. Loan approval, rates and terms depend on the credit provider and your individual circumstances.

How to Repay Debt Faster in South Africa: A Practical 2026 Guide

This practical 2026 guide explains how to repay debt faster in South Africa, sharing proven strategies to reduce interest costs, manage repayments, and regain financial control through smarter budgeting and repayment planning

How to Repay Debt Faster in South Africa

Last Updated: October 2026

Learning how to repay debt faster in South Africa starts with understanding what you owe, choosing a realistic repayment strategy and making the most of the money available in your budget.

Whether you have credit card balances, personal loans, store accounts or short-term credit, there are practical steps you can take to reduce outstanding debt. These include prioritising expensive debts, avoiding unnecessary borrowing and making additional repayments when affordable.

This guide explains how the debt snowball and avalanche methods work, how to create a repayment plan and what to do if you are struggling to meet your existing obligations.

Not every strategy suits every borrower. If your repayments are already unaffordable, seeking help from creditors or a registered debt counsellor may be more appropriate than taking on another loan.

Why Repaying Debt Faster Can Make a Difference

Repaying outstanding debt sooner may improve your financial position, particularly when you are paying interest on balances that remain unpaid for long periods.

Potential benefits include:

  • Lower interest costs: Reducing an interest-bearing balance sooner may decrease the interest charged over the remaining repayment period.
  • Fewer ongoing commitments: Settling an account removes its future scheduled repayments, provided no balance or additional charges remain.
  • More room in your budget: Money previously used for repayments may become available for essential expenses or savings.
  • Improved financial organisation: Following a structured repayment plan can make it easier to monitor your progress.
  • Potential credit-history benefits: Consistently meeting your repayment obligations may support a healthier credit history over time, although improvements are not guaranteed.

Even a relatively small additional repayment can make a difference, depending on the interest rate, outstanding balance and terms of the credit agreement.

If you are also working on your credit profile, read our guide to checking and improving your credit score in South Africa.

Understanding Your Debt: The First Step to Repaying Faster

Before you tackle your debt, you need clarity. That means understanding exactly:

  • How much you owe
  • What interest rates you’re paying
  • Which accounts are costing you the most
  • How your monthly payments are structured

Different debt types affect your repayment plan differently:

Credit Card Debt

High interest + revolving balance = one of the biggest drains on South African households.

Personal Loans

Fixed repayment terms can make budgeting more predictable. Paying off a personal loan early may reduce interest costs, depending on the loan agreement and applicable charges.

Store Accounts & Buy-Now-Pay-Later

Store accounts and buy-now-pay-later arrangements can have different fee structures, repayment terms and interest charges. Check the full agreement to understand the costs of missing payments or carrying a balance.

Microloans & Short-term Loans

Short-term loans can carry relatively high borrowing costs. Prioritising them may reduce interest expenses, depending on their rates, fees and outstanding balances.

If these multiple debts are causing overwhelm, consider reading our explanation on how debt consolidation loans work in South Africa, which breaks down how to merge accounts into one manageable repayment.

How Interest Rates Affect Debt Repayment

Interest is one of the main reasons outstanding debt can become expensive over time. Generally, the longer an interest-bearing balance remains unpaid, the more interest may accumulate.

For example, a credit card charging a higher interest rate will usually be more expensive to carry than a comparable balance charging a lower rate, assuming similar fees and repayment terms.

Ways to manage interest costs include:

  • Paying more than the required minimum when affordable.
  • Prioritising higher-interest debts while keeping other repayments up to date.
  • Avoiding additional borrowing on revolving credit accounts.
  • Asking creditors whether alternative repayment arrangements are available.
  • Checking whether additional payments reduce the outstanding principal and how they affect the repayment schedule.

Before making additional repayments, check your credit agreement for applicable terms, fees and any early-settlement provisions.

If you have several outstanding debts, understanding the meaning of debt consolidation may also help you assess whether refinancing is worth considering.

How to Prepare Yourself to Repay Debt Faster

Debt freedom begins with a plan. Here’s how to set yourself up for success:

1️⃣ Assess Your Financial Situation

Start with:

  • A complete list of debts
  • Balances + interest rates
  • Monthly instalments
  • Income + essential expenses

This alone often provides the clarity people need to take action.

2️⃣ Create a Budget that Supports Faster Repayment

A realistic budget helps you:

  • Avoid overspending
  • Allocate more toward debt
  • Track progress monthly
  • Identify unnecessary expenses

Use budgeting tools like 22seven or a simple spreadsheet.

3️⃣ Build a Small Emergency Fund

Having some money set aside for unexpected expenses may help you avoid taking on additional debt while following your repayment plan.

Depending on your budget, even setting aside a small amount regularly can help you build an emergency buffer over time.

However, prioritise essential living expenses and required debt repayments before setting money aside. The amount you can realistically save will depend on your financial circumstances.

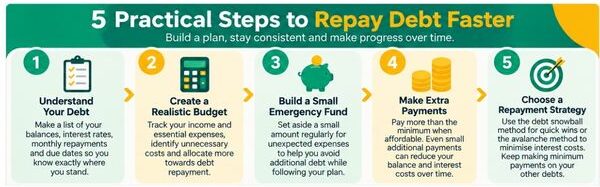
Five steps to repay debt faster in South Africa

Debt Repayment Strategies: Snowball vs Avalanche

Two commonly used approaches to repaying multiple debts are the debt snowball and debt avalanche methods.

With either method, the starting point is to keep up with the required repayments on your other accounts. Any affordable extra amount is then directed towards the debt you have chosen to prioritise.

The Debt Snowball Method

The debt snowball method focuses on repaying your smallest outstanding balance first, regardless of its interest rate.

  1. List your debts from the smallest balance to the largest.
  2. Continue making the required repayments on your other debts.
  3. Put any additional repayment money towards the smallest debt.
  4. Once that debt is settled, redirect the amount you were paying towards the next-smallest balance.

Example: If you owe R2,000 on a store account, R8,000 on a credit card and R20,000 on a personal loan, you would focus your extra repayments on the R2,000 balance first.

Best suited to: People who find motivation in clearing individual debts and seeing visible progress.

The Debt Avalanche Method

The debt avalanche method prioritises the debt with the highest interest rate rather than the smallest balance.

  1. List your debts from the highest interest rate to the lowest.
  2. Keep making the required repayments on your other accounts.
  3. Direct any affordable extra repayments towards the highest-interest debt.
  4. Once it is settled, move to the debt with the next-highest interest rate.

Example: If your credit card charges 24% interest, your store account charges 20% and your personal loan charges 15%, you would prioritise extra repayments towards the credit card first.

Best suited to: People whose main goal is to minimise interest costs over time.

Which Debt Repayment Method Is Better?

Feature Snowball Method Avalanche Method
First priority Smallest outstanding balance Highest interest rate
Main advantage Early progress and motivation Potentially lower total interest costs
Possible drawback May cost more in interest First debt may take longer to clear
Best for Motivation and consistency Reducing borrowing costs

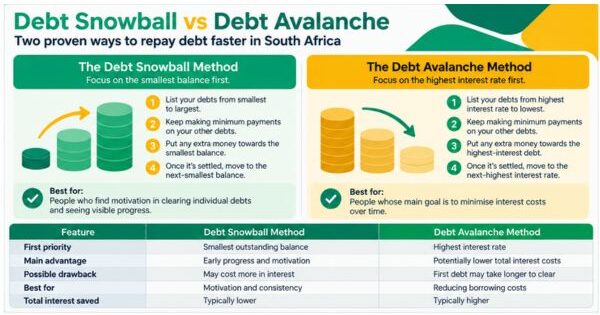
Debt snowball vs debt avalanche methods

Neither method guarantees a particular repayment timeline. Your results depend on your balances, interest rates, fees and how much you can afford to repay.

When Might Debt Consolidation Help?

If you have several existing debts, a consolidation loan may allow you to combine eligible balances into one repayment arrangement.

However, consolidation does not automatically reduce the amount you owe or help you become debt-free sooner. A longer repayment term may reduce your monthly instalment while increasing the total cost of borrowing.

Before refinancing, compare the new loan’s interest rate, fees, repayment period and total repayment amount against your existing debts.

You can explore debt consolidation loan options in South Africa through FatCat Loans, a loan comparison and matching service rather than a lender.

Common Mistakes That Slow Down Debt Repayment

Avoid these traps if you want to make real progress:

❌ Only paying the minimum instalment

Interest keeps growing.

❌ Opening new credit accounts

This creates a cycle that’s hard to break.

❌ Ignoring high-interest debts

They grow the fastest.

❌ Not budgeting

You can’t fix what you can’t see.

❌ Paying late

This adds fees and harms your credit score.

Compare debt consolidation options

Conclusion: Start With a Realistic Debt Repayment Plan

Repaying debt faster starts with understanding your balances, choosing a manageable strategy and keeping up with your existing repayment obligations.

The snowball and avalanche methods offer different ways to prioritise debts, while budgeting and affordable additional repayments can help you make progress over time.

If you cannot afford your current repayments, contact your creditors or seek guidance from an NCR-registered debt counsellor before considering further borrowing.

If refinancing is appropriate for your circumstances, FatCat Loans can help you explore available loan options. Approval and loan terms remain subject to the lender’s assessment.

Frequently Asked Questions About Repaying Debt Faster

What is the fastest way to pay off debt in South Africa?

There is no single fastest method for everyone. Prioritising higher-interest debts while maintaining other required repayments can help reduce interest costs. The best approach depends on your outstanding balances, interest rates, fees and available budget.

Which is better: the snowball or avalanche method?

The snowball method focuses on clearing smaller balances first and may help with motivation. The avalanche method targets higher-interest debts first and will generally minimise interest costs when other factors are equal.

Can making extra repayments reduce loan interest?

Potentially. Additional repayments may reduce your outstanding principal and future interest charges, depending on the loan agreement and how the lender applies payments. Check the applicable terms before making extra payments.

What should I do if I cannot afford my monthly debt repayments?

Contact your creditors as soon as possible to discuss available arrangements. If you are over-indebted, consider speaking to an NCR-registered debt counsellor. Taking out another loan may not be appropriate if your existing repayments are already unaffordable.

How long does it take to become debt-free?

There is no standard timeframe. The time needed depends on how much you owe, your interest rates, repayment obligations and how much you can realistically afford to pay each month.

Disclosure: This article is for general informational purposes and does not constitute personalised financial advice. FatCat Loans is a loan comparison and matching service, not a lender. Loan eligibility, approval, rates and terms are determined by the lender. Always review the full cost and conditions of any credit agreement before accepting an offer.

Secured Loan vs Unsecured Loan: Understanding the Difference

Understand the difference between secured loan vs unsecured loan. Explore our blog for insightful comparisons and key distinctions.

Secured vs Unsecured Loans: What’s the Difference?

Last Updated: October 2026

When applying for credit, it’s important to understand the key differences between a secured loan vs unsecured loan. These two types of loans determine how much you can borrow, the interest rates you’ll pay, and the level of risk involved.

Knowing the difference between a secured loan vs unsecured loan can help you make smarter financial decisions and choose the right option for your needs. In this guide, we’ll break down how each type works, their benefits, and which one may suit your financial goals best.

Key Differences Between Secured and Unsecured Loans

  • Collateral: Secured loans require an asset or other security, while unsecured loans generally do not.
  • Risk: With a secured loan, the asset provided as security may be at risk if you fail to meet the repayment obligations.
  • Interest rates: Rates vary by credit provider, loan type and applicant. Providing security may affect the terms offered.
  • Loan amounts: The amount available depends on the credit product, value of any security, affordability assessment and provider’s lending criteria.
  • Assessment: Credit providers may consider your income, expenses, existing debts, credit information and ability to afford the repayments for both secured and unsecured credit.

Apply for secured and unsecured loans

Exploring the Basics of a Secured Loan vs Unsecured Loan

Getting a loan can be a major decision in one’s financial journey. Whether you’re looking to buy a house, start a business, or consolidate your debts, understanding the difference between secured and unsecured loans is essential.

A secured loan vs unsecured loan comparison helps borrowers understand the two primary types of loans offered by lenders. A secured loan requires collateral — an asset such as a home, car, or other valuable property — that serves as security for the loan. In contrast, an unsecured loan does not require any collateral and is granted based on the borrower’s creditworthiness and ability to repay. Understanding the difference between a secured loan vs unsecured loan is essential when deciding which option suits your financial situation, credit history, and borrowing goals.

It’s important to understand the differences between secured and unsecured loans before making a borrowing decision. In this article, we will explore the basics of secured and unsecured loans, the role of collateral, the types of loans available, the advantages and disadvantages of each, and factors to consider when choosing between the two.

In-Depth Analysis of Secured Loans

A secured loan requires an asset or other form of security as part of the credit agreement. Depending on the type of loan, this could include property or a vehicle. The security reduces some of the credit provider’s risk, but the interest rate, loan amount and other terms still depend on the product, provider and applicant’s circumstances.

The main risk for the borrower is that failing to meet the obligations under a secured credit agreement could put the secured asset at risk.

Examples of Secured Credit

Secured credit can take different forms depending on the product and provider. Common examples include:

  • Home loans: The property provides security for the credit agreement.
  • Vehicle finance: The financed vehicle may provide security under the agreement.
  • Other asset-backed credit: Some credit products may allow an eligible asset to be used as security, subject to the provider’s requirements.

Always check exactly what asset secures the agreement and what could happen to that asset if you fail to meet your repayment obligations.

Comprehensive Guide to Unsecured Loans

When comparing a secured loan vs unsecured loan, the main advantage of an unsecured loan is flexibility — borrowers can access funds without needing any collateral. These loans are typically based on the borrower’s creditworthiness, income, and ability to repay. In a secured loan vs unsecured loan comparison, unsecured loans rely more heavily on credit history since no assets are tied to the borrowing. This makes them a popular choice for individuals who don’t own valuable property or prefer not to risk losing assets in case of default. Understanding how a secured loan vs unsecured loan differs helps borrowers decide whether flexibility or security is more important for their financial goals.

Varieties of Unsecured Loans Available

Unsecured loans come in various forms, each catering to specific borrowing needs. Here are some common types of unsecured loans:

  • Personal loan: A personal loan is a versatile form of unsecured loan that can be used for various purposes, such as debt consolidation, home improvements, or funding a wedding.
  • Student loans: These loans are specifically designed to help students finance their education. They are typically unsecured and require the borrower to make repayments after completing their education.
  • Unsecured personal loan: An unsecured personal loan is a general-purpose loan that does not require any collateral. Borrowers can use the funds for any purpose, from home renovations to medical expenses.

When considering an unsecured loan, it’s important to compare interest rates, repayment terms, and eligibility criteria to find the best option for your specific needs.

Advantages and Disadvantages of Unsecured Loans

Potential Advantages

  • No asset normally needs to be provided as collateral.
  • Personal loans may offer flexibility in how the funds can be used, subject to the agreement.
  • You do not put a specific asset at risk as security for the loan.

Potential Disadvantages

  • Interest rates and fees can vary considerably between providers and applicants.
  • Approval is subject to the credit provider’s lending criteria and affordability assessment.
  • Missing repayments can lead to additional costs, collection activity and negative information being reflected in your credit history.

Important Factors When Deciding on a Secured Loan vs Unsecured Loan

When deciding between secured and unsecured loans, several factors should be taken into consideration:

  • Interest rate

Compare the interest rates offered for both secured and unsecured loans. Rates vary depending on the credit product, provider and applicant, so consider the total cost of borrowing as well as the advertised interest rate.

  • Credit score

Your credit score plays a significant role in loan approval and interest rates. If you have a good credit score, you may have access to more favourable terms and lower interest rates.

  • Financial situation

Evaluate your financial situation, including your income, expenses, and existing debt. This will help determine your ability to repay the loan and manage the associated risks.

By considering these factors, you can make an informed decision about which type of loan is best suited to your needs.

How Loans Can Affect Your Credit History

Repayment behaviour on both secured and unsecured credit can form part of your credit history. Making agreed repayments on time can contribute to a positive repayment history, while missed payments or defaults may negatively affect your credit profile.

Your credit score is influenced by several factors, so taking out a new loan should not be viewed as a guaranteed way to improve your score. Borrow because the credit serves a genuine need and the repayments are affordable, rather than simply to try to build credit.

Secured Loans: Eligibility and Application Process

Secured loans have specific eligibility requirements and an application process that differs from unsecured loans. To apply for a secured loan, the borrower must provide relevant documentation and meet the following criteria:

  • Collateral: The borrower must have an asset to offer as collateral that meets the lender’s requirements. The lender will assess the value of the collateral and determine the loan amount based on its appraised value.
  • Creditworthiness: While secured loans are backed by collateral, lenders may still review the borrower’s credit history and credit score to assess their ability to repay the loan.
  • Financial stability: Lenders may also consider the borrower’s income, employment stability, and overall financial situation when evaluating a secured loan application.

Documents Required for a Secured Loan

To apply for a secured loan, you will need to go through an application process with a financial institution. The specific documents required may vary depending on the lender and the type of collateral you are offering. Generally, you will need to provide:

  • Proof of ownership of the valuable asset you are using as collateral, such as property documents or car ownership papers.
  • Financial documents to assess your ability to repay the loan, such as income statements, bank statements, and tax returns.
  • Appraisal or valuation of the collateral to determine its worth.

It is important to carefully review the application requirements and provide all requested documents to ensure a smooth loan approval process.

Understanding the Valuation of Collateral

When applying for a secured loan, the lender will need to assess the value of the collateral you are offering. This valuation is important because it determines the loan amount that can be granted. The lender will typically require an appraisal or valuation of the collateral, which may be carried out by a qualified professional. The valuation takes into account factors such as the condition, age, and market value of the asset. The lender wants to ensure that the collateral has sufficient value to cover the loan amount in case of default.

It is important to note that the valuation process may involve additional costs, which will be borne by the borrower. Understanding the valuation of collateral is crucial when applying for a secured loan, as it directly impacts the loan amount that can be obtained.

Navigating the World of Unsecured Loans

When it comes to unsecured loans, things work differently. These loans do not require any collateral and are typically based on the borrower’s credit score and credit history. The approval process for an unsecured loan is usually quicker, as there is no need for the lender to assess the value of collateral.

To qualify for an unsecured loan, lenders typically consider the following:

  • Credit score

A higher credit score indicates a lower risk for the lender, making it more likely for you to be approved for the loan.

  • Credit history

A strong credit history, including a record of timely payments and low credit utilization, also increases your chances of getting approved.

  • Income

Lenders may also assess your income to ensure that you have the financial means to repay the loan.

  • Other factors

Additionally, lenders may consider other factors such as employment history, debt-to-income ratio, and existing financial obligations.

It is important to maintain a good credit score and credit history to improve your chances of qualifying for an unsecured loan with favourable terms.

Before Applying for an Unsecured Loan

Before applying, review your financial situation and consider whether the repayments would remain affordable alongside your existing commitments.

You can also:

  • Check your credit report for information you believe is incorrect.
  • Review your income, expenses and existing debts.
  • Prepare the identification, income and banking documents requested by the credit provider.
  • Compare the interest rate, fees, repayment period and total cost of different offers.
  • Avoid borrowing more than you genuinely need.

Approval is not guaranteed and depends on the credit provider’s lending criteria and assessment of your circumstances.

Apply for a secured or unsecured loan up to R350,000

How Lenders Assess Risk in a Secured Loan vs Unsecured Loan

Credit providers assess risk differently depending on the type of credit and the applicant’s circumstances. With secured credit, an asset provides security under the agreement, while unsecured credit does not have the same form of collateral. Interest rates, loan amounts, eligibility requirements and other terms vary by credit product, provider and applicant.

How Lenders Evaluate Loan Applications

When evaluating loan applications, lenders consider various factors to assess the borrower’s creditworthiness. The key factors that lenders consider include:

  • Credit score, which is a numerical representation of their creditworthiness based on their credit history.
  • Financial situation, including their income, employment stability, and debt-to-income ratio.
  • Loan amount is another important consideration, as lenders want to ensure that the borrower can comfortably repay the loan.
  • Purpose of the loan, the borrower’s repayment history, and their existing financial obligations.

By evaluating these factors, lenders can determine the risk associated with the loan and make informed decisions about loan approvals and interest rates.

The Importance of Credit History in Loan Approval

Credit history plays a crucial role in loan approval. Lenders review a borrower’s credit history to assess their creditworthiness and determine the risk involved in granting a loan. A good credit history, with a record of timely payments and responsible credit use, demonstrates that the borrower is likely to repay the loan on time. This increases the borrower’s chances of loan approval and may result in more favourable terms, such as lower interest rates. On the other hand, a poor credit history, with missed payments or a high level of debt, indicates a higher risk for lenders, leading to potential loan rejections or higher interest rates. It is important to maintain a good credit history by paying bills on time, keeping credit utilization low, and addressing any credit issues promptly.

Conclusion

Understanding the difference between a secured loan vs unsecured loan is crucial for making informed financial decisions. In a secured loan vs unsecured loan comparison, secured loans typically offer lower interest rates because they are backed by collateral, while unsecured loans rely on the borrower’s creditworthiness. When choosing between the two, consider key factors such as interest rates, collateral requirements, and credit impact. Knowing the eligibility criteria and application process for each type of loan will help you make the best choice. By evaluating a secured loan vs unsecured loan carefully, you can prioritize financial stability and select the option that aligns with your long-term goals for a secure financial future.

Frequently Asked Questions About a Secure Loan vs Unsecure Loan

Secured Loan vs Unsecured Loan: Can I Convert an Unsecured Loan into a Secured Loan?

No, you cannot convert an unsecured loan into a secured loan. A secured loan requires collateral from the borrower, while an unsecured loan does not. If you need a secured loan, you will need to apply for a new loan with collateral.

What happens if I default on a secured loan?

If you default on a secured loan, the lender has the right to seize the collateral used to secure the loan. They can sell the collateral to recover the outstanding balance. Defaulting on a secured loan can also have a negative impact on your credit score.

Are there unsecured loans with no credit check?

Some credit providers may place less emphasis on a traditional credit score, but affordability and other checks still apply. A provider may also access credit information as part of its assessment. Learn more about how no credit check loans are assessed in South Africa.

How a Secured Loan vs Unsecured Loan Affects Your Credit Score

Repayment behaviour on both secured and unsecured loans can form part of your credit history. Making agreed repayments on time can contribute to a positive repayment history, while missed payments or defaults may negatively affect your credit profile. The effect on your credit score depends on several factors and is not determined simply by whether the loan is secured or unsecured.

Ultimate Guide to Online Loans Cape Town

Find the ultimate guide to online loans Cape Town. Get the information you need for quick and easy access to online loans in Cape Town.

How Online Loans Work in Cape Town

Last Updated: October 2026

Residents of Cape Town can apply for loans in Cape Town online without visiting a physical branch. Whether you need to cover an unexpected expense or another personal cost, eligibility, loan amounts, repayment terms and costs depend on the credit provider and your financial circumstances. This guide explains how online loans work, what lenders may consider and how to apply safely.

This guide will walk you through everything you need to know — from choosing a trusted lender to submitting your application safely and efficiently.

Key Facts About Online Loans in Cape Town

  • Online loans allow you to submit an application using a computer or smartphone without visiting a physical branch.
  • Eligibility and affordability requirements vary between credit providers.
  • Credit providers may assess your income, expenses, existing debts and credit information before making a decision.
  • Interest rates, fees, loan amounts and repayment periods vary by product and provider.
  • Always review the credit agreement and total cost before accepting an offer.

Understanding Online Loans in Cape Town

Online loans in Cape Town allow borrowers to complete some or all of the application process online. The credit provider will assess the application according to its lending criteria and affordability requirements before deciding whether to offer credit.

This guide covers eligibility, the application process, costs and important factors to consider when comparing online loan options.

The Basics of Online Lending

Online lending allows you to apply for credit through a website or other digital platform. Depending on the credit product, you may be asked for personal, income, banking and other financial information. The credit provider then assesses the application and, if approved, provides the applicable loan amount, interest rate, fees and repayment terms.

Benefits of Applying for a Loan Online

The main benefit of online lending is convenience. Applications can generally be submitted without visiting a physical branch, and documents may be provided electronically. You can also compare different credit options online before deciding whether borrowing is appropriate for your circumstances.

Common Requirements for Online Loans Cape Town Approval

Eligibility requirements vary between credit providers. Providers must comply with applicable requirements under the National Credit Act, including assessing affordability before granting credit. Depending on the lender and product, the following information may form part of the assessment:

  • Accurate personal information: This includes their name, contact details, and identification documents. This information is necessary for lenders to verify the borrower’s identity and assess their creditworthiness.
  • Valid bank account in South Africa: This allows lenders to deposit the loan amount directly into the borrower’s account and set up automatic repayments.
  • Credit information: Credit providers may consider information in your credit profile alongside factors such as income, expenses, existing debts and affordability.
  • Affordability: Affordability is determined by the borrower’s income and expenses, ensuring they can comfortably repay the loan without financial strain.

Meeting a credit provider’s basic requirements does not guarantee approval. The provider will assess the application according to its lending criteria and the applicant’s individual circumstances.

How Credit Information May Affect Loan Eligibility

Credit providers may consider information from your credit profile when assessing an online loan application. However, there is no single credit score that guarantees approval or determines the terms you will receive.

A lender may consider several factors, including your income, expenses, existing debts, repayment history, credit information and overall affordability. Requirements and assessment methods vary between providers.

If you have a weaker credit profile, you can learn more about bad credit loan options and the factors lenders may consider.

How to Apply for Online Loans Cape Town

Applying for an online loan in Cape Town is a simple and convenient process. Online lenders offer an easy-to-use online application platform, making it quick and hassle-free to apply for a loan.

To start the application process with online loans Cape Town, borrowers need to visit the lender’s website and navigate to the loan application page. Here, they will be prompted to provide personal and financial information, such as their name, contact details, employment information, and income details. It is important to provide accurate and complete information to ensure a smooth application process.

Once the application is submitted, the credit provider will assess the information provided and may request additional documents or verification.

If the application is approved, you should receive a loan agreement or other pre-agreement information setting out the applicable loan amount, interest rate, fees, repayment period and other terms. Review these carefully and make sure you understand the total cost and repayment obligations before accepting an offer.

Approval and payout times vary between credit providers and can also depend on verification requirements, the time of application and banking processes.

Documents Needed for Loan Application

When applying for an online loan in Cape Town, borrowers will need to provide certain documents as part of the application process. These documents help lenders verify the borrower’s identity, income, and financial standing. Here are some documents that may be needed for an online loan application:

  • Bank statements: Lenders may require the borrower to provide their latest bank statements as proof of income and to verify their financial stability. These provide a snapshot of the borrower’s financial transactions and help lenders assess the borrower’s ability to repay the loan./
  • Accurate personal information: This can include their name, contact details, and identification documents. This information is necessary for lenders to verify the borrower’s identity and ensure that the loan is being provided to the correct person.
  • Phone number: Borrowers may be asked to provide a phone number that can be used for communication purposes throughout the loan application process. This allows lenders to reach out to the borrower if any additional information is needed or to provide updates on the loan application status.

Having the requested information and documents available can help you complete the application process and respond to any verification requests from the credit provider.

Choosing the Right Lender in Cape Town

Choosing the right lender is crucial when applying for online loans Cape Town. Here are some key factors to consider when choosing an online lender:

  • Work with a registered credit provider that adheres to responsible lending practices and is regulated by the National Credit Regulator. Registered credit providers are required to follow industry standards and guidelines, ensuring that borrowers are protected from predatory lending practices. They are also subject to scrutiny and oversight by the National Credit Regulator, providing an added layer of security for borrowers.
  • Consider the security measures implemented by the lender. Online lenders should have secure encryption protocols in place to protect borrowers’ personal and financial information. This includes secure transmission of data and storage of information on secure servers. Look for secure payment gateways and SSL certificates.
  • Read reviews and testimonials from other borrowers to gauge the lender’s reputation and customer service. A lender with positive reviews and satisfied customers is more likely to provide a reliable and trustworthy lending experience.
  • Review the loan terms and conditions carefully. This includes interest rates, repayment terms, and any additional fees or charges. Understanding the loan terms ensures that borrowers are fully aware of their financial obligations and can make an informed decision.

By being cautious and doing your due diligence, borrowers can have peace of mind knowing that their personal and financial information is secure, and they are working with a reputable and responsible credit provider.

Online loans Cape Town with FatCat Loans

Interest Rates and Fees

Understanding the interest rates and fees associated with online loans in Cape Town is crucial when making borrowing decisions. Here’s what you need to know:

Interest Rates

Interest rates on online loans can vary depending on the lender and your credit profile. That’s why it’s worth comparing offers from different lenders before you apply.

To get a better idea of what you may repay each month, try our loan  repayment calculator. It can help you estimate repayments based on your loan amount, interest rate, and repayment term.

Additional Fees

  • In addition to interest rates, some online loans may include extra costs such as application fees, initiation fees, or late payment penalties.
  • Always review the loan agreement carefully so you understand the full cost of borrowing before accepting a loan offer.
  • By considering both the interest rate and any additional fees, you can make a more informed decision and choose an online loan in Cape Town that fits your budget and financial needs.

Effective Tips for Managing Your Loan Repayment

Managing your loan repayment is crucial to avoid any financial strain. Here are some tips to effectively manage your online loan in Cape Town:

  • Create a budget that includes your loan repayments. This will help you allocate funds and ensure timely repayments without compromising other financial commitments.
  • Make sure your agreed repayment amount and schedule fit within your budget before accepting the loan.
  • Set up automatic payments or reminders to avoid missing any repayments. This will help you stay on track and avoid late payment fees.
  • If you encounter financial difficulties, contact your lender early. They may be able to offer temporary relief options or work out a revised repayment plan.

By following these tips, you can effectively manage your online loan repayment and maintain a healthy financial standing.

What Happens if You Miss a Payment?

Missing a repayment can have financial consequences. Depending on your credit agreement and circumstances, these may include additional permitted charges, collection activity and negative information being reflected in your credit history.

If you think you may struggle to make a repayment, contact the credit provider as early as possible. Ask what options may be available and make sure you understand any changes to your repayment obligations.

Conclusion

In conclusion, understanding the landscape of online loans in Cape Town is crucial for making informed financial decisions. From grasping the basics of online lending to choosing the right lender and managing repayment effectively, this ultimate guide equips you with the necessary knowledge. Be mindful of interest rates, eligibility criteria, and repayment strategies to navigate the online loan market successfully. By staying informed and proactive, you can make the most of online loans while safeguarding your financial well-being. Make wise choices, and secure your financial future with confidence.

Frequently Asked Questions About Online Loans in Cape Town

Can I apply for an online loan if I live in Cape Town?

Yes. Many credit providers allow South African residents, including people living in Cape Town, to complete their loan application online. Eligibility depends on the provider’s lending criteria, affordability assessment and your individual circumstances.

Do I need to visit a branch to apply for an online loan in Cape Town?

Not necessarily. Many online loan applications can be completed digitally, although the process varies between credit providers. You may need to provide identification, income, banking or other information so the provider can verify your details and assess your application.

How quickly can I get an online loan in Cape Town?

Approval and payout times vary between credit providers. Timing can depend on factors such as document verification, affordability checks, the time you apply and banking processes. Be cautious of providers that guarantee approval or promise a specific payout time without assessing your application.

Can I get an online loan in Cape Town with bad credit?

Some credit providers may consider applicants with weaker credit profiles, but approval is not guaranteed. Providers may consider your income, expenses, existing debts, credit information and ability to afford the repayments. Learn more about bad credit loans in South Africa.

How can I check whether an online lender is legitimate?

Check that the credit provider is registered with the National Credit Regulator (NCR) and verify its details before providing personal or banking information. Be cautious of anyone promising guaranteed approval, asking for suspicious upfront payments or requesting sensitive information such as your banking PIN or password.

Are online loans in Cape Town different from online loans elsewhere in South Africa?

Online loans available to Cape Town residents generally operate under the same South African credit laws as online loans elsewhere in the country. The products, eligibility requirements, costs and lending criteria depend on the individual credit provider rather than simply where you live.

How To Get A Loan with Bank Statement Only

Searching for a quick personal loan with bank statement only? Get the funds you need without hassle. Learn more on our blog!

Understanding Personal Loans with Bank Statement Only

Last Updated: October 2026

If you don’t receive traditional payslips, you may wonder whether you can apply for a personal loan using bank statements to show your income. Some credit providers may accept bank statements as part of their income and affordability verification, particularly where income is irregular or comes from self-employment.

However, a bank statement does not necessarily replace every other application requirement. Credit providers may also request identification, income information or other supporting documents and may access credit information when assessing an application.

If you have limited traditional credit information, you can also learn more about how no credit check loans are assessed in South Africa. These do not mean that affordability and other checks are skipped.

Key Things to Know About Applying With Bank Statements

  • Bank statements may help a credit provider verify income and assess your financial circumstances.
  • Application and documentation requirements vary between credit providers.
  • You may still need to provide identification and other information requested by the provider.
  • The credit provider must assess affordability before granting credit.
  • Approval, loan amounts, interest rates, fees and repayment terms depend on the provider, product and applicant’s circumstances.

Eligibility When Applying With Bank Statements

Eligibility requirements vary between credit providers and credit products. When assessing an application, a provider may consider information such as:

  • Your identity and personal information.
  • Your income and how regularly it is received.
  • Your expenses and existing financial obligations.
  • Information shown in your bank statements.
  • Your credit information and repayment history.
  • Whether the proposed repayments appear affordable.

Providing the requested information does not guarantee approval. The credit provider will assess the application according to its lending criteria and your individual circumstances.

Applying for a Personal Loan Using Your Bank Statements

The exact application process varies between credit providers, but it may include the following steps:

  • Compare your options: Compare lenders, interest rates, fees, repayment periods and eligibility requirements before applying.
  • Prepare your information: Have recent bank statements and any other identification, income or financial information requested by the provider available.
  • Complete the application: Provide accurate personal and financial information.
  • Submit the requested documents: The provider may use bank statements and other information to assess income, expenses and affordability.
  • Wait for the assessment: The credit provider will assess your application and may request additional information or verification.
  • Review any offer: If approved, carefully review the interest rate, fees, repayment period, total cost and other terms before accepting the credit agreement.

Approval and payout times vary between credit providers and may also depend on verification requirements and banking processes.

Documents Required Besides Bank Statements

In addition to bank statements, lenders may require borrowers to provide other documents as part of the loan application process. These documents help lenders assess the borrower’s financial situation and determine their eligibility for the loan. Some additional documents that may be required include:

  • Salary slip: If the borrower has a payslip, it may be requested as supplementary proof of income.
  • Personal information: Identification documents such as an ID card or passport may be required to verify the borrower’s identity.
  • Credit history: Lenders may request access to the borrower’s credit history to assess their creditworthiness and repayment behaviour.

Why Bank Statements May Be Useful When Applying

Bank statements can provide a credit provider with information about money entering and leaving your account. This may be particularly useful if your income is irregular, you are self-employed or you do not receive a traditional monthly payslip.

However, accepting bank statements as part of an application does not mean that normal lending criteria or affordability requirements are removed.

If you’re considering an unsecured personal loan, you can learn more about how personal loans work and what providers may consider when assessing an application.

What to Consider Before Applying

Using bank statements as part of an application does not tell you whether a loan will be affordable or competitively priced. Before accepting an offer, compare the interest rate, fees, repayment period, monthly repayment and total cost of credit.

Only borrow an amount you can reasonably afford to repay alongside your existing expenses and financial commitments. If one option is unsuitable, you can explore other loan options before deciding whether to borrow.

Compare loan offers online with FatCat Loans South Africa.

Comparing Lenders for the Best Deal

When considering a personal loan, compare different credit options rather than focusing only on whether bank statements are accepted. Interest rates, fees, repayment periods and eligibility requirements can vary between providers. Here are some important factors to consider:

  • Check if the lender charges any service fees or other permitted charges. These can increase the overall cost of the loan.
  • Review the loan terms, including the interest rate and repayment period. Make sure the repayments fit within your budget.
  • Check that the credit provider is registered with the National Credit Regulator (NCR) and verify its registration details.
  • Consider consulting a financial advisor who can provide guidance and help you make informed decisions about your loan options. They can also assist with budgeting and managing your repayments.

When seeking a personal loan with bank statement only, it is important to be aware of predatory lenders. These are lenders who may take advantage of borrowers in vulnerable financial situations. They may charge exorbitant interest rates, have unfair loan terms, or use aggressive collection practices.

Taking the time to choose a reputable lender can provide peace of mind and increase your chances of a positive loan experience.

Navigating Through Your Loan Approval

After submitting your application, the credit provider will review the information provided, which may include your bank statements, income information, expenses, existing financial obligations and credit information. The provider may also request additional documents or verification before making a decision.

If your application is approved, carefully review the interest rate, fees, repayment schedule, total cost and other terms before accepting the offer. Payout timing varies between credit providers and may depend on verification requirements and banking processes.

Managing Your Loan Repayments Effectively

During the loan term, you will be required to make regular repayments as per the agreed schedule. Missing or late payments can have negative consequences, such as late fees or a negative impact on your credit score. Managing your loan repayments effectively is crucial to ensure you meet your financial obligations and maintain a good credit score. Here are some tips to help you manage your loan repayments:

  • Create a budget: Evaluate your income and expenses to create a budget that allows you to meet your loan repayments. Prioritise your loan payments to ensure they are paid on time.
  • Set up automatic payments: Consider setting up automatic payments from your bank account to ensure your loan repayments are made on time. This can help you avoid late fees and maintain a positive credit history.
  • Communicate with your lender: If you are facing financial difficulties and are unable to make your loan repayments, reach out to your lender. They may be able to offer temporary solutions or alternative repayment plans.
  • Seek financial advice: If you are struggling to manage your loan repayments, consider seeking advice from a financial advisor. They can help you develop a repayment plan and provide guidance on managing your finances effectively.

Alternatives to Consider

If a credit provider cannot assess your application using the documentation you have available, ask what other forms of income verification it accepts or consider comparing other suitable credit options.

You can also learn about the differences between secured and unsecured loans before deciding which type of borrowing may be appropriate for your circumstances.

Whatever type of credit you consider, check the eligibility requirements, total cost and repayment obligations before applying.

Conclusion

Bank statements can be useful when applying for a personal loan, particularly if you do not receive traditional payslips or your income varies from month to month. However, providing bank statements does not mean that affordability, identity, credit or other checks will be skipped.

Requirements vary between credit providers, so compare loan options carefully and review the interest rate, fees, repayment period and total cost before accepting an offer.

Frequently Asked Questions About Applying for a Loan With Bank Statements

Can I get a personal loan using my bank statements?

Some credit providers may accept bank statements as part of the income and affordability verification process. However, you may also need to provide identification and other information or documents requested by the provider.

Can I get a loan without a payslip in South Africa?

Potentially. Requirements vary between credit providers, and some may accept alternative ways of verifying income. A payslip is not necessarily the only information a provider can use, but you will still need to meet its eligibility and affordability requirements.

How many months of bank statements do I need for a loan?

The number of bank statements required varies between credit providers and products. Check the provider’s application requirements rather than assuming that a particular number of months will always be sufficient.

Does providing bank statements guarantee loan approval?

No. Bank statements may form part of the assessment, but approval depends on the credit provider’s lending criteria, affordability assessment and your individual circumstances.

How quickly can a loan using bank statements be approved?

Approval times vary between credit providers. Timing can depend on the information and documents required, verification checks and the complexity of the application. Be cautious of anyone promising guaranteed approval.

Borrowing Money from Family: FAQs & Tips

Get answers to your FAQs on borrowing money from family to buy a house. Find out everything you need to know on our blog.

Borrowing Money from Family in South Africa: What You Need to Know

Updated March 2026

Borrowing money from family can feel like the easiest solution when you’re under financial pressure. Whether you’re covering unexpected expenses, consolidating debt, or funding a big purchase, family loans often come with fewer barriers than traditional lenders.

But here’s the reality: borrowing from family is still a financial agreement — not just a favour.

Without proper structure, it can damage relationships and create long-term tension.

In this guide, we’ll break down:

  • When borrowing from family makes sense
  • How to structure a proper agreement
  • Legal considerations in South Africa
  • Safer alternatives if things go wrong

This article is for general information only and should not be taken as legal, tax, or financial advice.

Compare your loan options with FatCat Loans.


Key Takeaways

  • Family loans can offer lower interest rates and flexible repayment terms
  • You should always use a written loan agreement
  • Even informal loans should follow basic legal and financial principles
  • Clear communication is essential to avoid damaging relationships
  • Always consider whether you can realistically repay the loan

Is It a Good Idea to Borrow Money from Family?

It can be—but only in the right situation.

When it makes sense:

  • You have a clear repayment plan
  • You want to avoid high-interest debt
  • Your credit score limits traditional borrowing options

If your credit is low, you may also want to explore bad credit loan options before involving family.

When it’s risky:

  • You’re already struggling with repayments
  • There’s no formal agreement
  • Expectations aren’t clearly discussed

Bottom line: If it’s not structured properly, it can cost more than money—it can cost relationships.


How Family Loans Work

A family loan is simply a loan between relatives, but it should still be treated like a formal financial agreement.

In practice, that usually means having:

  • Written contract
  • Defined repayment terms
  • Agreed interest rate (if applicable)

Even between family, this protects both sides.


Legal Considerations in South Africa

Depending on how the loan is structured, whether interest is charged, and whether lending is done regularly, some family loan arrangements may raise legal or regulatory considerations in South Africa.

Key things to consider:

  • A written agreement helps enforce repayment
  • Charging excessive interest could raise compliance issues
  • Large loans may have tax implications (SARS)

If you’re unsure, it’s worth getting basic legal advice—especially for large amounts.


How to Set Up a Family Loan Agreement

A proper agreement removes confusion and protects your relationship.

Include these key terms:

  • Loan amount:  Total borrowed
  • Repayment plan:  Monthly amount + duration
  • Interest rate:  If applicable
  • Missed payment terms:  What happens if you fall behind
  • Signatures:  Both parties should sign

See what a loan agreement should include


What Is a Fair Interest Rate?

Even with family loans, setting a fair interest rate can avoid future conflict.

You can base it on:

  • Current market rates
  • Your credit profile
  • The risk to the lender

See how different personal loan rates compare.

Some families choose 0% interest, but even then, repayment expectations should be clear.


How to Talk to Family About Borrowing Money

This is where most people go wrong.

Do:

  • Be honest about your financial situation
  • Explain how you’ll repay the loan
  • Put everything in writing

Don’t:

  • Assume they’ll say yes
  • Avoid difficult conversations
  • Treat it casually

Clear communication prevents resentment later.


Managing Repayments Without Damaging Relationships

Once the loan is in place, discipline matters.

Best practices:

  • Set up automatic payments
  • Track your progress
  • Communicate early if issues arise

If you’re struggling to keep up with repayments, it’s important to act early. Missing payments can lead to financial stress and strain your relationship with your family member.

Reviewing your finances and following a structured repayment strategy can help you avoid falling further behind.

Learn practical ways to repay debt faster.


What If You Can’t Repay?

Don’t ignore it.

Instead:

  • Speak to your family member immediately
  • Renegotiate terms if needed
  • Show accountability

Silence is what damages trust—not the problem itself.


Pros and Cons of Borrowing from Family

Pros:

  • Lower or no interest
  • Flexible terms
  • Faster access to money

Cons:

  • Emotional pressure
  • Risk to relationships
  • Lack of legal protection if informal

Alternatives to Borrowing from Family

Before committing, consider:

These options may protect your relationships while still meeting your financial needs.

Compare your loan options with FatCat Loans.


FAQs: Borrowing Money from Family in South Africa

1. Is it legal to borrow money from family in South Africa?

Yes, borrowing money from family is legal in South Africa. However, if interest is charged or lending becomes frequent, the agreement may fall under the National Credit Act (NCA). It’s always recommended to have a written agreement to protect both parties.


2. Do I need a contract when borrowing money from family?

Yes. Even if it feels informal, a written loan agreement helps prevent misunderstandings. It should clearly outline the loan amount, repayment terms, and any interest charged.


3. Can a family loan affect my credit score?

No, most family loans are not reported to credit bureaus, so they won’t directly impact your credit score. However, failing to repay could harm your financial reputation and relationships.


4. Should you charge interest on a family loan?

It depends. Some families choose not to charge interest, while others set a fair rate based on market conditions. Charging interest can make the agreement feel more formal and balanced.


5. What is a fair interest rate for a family loan in South Africa?

A fair interest rate is usually lower than what banks charge, but still reasonable enough to compensate the lender. Comparing rates across available loan options can help guide your decision.


6. What happens if I can’t repay a family loan?

If you can’t make a payment, communicate immediately. You may be able to renegotiate the repayment plan. Ignoring the issue can damage trust and strain your relationship.


7. Can SARS tax a family loan?

In some cases, yes. If a loan is interest-free or below market rates, SARS may view part of it as a donation, which could have tax implications. It’s best to get professional advice for large amounts.


8. What are the risks of borrowing money from family?

The biggest risks are:

  • Damaging relationships
  • Misaligned expectations
  • Lack of formal legal protection

That’s why clear agreements and communication are essential.


9. Is borrowing from family better than a personal loan?

It can be, especially if you get better terms. However, personal loans can offer more structure, clearer terms, and formal application processes.

Explore personal loan options.


10. How do I ask a family member for a loan?

Be honest and respectful. Clearly explain:

  • Why you need the money
  • How much you need
  • How you plan to repay it

Treat it like a formal financial request—not just a favour.


11. What should be included in a family loan agreement?

A proper agreement should include:

  • Loan amount
  • Repayment schedule
  • Interest rate (if any)
  • Consequences for missed payments
  • Signatures from both parties

12. Are there alternatives to borrowing from family?

Yes, alternatives include:

  • Personal loans
  • Credit unions
  • Peer-to-peer lending

These options can reduce the risk of damaging personal relationships.


Final Thoughts

Borrowing money from family isn’t just a financial decision—it’s a personal one.

Handled correctly, it can strengthen trust.
Handled poorly, it can create lasting tension.

Treat it like a real loan:

  • Put it in writing
  • Communicate clearly
  • Stick to your commitments

That’s how you protect both your finances—and your relationships.

Not sure borrowing from family is the right move? A personal loan may offer more structure, clearer terms, and less pressure on your personal relationships.

Apply online to see what loan options may be available to you.

Average Credit Score South Africa: What It Means

The average credit score in South Africa is best understood as a benchmark rather than a fixed number, because scores can differ between credit bureaus and scoring models. This guide explains what “average” typically means, how it compares to fair and good ranges, and how it may affect loan approval and interest rates.

What Is the Average Credit Score in South Africa?

Updated April 2026

Many South Africans search for the “average credit score” to understand where they stand.

Unlike some countries, South Africa doesn’t have one official average score. This is because different credit bureaus use slightly different scoring models.

The best way to understand your position is to compare your score against standard ranges and lender expectations.

In this guide, we explain what “average” usually means in South Africa, how it compares to a good or excellent score, and what an average score could mean for loan approval and interest rates.

If you’re unsure where you fall, start by checking your credit report and score before comparing to the average.


Key Facts About the Average Credit Score in South Africa

  • There isn’t one universally published “average credit score” in South Africa because scores can vary by bureau and scoring model.
  • Most lenders interpret an “average” score as falling in the fair range, often around 610–660.
  • Your credit score affects both approval odds and the interest rate margin you may be offered (prime + / prime -).
  • Credit scores can differ between credit bureaus because lenders don’t always report to every bureau and updates can happen at different times.
  • Before comparing yourself to the average, check your credit report for errors or outdated listings that could lower your score.

Credit Score Ranges in South Africa (Quick Guide)

Credit score ranges vary slightly by bureau, but most South African scoring models use a scale up to 999. Here’s how most lenders interpret those ranges in practice:

Score range General meaning
800+ Excellent (lower risk)
661–780 Good
610–660 Fair / average range
500–609 Poor
Below 500 Very poor

If you want a detailed breakdown of what lenders consider “good” and “excellent,” read our guide to what counts as a good credit score in South Africa.


How Credit Bureaus Calculate Your Credit Score

Your credit score is calculated by registered credit bureaus based on the information contained in your credit record. These credit bureaus track your credit history and how you manage accounts such as credit cards, personal loans, retail accounts, and other credit agreements.

Each of the major credit bureaus builds a picture of your credit profile using factors like payment history, outstanding balances, and how often you apply for credit. If you miss repayments or carry very high balances, it may result in a poor credit score.

Because lenders may report to different credit bureaus, your score can vary slightly between them. This is why checking your full credit record can help you understand how lenders assess your financial behaviour.

In South Africa, credit bureaus operate under regulations from the National Credit Regulator (NCR), which oversees responsible lending and credit reporting practices.

Get free credit report


Why “Average” Matters More Than Most People Think

An average credit score doesn’t automatically mean your loan will be approved. Lenders usually consider your score alongside affordability, income stability, and your current debt commitments. A fair or average score can still qualify for credit — but you may receive higher pricing (prime +) compared to someone with an excellent score (prime -).

In simple terms: your score affects both your approval chances and the interest rate you’re offered.


How Lenders Interpret an Average Credit Score

An average credit score doesn’t automatically mean rejection. Many lenders will still consider your application, but they may apply stricter affordability checks or offer higher interest rates.

Lenders typically look beyond your score and review your full credit report, including your repayment behaviour, existing debt, and income stability. This means two people with the same score can receive very different loan offers.

Understanding how lenders interpret your score can help you prepare before applying and improve your chances of approval.


What an Average Credit Score Means for Different Types of Credit

An average credit score doesn’t affect all types of credit in the same way. Different lenders assess risk differently depending on the product you’re applying for.

Personal loans

With an average credit score, you may still qualify for personal loans, but lenders may apply stricter affordability checks. Interest rates may also be higher compared to borrowers with stronger credit profiles.

Credit cards and retail accounts

For revolving credit like credit cards, lenders often look closely at your credit history and how you manage your credit limit. An average score may still be approved, but with lower limits or higher rates.

Home loans and vehicle finance

For larger credit products like home loans or car finance, an average credit score may reduce your approval chances or require stronger supporting factors such as stable income and lower debt levels.

Because each lender uses its own criteria, your full credit report — not just your score — plays a key role in the final decision.


Check Your Credit Report Before You Compare Yourself to the Average

Before you interpret your score against the South African average, make sure your credit report is accurate. Incorrect listings, outdated balances, or accounts that aren’t yours can affect your score and your approval chances. Your credit report gives a full breakdown of the accounts and activity used to calculate your score.

To check your report properly, follow our step-by-step guide on how to check your credit score in South Africa.


How to Improve an Average Credit Score

If your score is below the fair or average range, focus on improving your credit behaviour and keeping your repayments manageable before applying for major credit products.

Start with these practical steps:

  • Pay at least the minimum instalment on every account by the due date to protect your payment history.
  • Reduce revolving credit utilisation and avoid using most of your available credit limit.
  • Keep your monthly debt repayments manageable relative to your income.
  • Avoid applying for multiple loans or credit cards within a short period.
  • Check your credit record for errors and dispute incorrect listings with credit bureaus.

Small improvements over time can help strengthen your credit profile and improve your chances of approval.

For a full step-by-step plan, read Improve Credit Score South Africa: Practical Steps That Work


Quick Mistakes That Keep Scores Below Average

  • Missing even one repayment date
  • Using most of your credit limit consistently
  • Applying for several new credit lines within a short period

For deeper fixes, follow our full guide to improving your credit score.


The Impact of Your Credit Score on Financial Opportunities

Your credit score plays a crucial role in determining your financial opportunities.

When you apply for a loan, lenders assess your credit profile to evaluate your creditworthiness.

A higher score can increase your chances of approval and may qualify you for lower interest rates. On the other hand, a lower credit score can make it more difficult to secure a loan and may result in higher interest rates. It’s important to be proactive in managing your credit score to ensure you have the best chance of accessing favourable financial opportunities.

Find out about the average Credit Score in South Africa with FatCat Loans.


Does the “Average” Credit Score Change Over Time?

Yes. Credit behaviour across South Africa can shift over time due to economic conditions, lending trends, and changes in how credit bureaus calculate scores. This means what is considered “average” today may not be the same in a few years.


Conclusion: Use the Average Score as a Benchmark — Not a Label

The average credit score serves as a benchmark that helps you understand how lenders may view your overall risk profile. If your score falls within the fair/average range, you may still qualify for credit — but your interest rate could be higher than someone with a good or excellent profile.

The best next step is to confirm your credit report is accurate, understand what your score range means, and improve affordability before applying for major credit products.


Frequently Asked Questions: Average Credit Score South Africa

What is the average credit score in South Africa?

There isn’t one universally published national “average” because credit scores differ by bureau and scoring model. Most lenders interpret an average score as falling in the fair range (around 610–660).

Is 610 a good credit score in South Africa?

A score of 610 is often treated as the lower end of “fair” and may qualify for credit, but better terms are typically offered to higher scores.

Can I get a loan with an average credit score?

Yes, but approval depends on affordability, income stability, current debt levels, and the lender’s risk rules.

Why does my credit score differ between bureaus?

Not all lenders report to every bureau, and bureaus may update at different times or use different scoring models.

What should I do if my score is below average?

Check your report for errors, reduce credit utilisation, pay on time, and avoid repeated applications. Use a structured improvement plan before applying again.

Disclosure:  This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

What Is a Good Credit Score in South Africa?

Learn about what’s a good credit score in South Africa and how to improve yours for better financial opportunities. Visit our blog for insights.

What’s a Good Credit Score in South Africa?

Updated April 2026

Quick Answer: Credit Score Ranges in South Africa

In South Africa, a good credit score generally starts at 681+ (on the common 0–999 scale). If your score is in the excellent credit scores range (typically 767–999), you’ll usually qualify more easily and may receive better interest rates.

  • Poor credit score: 0–527 (higher risk)
  • Below average: 528–600
  • Fair: 601–680
  • Good: 681–766
  • Excellent: 767–999

Many South Africans often ask, “What’s a good credit score in South Africa?” — and what counts as a strong score when applying for credit. Your credit score plays a crucial role in determining whether you qualify for loans, credit cards, and even rental agreements.

A good credit score opens the door to financial opportunities.

It can help you:

  • Secure lower interest rates
  • Get approved faster
  • Access better loan terms

On the other hand, a poor score can limit your options or lead to higher borrowing costs.

In this comprehensive guide, we’ll explore what defines a good credit score in South Africa, how it’s calculated, what influences it, and what you can do to improve it.

Free credit report apply button


What Is a Credit Score and How Does It Work in South Africa?

Your credit score is a three-digit number that reflects your creditworthiness and financial behaviour. In South Africa, it typically ranges from 0 to 999. The higher the score, the lower the risk you present to lenders.

Credit bureaus like Experian South Africa, TransUnion, Compuscan, and XDS compile your financial data and calculate your score based on factors such as:

  • Payment history
  • Length of credit history
  • Types of credit used
  • Frequency of credit applications

Financial institutions use this score to assess your ability to repay debt before approving personal loans, credit cards, or other financial products.


What Is Considered a Good Credit Score in South Africa?

In South Africa, a good credit score usually starts from 681 and above. Here’s a general breakdown:

Score Range Rating What It Means
0 – 527 Poor High risk – low loan approval odds
528 – 600 Below Average Some lenders may approve with high interest
601 – 680 Fair Acceptable, but limited access to top offers
681 – 766 Good Strong credit profile – favourable rates
767 – 999 Excellent Low risk, easy approvals, best interest rates

Credit bureaus may calculate scores slightly differently, but most South African lenders consider scores above 681 to be a good credit score.

A score of 681 or higher signals to lenders that you’re a responsible borrower — which means quicker approvals and lower interest rates on personal loans and other credit products.

Not sure where you stand? Checking your credit score is the fastest way to see your current position and understand what lenders may offer you.


Credit Scores vs Credit Reports: What’s the Difference?

Although often used interchangeably, a credit score and a credit report are two different things.

A credit score is the numerical summary of your creditworthiness, while a credit report is the full record of your credit history.

Your credit report includes:

  • Details of all open and closed credit accounts
  • Payment history and missed payments
  • Total outstanding balances
  • Judgments, defaults, or bankruptcies

The credit score is derived from this information — it’s the quick snapshot lenders use to make decisions.


Key Factors That Influence Your Credit Score

Understanding what affects your credit score is the first step to improving it. If you’re working to raise your score, read our guide on how to check and improve your credit score in South Africa.

The main factors include:

1. Payment History

Your payment history is one of the most important components of your score. Missing payments or defaulting on loans can cause significant damage. Always pay your accounts on or before the due date.

2. Debt-to-Credit Ratio

This ratio measures how much credit you’ve used compared to what’s available. A high ratio (using most of your credit limit) suggests risk, while keeping it below 30% shows responsible usage.

3. Length of Credit History

The longer you’ve managed credit responsibly, the better. Lenders value consistent, positive behaviour over time.

4. Types of Credit Used

Having a mix of credit — such as personal loans, credit cards, and store accounts — helps demonstrate your ability to manage different types of credit.

5. Frequency of Credit Applications

Each new loan or credit card application triggers a hard enquiry, which can temporarily lower your score. Too many applications in a short period raise red flags.


Credit Bureau Checks and Free Credit Checks

Your score is calculated by a credit bureau based on the information lenders report. If you want a free credit check, you can request your free credit report once per year from each registered bureau. Checking your report regularly also helps you spot mistakes that could hurt your credit scores, such as incorrect balances, missed payments recorded in error, or accounts you don’t recognise.

Many people run a free credit check before applying for personal loans to understand their approval chances.


How to Access and Read Your Credit Score in South Africa

You can easily check your credit score in South Africa through registered bureaus such as:

By law, every South African is entitled to one free credit report per year from each bureau. Reviewing your credit report regularly helps you spot errors, track improvements, and stay on top of your financial profile.

What to check on your credit report

  • Any missed/late payments you don’t recognise
  • Incorrect personal details
  • Unknown accounts (possible fraud)
  • Your credit utilisation and total balances

If you spot an error, dispute it immediately — credit bureaus are required by law to investigate and correct inaccuracies within 20 business days.


How to Get a Free Credit Score Check in South Africa

South Africans are legally entitled to a free credit check once per year from every registered credit bureau. This allows you to see your credit score, review your credit report, and check for errors that could hurt your credit scores.

You can request a free credit report from major credit bureaus such as:

  • Experian South Africa
  • TransUnion SA
  • Compuscan
  • XDS

A free credit check helps you understand whether you have a poor credit score, a good credit score, or one of the excellent credit scores ranges. Monitoring your report regularly also helps detect fraud, identify reporting errors, and track improvements in your financial profile.

Many South Africans check their score before applying for personal loans to understand their approval chances and potential interest rates.


Improving Your Credit Score in South Africa

Improving your credit score takes time, consistency, and responsible financial habits. If you want a step-by-step plan, see our guide on improving your credit score in South Africa. Here are proven strategies to raise your score and maintain a good standing.

1. Pay All Accounts on Time

Late or missed payments can severely damage your score. Set reminders or automatic debit orders to ensure you pay on time every month.

2. Reduce Outstanding Debt

Pay down your balances, starting with high-interest debts first. Lowering your overall debt load shows lenders you’re financially disciplined.

3. Keep Your Credit Utilisation Low

Use less than 30% of your available credit. If your credit card limit is R10,000, try not to use more than R3,000 regularly.

4. Limit New Credit Applications

Each new credit application triggers a hard check. Apply only when necessary to avoid short-term score drops.

5. Review Your Credit Report Annually

Mistakes happen — make sure your report accurately reflects your credit history. Correcting errors can boost your score instantly.


Dealing With Credit Score Challenges

If your score is low, don’t panic — improving it is absolutely possible. Here’s how to handle challenges effectively:

1. Identify the Problem Areas

Check for overdue accounts, defaults, or judgments. These are the biggest score-killers.

2. Negotiate with Creditors

If you’re struggling, contact your lenders early to arrange a payment plan before they report missed payments.

3. Consider Professional Help

If you’re overwhelmed, seek guidance from an NCR-registered debt counsellor or financial advisor. They can help you restructure debt and rebuild your score responsibly.

4. Be Patient

Credit repair takes time. Consistent positive behaviour — even over six months — can lead to noticeable improvement.


The Role of Credit Scores in Loan Approvals

Your credit score doesn’t just determine whether you’ll be approved for credit — it also impacts how much you can borrow and what you’ll pay for it.

Borrowers with higher scores typically enjoy:

  • Lower interest rates
  • Larger loan amounts
  • Easier approval for personal loans and credit cards

Those with poor scores may still get approved but face higher rates and stricter terms. That’s why having a good credit score and improving it over time is so important for financial flexibility.


How Often Should You Check Your Credit Score?

It’s recommended to check your credit score and full report at least once per year, though quarterly reviews are ideal.

Regular monitoring helps you:

  • Catch identity theft or fraudulent activity
  • Spot errors early
  • Track improvements
  • Stay credit-ready for upcoming loan or mortgage applications

Many credit bureaus, banks, and financial platforms now offer free or low-cost tools to monitor your score in real time.


Final Thoughts: Understanding What a Good Credit Score Means

Your credit score is more than a number — it’s a reflection of your financial habits and trustworthiness. Knowing what counts as a good credit score empowers you to make smarter borrowing decisions, negotiate better interest rates, and achieve long-term financial stability.

Building and maintaining a good score isn’t difficult — it just takes consistency: pay on time, keep your debt low, and monitor your credit regularly.

At FatCat Loans, we believe financial confidence starts with knowledge. Whether you’re working to improve your credit or looking for affordable personal loans, we’re here to help you borrow responsibly and achieve your goals.

Check your credit score, build it strong, and explore flexible loan options today with FatCat Loans

Compare your loan options with FatCat Loans.


FAQ: Good Credit Scores in South Africa

What is a good credit score in South Africa?

A good credit score in South Africa generally starts at 681 or higher on the 0–999 scale used by most credit bureaus. Borrowers with scores in this range are considered lower risk and are more likely to qualify for loans, credit cards, and better interest rates.

What is the average credit score in South Africa?

Average credit scores in South Africa typically fall within the fair to good range (around 600–700). However, scores vary depending on payment history, debt levels, and credit usage.

Is 650 a good credit score in South Africa?

A credit score of 650 is considered fair. While some lenders may approve credit applications, you may not qualify for the best interest rates. Improving your score above 681 can significantly improve your chances of approval and access to better loan terms.

What credit score is needed to get a loan in South Africa?

Most lenders prefer borrowers with credit scores of at least 600–650. However, approval criteria vary depending on the lender, your income, existing debt, and overall credit history. Borrowers with scores above 681 generally receive better loan offers.

How can I check my credit score for free in South Africa?

South African consumers are legally entitled to one free credit report per year from each credit bureau, including Experian, TransUnion, Compuscan, and XDS. Checking your credit report helps you monitor your score, identify errors, and detect possible fraud.

What factors affect your credit score in South Africa?

Several factors influence your credit score, including:

  • Payment history
  • Credit utilisation (how much credit you use)
  • Length of credit history
  • Types of credit accounts
  • Frequency of credit applications

Maintaining on-time payments and keeping debt levels low are two of the most effective ways to improve your score.

How long does it take to improve a credit score in South Africa?

Improving your credit score can take several months to a year, depending on your financial behaviour. Paying bills on time, reducing outstanding balances, and limiting new credit applications can gradually increase your score over time.

Credit Bureaus in South Africa: What They Do for Your Credit

Credit bureaus in South Africa collect and manage your credit information, which lenders use to assess your affordability and risk when you apply for loans. This guide explains how credit bureaus work, which bureaus operate locally, why your score can differ between bureaus, and how your credit report can affect approval decisions and interest rate

Credit Bureaus in South Africa

Your credit profile can influence almost every major financial decision — from whether you qualify for a personal loan to the interest rate you pay on a home loan. But many people don’t realise that your credit score and credit report don’t “belong” to your bank. They are generated and maintained by credit bureaus in South Africa.

Credit bureaus collect information from lenders, retailers, and credit providers, and use it to build your credit report and score. Lenders then use that information to assess risk when you apply for credit.

In this guide, you’ll learn what credit bureaus do, which bureaus operate in South Africa, how lenders use bureau data, why your score can differ between bureaus, how long negative listings stay on your record, and what your rights are under the National Credit Act.

Key Facts About Credit Bureaus in South Africa

    • Credit bureaus in South Africa collect credit data from lenders and generate your credit report and score.
    • Most lenders check one or more bureaus before approving a loan or credit application.
    • Your credit score can differ between bureaus because lenders don’t always report to every bureau and scoring models differ.
    • You’re legally entitled to a free credit report from each registered bureau once every 12 months under the National Credit Act.
    • Credit bureaus must remove paid-up judgments and defaults within set timeframes once updated by the credit provider.

What Are Credit Bureaus in South Africa?

Credit bureaus are regulated organisations that collect and store consumer credit information. They receive data from credit providers such as banks, loan companies, retailers, and cellular providers, and use it to create:

      • Your credit report (a record of your credit accounts and payment behaviour)
      • Your credit score (a number that summarises your risk profile)

Credit bureaus do not approve loans, set interest rates, or decide whether you qualify for finance. They provide the information lenders use to make those decisions.

Why Credit Bureaus Matter When You Apply for Loans

When you apply for credit, lenders use your bureau profile to answer key questions:

      • Have you repaid credit reliably in the past?
      • Are you currently over-indebted?
      • Have you missed payments recently?
      • Do you have defaults, judgments, or debt review on your profile?
      • Are you applying for credit frequently?

A good profile can improve approval odds and reduce your interest rate margin (prime –). A weaker profile may lead to higher pricing (prime +), smaller loan limits, or rejection.

If you’re unsure what lenders consider “good,” read our guide to what’s considered a good credit score in South Africa to understand the score bands and common approval thresholds.

The Main Credit Bureaus in South Africa

Most consumers will encounter these three major bureaus:

1) Experian

A global bureau operating in South Africa with credit reports, credit scoring tools, and dispute services.

2) TransUnion

One of the most widely used bureaus by banks and lenders for consumer and business credit checks.

3) XDS (Xpert Decision Systems)

A locally focused bureau used by many lenders and financial institutions, known for strong affordability and risk assessment reporting.

What About Compuscan?

Compuscan remains active locally, but it was acquired and is now part of Experian’s group. Many consumers still see “Compuscan” referenced because it historically operated independently.

Which Credit Bureau Do Banks and Lenders Use?

There’s no single bureau that every lender uses. Banks and credit providers may:

      • check one bureau only,
      • check multiple bureaus, or
      • use different bureaus depending on the product (home loan vs credit card vs personal loan).

This is why your credit report and score can look different depending on where you check it.

Important takeaway: If you’re preparing for a major application (like a home loan), it’s worth checking your profile across more than one bureau to make sure the information is consistent.

Why Your Credit Score Can Differ Between Bureaus

Many South Africans get confused when they see different scores at different bureaus. This is normal, and usually happens for three reasons:

1) Not all lenders report to every bureau

Some providers report to Experian but not TransUnion (or vice versa).

2) Update timing differs

Data can appear faster on one bureau than another depending on reporting cycles.

3) Scoring models differ

Even with similar data, bureaus can score the information using different weighting or scoring systems.

This is why your score isn’t a single universal number — it’s a reflection of bureau data and scoring methodology.

What Information Do Credit Bureaus Collect?

Credit bureaus typically track:

      • Your personal identity details (ID, name, addresses linked to credit)
      • Credit accounts (loans, credit cards, retail accounts, cellphone accounts)
      • Payment behaviour (on-time vs late payments)
      • Defaults and arrears
      • Judgments and collection actions
      • Debt review status
      • Recent credit applications (enquiries)

This data is provided by credit providers — not created by the bureau.

How Often Is Credit Bureau Information Updated?

Credit providers update bureau records on their own reporting cycle. Some update monthly, while others update more frequently depending on account type.

If you’ve recently paid off a debt or settled an account, it may take time for the credit provider to submit updates — and for those updates to reflect across all bureaus.

Tip: If you’ve settled a listing, ask the credit provider for proof of settlement and confirmation that they have updated your bureau status.

How Long Does Negative Information Stay on Your Credit Report?

Credit bureaus must follow retention rules under the National Credit Act. That means negative information does not stay forever.

Here are common retention examples (can vary by listing type):

      • Defaults: usually up to 1 year
      • Judgments: up to 5 years, unless paid earlier
      • Paid-up judgments: must be removed shortly after the credit provider confirms settlement
      • Enquiries: typically remain visible for a limited period

If you suspect outdated or incorrect negative listings, dispute them directly with the bureau and provide supporting documents.

Your Rights Under the National Credit Act (South Africa)

Under the National Credit Act, you have important consumer rights, including:

      • The right to access a free credit report once every 12 months from each registered bureau
      • The right to dispute inaccurate information
      • The right to have paid-up judgments and defaults removed once updated by the credit provider
      • The right to fair, lawful credit reporting practices

Knowing these rights helps you take control of your credit profile instead of relying only on lender decisions.

How to Check Your Credit Report

If you want the exact step-by-step process, follow our guide on how to check your credit score in South Africa — it explains where to access reports, what to look for, and how to avoid common errors before applying for credit.

Your bureau report matters most when you apply for a loan, so checking it before any big application can help you prevent avoidable rejection.

How to Dispute Errors on Your Credit Report (Quick Overview)

If your report contains incorrect information (wrong account, duplicate listing, outdated balance), you can dispute it.

The bureau must investigate the dispute within a regulated timeframe, and either update the report or confirm why the listing is valid.

For a full checklist and example dispute steps, read our guide to how to check your credit score in South Africa, which includes what documents to provide.

How Credit Bureaus Affect Interest Rates (Not Just Approval)

Many borrowers assume credit bureaus only matter for approval. In reality, they also influence:

      • your interest rate margin (prime + vs prime –)
      • your maximum loan limit
      • your repayment term options
      • whether you qualify for lower-risk credit products

Even a moderate improvement can shift your offer from expensive credit to more affordable options.

If you’re working on improving your profile, follow Improve Credit Score South Africa: Practical Steps That Work for a structured plan.

Credit Bureau Scams: How to Protect Yourself

Unfortunately, scammers often exploit people searching for “credit clearance” or “blacklist removal.”

Avoid providers that:

      • promise “instant removal” of negative listings
      • ask for upfront fees before checking your report
      • claim they can remove valid legal data without proof of settlement
      • request your bank login details or OTP codes

Legitimate credit bureaus will never ask for your banking password or OTP.

Compare the 4 Credit Bureaus in South Africa with FatCat Loans.

Conclusion: Credit Bureaus Are Not the Enemy — They’re the Record

Credit bureaus in South Africa play a central role in the lending system. They don’t decide whether you get a loan — but they provide the information lenders use to assess you.

The most powerful step you can take is to check your report regularly, understand what lenders see, dispute incorrect listings, and build consistent repayment habits over time.

If you want to check your profile and understand your score properly, follow our guide on how to check your credit score in South Africa before applying for credit.

Frequently Asked Questions: Credit Bureaus in South Africa

What are the main credit bureaus in South Africa?

The main bureaus consumers encounter are Experian, TransUnion, and XDS. Compuscan operates as part of Experian after its acquisition.

Do all lenders use the same credit bureau?

No. Lenders may check one or more bureaus depending on their risk policies and reporting relationships.

Why is my credit score different on Experian and TransUnion?

Scores can differ because lenders don’t report to all bureaus, bureaus update at different times, and scoring models differ.

How often can I get a free credit report in South Africa?

You are entitled to a free credit report once every 12 months from each registered bureau under the National Credit Act.

How long do defaults and judgments stay on your credit report?

Defaults and judgments are retained for regulated periods. Judgments can remain up to 5 years unless paid earlier, and paid-up listings must be removed after credit provider confirmation.

What should I do if my credit report has errors?

Dispute the information with the credit bureau and provide supporting documents. The bureau must investigate and update your report if the listing is incorrect.

Disclosure:  This article is for informational purposes only and does not constitute financial, legal, or credit advice. Credit reporting rules and retention periods are regulated by South African legislation and may change. Always verify your report directly with a registered credit bureau and consult a qualified advisor if you need legal or financial support.