Lime Loans Review (South Africa)

A detailed guide to Lime loans, including eligibility considerations, repayment structures, and how Lime compares with other lenders.

Introduction to Lime Loans

Last Updated:  July 2026

Lime Loans, now trading as Century Financial Services, is a digital credit provider operating in South Africa. Many South Africans still search for Lime Loans or Lime24 because that was the company’s previous trading name. Throughout this guide, we refer to Lime Loans where appropriate to reflect common search terms while noting the company’s current name.

Quick summary: Lime loans are usually positioned as online, non-bank instalment loans with a fast digital application. Before applying, confirm NCR registration, review the pre-agreement quotation, and compare total repayment with at least 3 alternatives.

2026 update: Century Financial Services is the new trading name for Lime Loans. Because many South Africans still search for “Lime Loans” and “Lime24”, this guide continues to use those names where relevant.

While Lime loans may appeal to borrowers seeking convenience and digital access, it is important to understand how Lime loans work, who they are best suited for, and how they compare with other lenders in the South African market. Applying without comparing alternatives can lead to repayment obligations that may not align with long-term affordability.

This is why many borrowers choose to compare loan options from multiple lenders before applying. Comparing lenders allows you to assess repayment structures, approval criteria, and suitability before committing to a loan.

Lime loans typically refer to online, non-bank personal loan options marketed for quick digital applications in South Africa. Always confirm the lender’s regulated status and total repayment before accepting any offer.

Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.

Button to compare Lime loan options with alternative lenders

Understanding Lime Loans as a Lender

Lime Loans at a glance (quick snapshot)

If you’re comparing Lime Loans (often referred to as Lime24 online), start with a quick snapshot of the typical factors borrowers check first: loan amount range, repayment term, total cost (interest + fees), payout speed, and required documents. If you’re specifically looking for a fully online process, you can also read our guide to online loans in South Africa. Some review sites publish example ranges and APR/fee examples, but always confirm the final quote on the lender’s official site before committing.

Lime Loans are usually compared against other online lenders based on total cost, approval checks, and payout speed.

What to check before you apply (fast checklist)

  • Is the provider NCR-registered? (Verify on the NCR register—steps below.)
  • Do you understand the full cost? (Interest rate + initiation fee + monthly service fee + any penalties.)
  • Can you afford the instalment after essentials? (Affordability checks are required under the National Credit Act framework.)
  • Do you need the money today—or just a fast decision? “Instant approval” and “same-day payout” are not always the same thing.

Century Financial Services (formerly Lime Loans) operates as a digital, non-bank lender, offering personal loan solutions through an online platform. Unlike traditional banks that often require branch visits or lengthy application processes, Century Financial Services focuses on accessibility and convenience through online applications.

Because of this model, Lime loans is often compared with other digital and non-bank lenders such as Wonga loan alternatives, Blink Finance loans, and Finance27 loan options.

Lime loans may appeal to borrowers who prefer digital-first loan applications and quicker decision-making processes.

Types of Loans Commonly Associated With Lime Loans

Most Lime loans searches relate to short- to medium-term instalment loans rather than long-term bank personal loans.

Searches for Lime loans generally relate to:

  • Short- to medium-term personal loans
  • Instalment-based credit solutions
  • Digitally issued loan agreements

These loans are commonly used for:

  • Managing unexpected expenses
  • Covering short-term financial gaps
  • Supporting personal cash flow needs

Lime loans are typically structured with fixed repayment terms, allowing borrowers to understand their repayment obligations upfront.

Who Typically Considers Lime Loan Options?

Lime loan options are commonly explored by:

  • Borrowers seeking digital loan solutions
  • Consumers comparing online lenders
  • Individuals looking for alternatives to bank loans

Many users researching Lime loans are also comparing:

This indicates that Lime loans is rarely considered in isolation and is often part of a broader loan comparison process.

Eligibility and Approval Considerations

If you’re applying because you need funds urgently, it’s important to understand the difference between “instant decision” and “same-day payout”. For time-sensitive options, compare same-day loans and instant loans to see what speed claims realistically mean.

Lime loan applications typically involve affordability and credit assessments before approving loan applications. These assessments typically consider:

Like most regulated credit providers, Lime loans generally require affordability and credit checks before approval.

  • Income consistency
  • Existing financial commitments
  • Credit history and repayment behaviour

As a digital lender, Lime loans may assess applications differently from traditional banks. Borrowers who do not meet bank lending criteria may still explore Lime loans as part of a comparison process.

Because approval outcomes and repayment terms vary, it is important to compare lenders before applying to avoid unsuitable commitments.

To verify a lender in South Africa, check the NCR register for the provider name or registration number. If it’s not listed, treat it as a red flag.

How to verify Century Financial Services (formerly Lime Loans) or any lender

Before you share ID/banking details or accept a loan offer, verify the lender is regulated.

Step 1: Check the National Credit Regulator (NCR) register
Search for Century Financial Services (formerly Lime Loans) or the applicable NCR registration number. Depending on when official records were updated, either name may appear. Always confirm that the registration details match the company you’re dealing with.

Step 2: Ask for (or locate) the pre-agreement statement & quotation
For regulated credit agreements, consumers are entitled to clear disclosure documents (the NCR provides official forms such as the Pre-Agreement Statement & Quotation format). This helps you compare total repayment, fees, and instalments before you accept.

Step 3: Never pay “upfront fees” to unlock a loan
If someone asks for a payment to “release” funds, it’s often a scam pattern. Use your site’s Fraud Alert guidance and only use regulated channels.

Advantages Often Associated With Lime Loans

Borrowers often consider Lime loans because of:

  • Fully online application process
  • Access to non-bank credit options
  • Structured repayment terms

These features may appeal to borrowers who value convenience and predictable repayment schedules.

Important Limitations to Consider

If the Lime loan is mainly for a short gap until payday, also compare short-term loans. If you need a longer repayment period, compare personal loans to avoid high short-term costs over time.

Despite its accessibility, Lime loans may not be suitable for all borrowers. Potential limitations include:

  • Repayment terms that may not suit long-term borrowing
  • Interest rates that may differ from traditional bank loans
  • Approval criteria that still require affordability checks

Because of these factors, Lime loans should always be compared with other available options before making a decision.

Understanding the real cost: interest + fees + penalties

When people search “Lime loans”, they’re usually comparing speed vs cost. The real cost of a loan is typically made up of:

  • Interest (often shown as a rate or APR)
  • Initiation fee (a regulated type of fee in SA credit agreements)
  • Monthly service fee
  • Default/late-payment charges (if you miss payments)

South Africa’s National Credit Act framework and related regulations set rules around credit marketing, disclosure, and affordability assessments. That’s why it’s important to compare total repayment—not just the headline “rate” or “instant approval” messaging.

The true cost of a loan is usually interest + initiation fee + monthly service fee + penalties. Compare total repayment, not only the advertised rate.

Borrower tip: If a lender can’t show you a clear quotation with the total repayment and fees, consider that a risk signal.

Comparing Lime Loans With Other Lenders

When comparing Lime loans with lenders such as Finchoice loan options, Sanlam loan options, or DirectAxis personal loans, borrowers should consider:

  • Repayment structure and duration
  • Monthly affordability
  • Differences in approval criteria

Some lenders may offer longer repayment periods or different credit structures, which is why comparison is essential.

When Lime Loans May Be a Good Fit

Century Financial Services (formerly Lime Loans) may suit borrowers who:

  • Prefer digital-first loan applications
  • Have stable income and manageable debt
  • Are exploring non-bank lending options
  • Are actively comparing multiple lenders

In these scenarios, Lime loans can form part of a broader loan comparison strategy.

When Lime Loans May Not Be the Right Option

Lime loans may be less suitable if you:

  • Are seeking long-term repayment flexibility
  • Prefer traditional bank lending products
  • Are managing complex or high-value financial commitments

In such cases, other lenders may offer solutions better aligned with your financial needs.

Alternatives if Lime Loans Is Not the Right Fit

If Lime loans does not meet your requirements, alternatives may include:

  • Banks offering personal loans
  • Other non-bank instalment lenders
  • Digital lenders with different approval models

Exploring alternatives ensures you are not limited to a single lender’s criteria.

How FatCat Loans Helps You Compare Lime Loans With Other Options

Borrowers who want to compare Lime loans with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.

FatCat Loans helps South Africans compare loan options from multiple lenders, including digital providers like Lime loans and traditional financial institutions. Using a comparison platform allows you to:

  • Compare repayment structures and affordability
  • Review multiple lenders in one place
  • Identify alternatives without unnecessary applications

This comparison-first approach supports informed and responsible borrowing decisions.

Responsible borrowing checklist (read this before you accept any offer)

Because loans affect your financial wellbeing, use this checklist before signing:

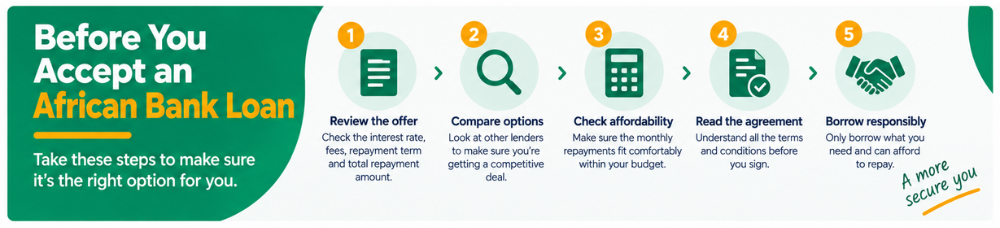
  1. Confirm affordability after rent, food, transport, and existing debt. (Affordability assessment requirements exist to reduce reckless credit.)
  2. Match the term to the purpose: short-term credit for short-term needs—avoid rolling debt into repeated borrowing.
  3. Compare at least 3 alternatives (bank + non-bank + digital) to avoid overpaying.
  4. Know your rights under SA consumer credit rules (disclosure, transparency, and fair treatment are core objectives).

Quick answers about Lime loans

  • NCR registration: Always verify the provider on the NCR register before sharing banking details.
  • Cost: Total cost usually includes interest + initiation fee + monthly service fee + late-payment charges.
  • Speed: “Instant decision” and “same-day payout” are not the same—confirm payout timing.

Frequently Asked Questions About Lime Loans

Are Lime Loans and Century Financial Services the same company?

Yes. Century Financial Services is the new trading name for Lime Loans. Many people still search for Lime Loans or Lime24, so both names may still appear online. When researching the lender, always confirm you are dealing with the official company and review the latest loan terms before applying.

Should I compare Lime loans with other lenders before applying?

Yes. Comparing lenders helps ensure the loan structure and repayments align with your financial situation.

For Lime loans, always confirm the initiation fee, monthly service fee, and the total repayment shown on the quotation before accepting.

Can I explore alternatives if Lime loans is not suitable?

Yes. Comparison platforms allow you to review multiple lenders and identify suitable alternatives.

Lime loans should only be considered if the instalment fits your budget after essentials and existing debt.

How can I check if Lime Loans is registered with the National Credit Regulator (NCR)?

You can verify any lender in South Africa by searching the National Credit Regulator (NCR) register using the lender’s name or registration number. If a lender is not listed, it may not be legally authorised to offer credit.

What fees should I expect when applying for a Lime loan?

Loan costs may include interest, an initiation fee, a monthly service fee, and possible late-payment charges. Always review the full quotation and total repayment amount before accepting any loan offer.

Does Lime Loans perform affordability checks?

Legitimate lenders in South Africa are required to conduct affordability assessments to ensure borrowers can repay the loan after covering essential living expenses and existing debt obligations.

Is Lime Loans suitable for short-term borrowing only?

Lime loans are generally considered more suitable for short-term or emergency expenses rather than long-term borrowing. For larger or longer-term needs, comparing traditional personal loans may be a better option.

What documents are usually required to apply for a Lime loan?

Requirements vary, but most online lenders typically ask for a South African ID number, an active bank account, a mobile phone number, and proof of income such as payslips or bank statements.

What should I do if I cannot repay my Lime loan on time?

If you anticipate repayment difficulties, contact the lender immediately to discuss possible options or review our FAQ for help. Avoid taking additional loans to cover repayments, and consider seeking help from a registered debt counsellor if you are over-indebted.

Are there alternatives to Lime Loans in South Africa?

Yes. Borrowers can compare banks, non-bank lenders, and digital loan providers to find options with different interest rates, repayment terms, and approval criteria. Start by using our compare loans hub to review options side-by-side.

Final Thoughts

Century Financial Services (formerly Lime Loans) continues to offer digital loan solutions for South Africans exploring non-bank lending options. While many borrowers still search for Lime Loans or Lime24, the company now trades as Century Financial Services. As with any lender, compare loan costs, repayment terms and affordability before accepting an offer.

By comparing Lime Loans with other lenders, you gain a clearer understanding of repayment obligations, approval criteria, and alternative solutions that may better suit your financial needs. FatCat Loans comparison simplifies this process by helping you compare loan options in one place, supporting informed and responsible borrowing decisions.

Fasta Loans: What South Africans Should Know Before Applying

A detailed guide to Fasta loans, including eligibility considerations, repayment structures, and how Fasta compares with other lenders.

FASTA Loans in South Africa: How They Work

Last Updated: September 2026

Fasta is a South African credit provider offering short- to medium-term personal loan solutions.

Many South Africans come across this lender when searching for accessible credit options that may offer faster decisions than traditional banks.

Searches for Fasta loans, Fasta personal loans, and Fasta credit options are common among borrowers comparing lenders.

Before applying, it’s important to understand how these loans work, who they suit, and how they compare with other options on the market.

You can also explore other providers in the FatCat Loans lender network before choosing a loan.

Applying without comparing alternatives can lead to repayment commitments that don’t match your affordability or long-term goals.

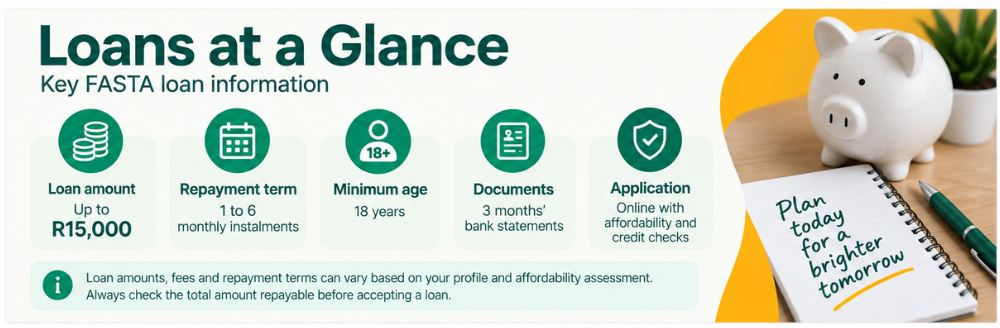
FASTA loans at a glance (quick summary)

This quick summary helps you decide if FASTA is worth considering before reading the full guide.

  • Typical loan size: Up to R15,000
  • Repayment term: 1 to 6 monthly instalments
  • Best for: short-term cash-flow gaps and urgent small expenses (not long-term borrowing)
  • Key watch-outs: fees add up quickly on short terms—always check the total repayable before accepting

FASTA offers short-term loans in South Africa of up to R15,000, repayable over 1 to 6 monthly instalments.

Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.

FASTA loan amounts, terms and requirements

Understanding Fasta as a Lender

Fasta operates as a non-bank personal loan provider in South Africa.

FASTA operates differently from a traditional bank, with an online application process focused on short-term credit.

Some borrowers may consider FASTA alongside traditional banks and other non-bank credit providers when comparing short-term loan options.

How to verify FASTA (or any lender) is registered with the NCR

In South Africa, legitimate credit providers are typically registered with the National Credit Regulator (NCR).

You can verify a lender by searching the NCR’s Register of Registrants and checking the provider name or registration number.

FASTA is a registered South African credit provider under NCRCP10591. You can independently verify a credit provider using the National Credit Regulator’s Register of Registrants.

Why this matters: If a lender cannot be found on the NCR register, treat it as a red flag—especially if they request upfront payments before you have signed a credit agreement.

Fasta is often compared with other non-bank and alternative lenders such as MPowa loan options, Lime loan options, and Blink Finance loans.

FASTA Contact Details

If you need to contact FASTA about an application, existing loan, repayment or account query, FASTA primarily directs customers to its online Customer Support Portal.

Customer support Use the Support portal at www.fasta.co.za
Support email [email protected]
General email [email protected]
Collections email [email protected]
Customer service hours Monday–Friday: 08:00–17:00
Saturday: 08:00–12:00
Sunday & public holidays: Closed
Physical address 33 Bree Street, Cape Town, 8001
NCR registration NCRCP10591

FASTA states that customers can submit a support ticket by selecting Support on its website. Logged-in customers can also access the Customer Support Portal through their FASTA profile.

Repayment problems: If you think you may miss a payment, FASTA advises contacting its Collections team at [email protected].

Contact details checked against FASTA’s official website in September 2026. FASTA may change its contact channels, so confirm the latest details on the official website.

FASTA contact details and customer service hours

Types of Loans Commonly Associated With Fasta

Searches for Fasta loans generally relate to:

These loans are commonly used for:

Managing unexpected expenses

  • Covering short-term financial needs
  • Supporting household or personal cash-flow requirements
  • Bridging gaps between income cycles

Fasta loans are typically structured with fixed monthly repayments, allowing borrowers to understand their repayment obligations upfront.

This predictability can be useful for budgeting, particularly for borrowers who want clarity around their monthly financial commitments.

A FASTA-style loan is usually best for a small, urgent expense or a short cash-flow gap—not for long-term borrowing

Who Typically Considers Fasta Loan Options?

Fasta loan options are commonly explored by:

  • Borrowers seeking alternatives to traditional bank loans
  • Consumers comparing non-bank lenders
  • Individuals looking for structured instalment repayments
  • Borrowers researching multiple lenders before applying

Many users researching Fasta are also comparing:

This behaviour highlights that Fasta is rarely considered in isolation and is usually part of a wider loan comparison process.

Eligibility and Approval Considerations

Fasta applies affordability and credit assessments before approving loan applications. These assessments typically take into account:

  • Income stability and consistency
  • Existing financial commitments
  • Credit history and repayment behaviour

As a non-bank lender, Fasta may assess applications differently from traditional banks. This can result in approval outcomes that vary depending on an applicant’s financial profile.

Borrowers with stable income and manageable debt are more likely to qualify for better repayment terms.

Tip: Always compare the total repayable amount — not just the monthly instalment.

Costs, fees, and what “cheap” really means on a short-term loan

With short-term credit, the rate is only part of the story. The total cost typically includes:

  • Interest (often quoted monthly for short-term credit)
  • Once-off initiation fee (charged when a new credit agreement is set up)
  • Monthly service fee (admin/maintenance fee on the agreement)
  • Optional or required add-ons (for example, credit protection/insurance if included in the offer).

Representative example (why you must check the total repayable)

A representative example shown by FASTA includes a combination of interest + initiation fee + monthly service fee + credit protection, and also references a maximum APR. Always compare:

  1. the total amount repayable, and
  2. what happens if you miss a payment (extra fees/interest).

Quick affordability checklist

Before accepting any offer, sanity-check:

  • Can you repay on your next pay cycle without needing another loan?
  • If income drops, do you still have a fallback plan?
  • Are you borrowing for a need (essentials/emergency) rather than a want?

If any answer is “no”, it’s safer to compare longer-term personal loans instead of rolling short-term debt.

What fees can be included in a FASTA-style short-term loan?

Short-term credit commonly includes interest, a once-off initiation fee, and a monthly service fee, and may include additional cover/insurance depending on the offer.

Compare Fasta loan options with alternative lenders

Advantages Often Associated With Fasta Loans

Borrowers often consider Fasta because of:

  • Access to non-bank credit solutions
  • Fixed monthly repayments that support budgeting
  • Structured instalment-based loan agreements
  • Simpler application processes compared to banks

These features may appeal to borrowers who want predictable repayments and a straightforward alternative to traditional bank lending.

Important Limitations to Consider

Fasta may not be suitable for everyone. Some limitations to consider include:

  • Repayment terms that may not suit long-term borrowing
  • Interest rates that may differ from traditional bank loans
  • Approval criteria that still require affordability checks

Because of these factors, Fasta loans should always be reviewed alongside other available lenders before making a final decision.

You can verify a lender by searching the NCR’s Register of Registrants for the provider name or registration number.

What to do if you’re struggling to repay

Short-term loans become expensive when you miss a payment or need to refinance repeatedly. If you think you’ll struggle:

  1. Contact the credit provider immediately to discuss arrangements before you default.
  2. Prioritise essentials (housing, transport to work, food) over non-essential repayments.
  3. Avoid “loan stacking” (taking a second loan to pay the first). This is where many borrowers get trapped.

If your current repayments feel unmanageable, comparing alternative lenders may help you find a more affordable option.

Comparing Fasta With Other Lenders

When comparing Fasta with lenders such as FinChoice loan options, Sanlam loan options, or RCS credit options, borrowers should consider:

  • Repayment structure and loan duration
  • Monthly affordability
  • Differences in approval criteria
  • Flexibility versus predictability

Some lenders may offer longer repayment periods, while others focus on shorter-term credit. Comparing these differences helps ensure you select a loan that aligns with your financial needs and repayment capacity.

When Fasta May Be a Good Fit

Fasta may suit borrowers who:

  • Are exploring non-bank loan options
  • Have stable income and manageable debt
  • Prefer structured instalment repayments
  • Want predictable monthly commitments
  • Are actively comparing multiple lenders

In these scenarios, Fasta can form part of a broader loan comparison strategy rather than a standalone decision.

If you fall into one of these categories, it’s worth checking what lenders will actually offer you based on your profile.

When Fasta May Not Be the Right Option

Fasta may be less suitable if you:

  • Are seeking long-term repayment flexibility
  • Prefer traditional bank lending products
  • Are managing complex or high-value financial commitments
  • Require highly flexible credit structures

In such cases, other lenders may offer solutions better aligned with your financial needs.

Alternatives if Fasta Is Not the Right Fit

If Fasta does not meet your requirements, alternatives may include:

  • Traditional banks offering personal loans
  • Other non-bank instalment lenders
  • Digital lenders with different approval models

Exploring alternatives ensures you are not limited to a single lender’s criteria or lending structure.

FASTA vs other options (quick comparison)

Option Typically best for Typical trade-off
Short-term loans (FASTA-style) Small urgent gaps Higher cost density over short term (fees matter)
Personal loans (longer term) Bigger needs, lower monthly strain Slower approval / stricter checks
Compare multiple lenders (recommended first step) Avoiding mismatches & rejections Takes a few extra minutes, saves cost/risk

How FatCat Loans Helps You Compare Fasta With Other Options

Borrowers who want to compare Fasta with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.

FatCat Loans helps South Africans compare loan options from multiple lenders, including non-bank providers like Fasta and traditional financial institutions. By using a comparison platform, you can:

  • Compare repayment structures and affordability
  • Review multiple lenders in one place
  • Identify alternatives without submitting multiple applications

This comparison-first approach supports informed and responsible borrowing decisions.

Frequently Asked Questions About Fasta Loans

How much can I borrow with FASTA loans?

FASTA currently offers cash loans of up to R15,000. The amount you can borrow depends on your application, affordability assessment and credit checks. Approval for the maximum amount is not guaranteed.

How long do I have to repay a FASTA loan?

FASTA loans can currently be repaid over 1 to 6 monthly instalments. Your repayment term, instalment amount and total amount repayable will be shown before you accept the loan.

What are the FASTA contact details?

FASTA’s Customer Services Team can be contacted through the Customer Support Portal at FASTA’s official website. Select Support to submit a query.

Customer service hours are Monday to Friday, 08:00–17:00, and Saturday, 08:00–12:00. The service is closed on Sundays and public holidays. Customers who are struggling with a repayment can email [email protected].

Is FASTA a registered lender in South Africa?

Yes. FASTA (Pty) Ltd states that it is a registered credit provider with the National Credit Regulator under NCRCP10591. You can independently verify a credit provider using the NCR’s Register of Registrants.

What do I need to apply for a FASTA loan?

FASTA’s current application information states that applicants need to be 18 or older, have a valid South African ID number and provide three months’ bank statements. You’ll also need your mobile number and online banking details during the application process. Applications remain subject to affordability and credit checks.

How quickly does FASTA pay out a loan?

FASTA currently advertises automated applications and says approved FASTACash funds can be paid directly into your bank account. Its FAQ says applications generally take around 2–3 minutes, although actual timing can vary depending on the application and banking process.

What fees does FASTA charge?

Your loan cost can include interest, a once-off initiation fee, a monthly service fee and credit protection insurance. The exact cost depends on the loan product and offer, so check the total amount repayable before accepting the agreement.

Can I get a FASTA loan with bad credit?

FASTA does not guarantee approval based simply on having a particular credit score. Applications are subject to affordability and credit checks, so your individual financial circumstances will affect the outcome.

Final Thoughts

Fasta provides access to structured personal loan solutions for South Africans exploring non-bank lending options.

However, accessibility alone should not determine your choice of lender.

By comparing Fasta with other lenders, you gain a clearer understanding of repayment obligations, approval criteria, and alternative solutions that may better suit your financial needs.

The key step is simple: compare before you apply.

With one quick check, you can see which lenders are most likely to approve you — and what your repayments could look like.

See loan options

Sources & Verification

We checked the information in this FASTA loans review against current lender information and South African consumer-credit sources. Key sources include:

Product information and contact details were checked in September 2026. Loan amounts, interest rates, fees, eligibility requirements and other terms can change. Always check your individual quotation and the lender’s official website before accepting a credit agreement.

MPowa Finance: What South Africans Should Know Before Applying

A detailed guide to MPowa loans, including eligibility considerations, repayment structures, and how MPowa compares with other lenders.

MPowa Loans Review South Africa

Last Updated: September 2026

MPowa is a South African credit provider. It is commonly associated with mobile-based and alternative personal loan solutions.

Many South Africans come across MPowa when searching for accessible credit options that do not follow traditional bank lending models.

Because of this, searches for MPowa loans, MPowa personal loans, and MPowa credit options are common among borrowers comparing lenders and exploring non-bank alternatives.

Quick note on the name “Mpowa”:
Some searches for “mpowa” may show unrelated organisations (for example, mpowa.io).

This article refers specifically to Mpowa Finance loans in South Africa (commonly found at mpowafin.co.za).

While MPowa may appeal to borrowers looking for convenience or alternative approval models, it is important to understand how these loans work.

You should also consider who they are best suited for, and how they compare with other lenders in the South African market.

If you’re comparing MPowa with other borrowing options, you can also compare lenders in South Africa through FatCat Loans before deciding which type of loan may suit your needs.

Applying without comparing alternatives can lead to repayment obligations that may not align with long-term affordability.

Important: FatCat Loans is a loan comparison service and is not affiliated with, endorsed by or owned by MPowa Finance. MPowa Finance may not be one of the lenders available through our comparison service. Loan amounts, rates, fees and eligibility criteria can change. Always confirm the terms of your individual quotation and pre-agreement statement before accepting credit.

Compare MPowa loan options with alternative lenders

Understanding MPowa as a Lender

MPowa operates as a non-bank lender offering personal loan solutions through alternative and digital-first channels.

Unlike traditional banks that rely on branch-based processes and long approval timelines, MPowa focuses on accessibility and technology-driven credit assessments.

Because of this model, MPowa is often compared with other alternative and digital lenders such as Lime loan options, Blink Finance loans, and Finance27 loan options.

MPowa may appeal to borrowers looking for a relatively small, short-term loan who prefer to complete the application online rather than through a traditional bank branch.

Borrowers can also compare loans across multiple providers to see how MPowa stacks up against other non-bank and bank lenders.

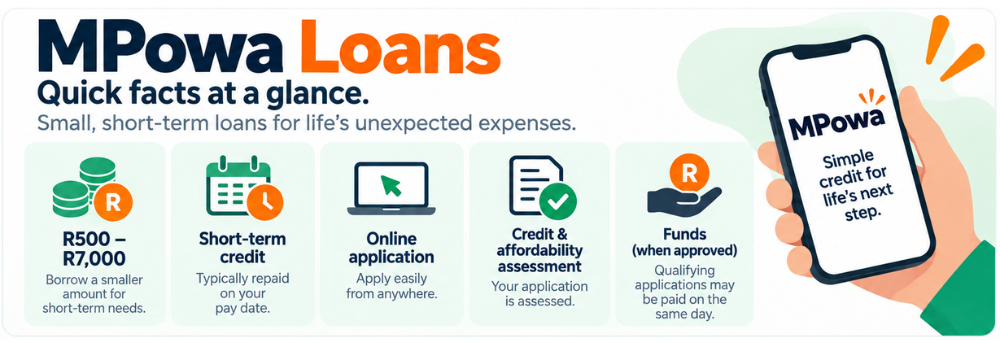
MPowa Finance loans: quick facts (at a glance)

(Always confirm the latest terms on the official site before applying.)

MPowa Loan Feature Details
Loan amount R500 – R7,000
Loan type Short-term credit
Application Online
Repayment Typically linked to your pay date
Interest 5% per month; 3% on additional loans in the same calendar year
Initiation fee 16.5% on the first R1,000, then 10% above R1,000, plus VAT
Monthly service fee R60 plus VAT
Credit check Yes
Registered credit provider MPowa Finance (Pty) Ltd – NCRCP6666

Rates, fees, eligibility and repayment terms can change and depend on your individual credit agreement. Always confirm the total repayment amount and due date before accepting a loan.

What are Mpowa loans?

Mpowa loans generally refer to short-term personal loans offered online by Mpowa Finance in South Africa, designed for smaller amounts with a fixed repayment date. Exact costs and approval depend on your quote and affordability checks.

Is MPowa Finance Legit and Registered in South Africa?

Yes. MPowa Finance (Pty) Ltd states that it is a registered South African credit provider with the National Credit Regulator under NCRCP6666. Its company registration number is 2011/128825/07.

Being NCR-registered means MPowa must operate within South Africa’s credit regulatory framework, including affordability and responsible-lending requirements. However, registration does not mean that a particular loan will be affordable or suitable for every borrower.

Consumers can independently check credit-provider information through the National Credit Regulator (NCR).

MPowa loan amounts, application and repayment overview

What Type of Loan Does MPowa Offer?

Searches for MPowa loans generally relate to:

  • Short-term personal loans
  • Online credit of R500 to R7,000
  • Loans generally structured around the applicant’s pay cycle

These loans are commonly used for:

  • Managing unexpected expenses
  • Covering short-term financial gaps
  • Supporting day-to-day cash flow needs

MPowa loans are usually structured with fixed repayment terms. This helps borrowers understand their repayment obligations upfront.

These products fall within the broader category of short-term loans in South Africa.

Who Typically Considers MPowa Loan Options?

MPowa loan options are commonly explored by:

  • Borrowers seeking non-bank lending solutions
  • Consumers who prefer mobile or digital credit access
  • Individuals comparing alternative lenders

Many users researching MPowa are also comparing:

This indicates that MPowa is usually part of a broader loan comparison process rather than a single-lender decision.

Eligibility and Approval Considerations

MPowa applies affordability and credit assessments before approving loan applications. Its basic eligibility and application requirements include:

  • Be at least 18 years old
  • Have a valid South African ID
  • Be permanently employed
  • Have worked for your current employer for at least 3 months
  • Receive a regular monthly salary into a South African bank account
  • Provide recent bank statements or payslips when requested

Approval outcomes and repayment terms can vary, so it is important to compare lenders before applying.

Does MPowa Perform a Credit Check?

Yes. MPowa Finance states that its lending decisions consider affordability and credit information. Its lending policy says the assessment can include gross and net salary, employment history, existing commitments and a credit-bureau check.

Meeting the basic eligibility requirements does not guarantee approval. The lender still needs to determine whether the proposed repayment is affordable based on your circumstances.

If you’re unsure how lender enquiries can affect your credit profile, read our guide to soft vs hard credit checks in South Africa.

What You May Need to Apply

MPowa may ask you to provide supporting documents such as:

  • A valid South African ID
  • Recent payslips and/or bank statements
  • Bank account details for verification and repayment

Because the application process is digital, borrowers who prefer this type of application can also compare online loan options in South Africa before applying.

How to Apply for an MPowa Loan

MPowa’s current application process is completed online. The lender describes the process as:

  1. Create an account and complete the online application.
  2. Provide your supporting documents, such as recent bank statements or payslips.
  3. Complete the affordability and credit assessment.
  4. Review and sign your credit agreement if approved.
  5. Authorise the repayment mandate and confirm the terms before funds are released.

Always check the total repayment, fees and repayment date shown in your credit agreement before accepting the loan.

How Long Does an MPowa Loan Take to Pay Out?

MPowa promotes same-day funding for qualifying applications. Its current information states that successful applications received before 3pm may be paid at 5pm on the same day.

However, same-day payment should not be treated as guaranteed. Timing can depend on completing the application, submitting the required documents, employment verification, approval and the required repayment mandate.

If speed matters, compare the total borrowing cost and repayment terms as well as payout time before choosing a lender.

Features of MPowa Loans

Borrowers often consider MPowa because of:

  • Access to alternative credit options
  • Digital or mobile-friendly application processes
  • Structured repayment terms

These features may appeal to borrowers who value accessibility and predictable repayment schedules.

Important Limitations to Consider

Despite its accessibility, MPowa may not be suitable for all borrowers. Potential limitations include:

  • Repayment terms that may not suit long-term borrowing
  • Interest rates that may differ from traditional bank loans
  • Approval criteria that still require affordability checks

Because of these factors, MPowa loans should always be reviewed alongside other available options before making a decision.

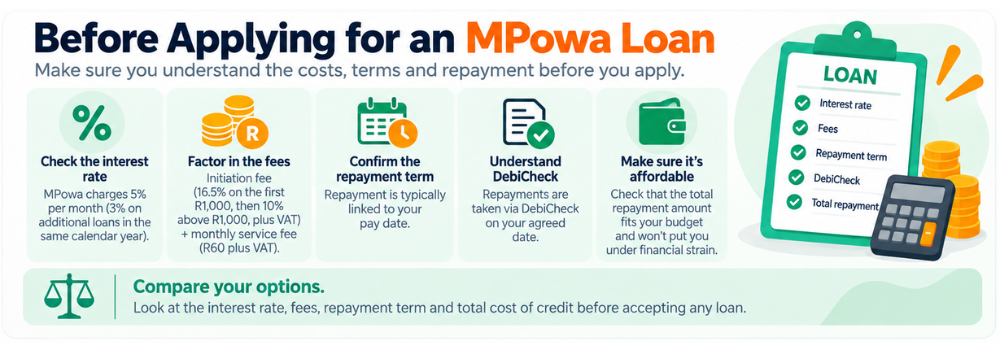
What MPowa loans can cost (and how to compare properly)

With short-term credit, the total repayment usually includes three parts:
(1) an initiation fee, (2) a monthly service fee, and (3) monthly interest.

So the true cost isn’t visible from “interest” alone.

MPOWA’s fee structure may also differ between a first loan and later loans within the same calendar year.

A safer comparison method (use this every time):

  1. For each lender, write down the cash amount you receive.
  2. Write down the total amount you must repay and the exact due date.
  3. Subtract (2 – 1) to get the total cost of credit in rands.
  4. Compare lenders using the same loan amount and same repayment window (e.g., ~30 days).

Red flag check: if any quote is unclear about total repayment, debit order authorisation, or fees, pause and compare alternatives before submitting documents.

How to Verify MPowa Before Applying

Before submitting personal or banking information:

  • confirm that you’re using MPowa Finance’s official website
  • check the lender’s NCR registration details
  • read the quotation and pre-agreement statement carefully
  • confirm the total repayment amount and due date
  • never pay an unexpected upfront fee to release a loan

Third-party customer reviews can provide useful information about service experiences, but they should not replace regulatory or contractual checks.

Consumer protection note

South Africa’s National Credit Act regulates credit agreements and certain borrowing costs, including applicable fees and interest limits.

If a quote looks far outside these norms, treat it as a red flag and verify that the lender is properly registered.

Comparing MPowa With Other Lenders

When comparing MPowa with lenders such as Finchoice loan options, Sanlam loan options, or DirectAxis loan options, borrowers should consider:

  • Repayment structure and duration
  • Monthly affordability
  • Differences in approval criteria

Some lenders may offer longer repayment periods or different credit structures, which is why comparison is essential.

To reduce unnecessary applications, start by visiting the compare loans page and shortlist suitable options first.

How to compare Mpowa vs other lenders (fast checklist): 

Compare (1) cash you receive, (2) total repayment, (3) due date, (4) all fees, and (5) mandate method — then choose the option that fits affordability.

When MPowa May Be a Good Fit

MPowa may suit borrowers who:

  • Prefer mobile or digital loan access
  • Have stable income and manageable debt
  • Are exploring non-bank lending options
  • Can afford to repay the loan on the agreed pay date

In these scenarios, MPowa can form part of a broader loan comparison strategy.

Mpowa may be a better fit when you need a small once-off bridge to payday, have stable income, and can repay on time without borrowing again. If you need long-term flexibility, compare instalment-style alternatives first.

When MPowa May Not Be the Right Option

MPowa may be less suitable if you:

  • Are seeking long-term repayment flexibility
  • Prefer traditional bank lending products
  • Are managing complex or high-value financial commitments

In such cases, other lenders may offer solutions better aligned with your financial needs.

If you’re worried about repayment, read this first

A short-term loan is safest when you already know exactly how you will repay it on payday—without missing rent, food, transport, or existing debit orders.

MPowa uses DebiCheck to authorise loan repayments. When accepting a loan, make sure the mandate amount and repayment date match the credit agreement before approving it.

Always ensure you understand what you’re authorising and keep proof of your mandate.

If you can’t repay on time:

  1. Contact the credit provider before the due date and ask what formal options exist.
  2. Avoid rolling multiple short-term loans at once (this is where affordability breaks).
  3. If you feel pressured or confused, pause and get independent help (debt counselling can be appropriate for persistent repayment difficulty).

(This guide is informational and not financial advice.)

Alternatives if MPowa Is Not the Right Fit

If MPowa does not meet your requirements, alternatives may include:

  • Traditional banks offering personal loans
  • Other non-bank instalment lenders
  • Digital lenders with different approval models

If you need a larger amount or a longer repayment period, you can also compare personal loans in South Africa, where repayment structures may differ from MPowa’s short-term credit model.

MPowa loan interest, fees and repayment checklist

How FatCat Loans Helps You Compare MPowa With Other Options

Borrowers who want to compare MPowa with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.

FatCat Loans helps South Africans compare loan options from multiple lenders, including alternative providers like MPowa and traditional financial institutions.

  • Compare repayment structures and affordability
  • Review multiple lenders in one place
  • Identify alternatives without unnecessary applications

This comparison-first approach supports informed and responsible borrowing decisions.

Compare MPowa loan options with alternative lenders

Sources & Verification

This page is maintained by the FatCat Loans South Africa Editorial Team and is reviewed against primary sources including:

  • MPowa Finance’s official loan, fee, eligibility and application information
  • MPowa Finance’s published lending policy
  • National Credit Regulator registration information
  • South Africa’s National Credit Act

Loan costs, eligibility and repayment terms depend on your individual quotation and affordability assessment and may change.

Frequently Asked Questions About MPowa Loans

Is MPowa Finance a legitimate lender?

Yes. MPowa Finance (Pty) Ltd states that it is registered with the National Credit Regulator under NCRCP6666. Its company registration number is 2011/128825/07. Being NCR-registered means MPowa operates within South Africa’s credit regulatory framework, although that does not mean every loan will be suitable or affordable for every borrower.

How much can I borrow from MPowa?

MPowa currently advertises short-term loans from R500 to R7,000. The amount available to you depends on your application, affordability assessment and credit profile. You can also choose to accept a smaller amount than the maximum offered.

What are the requirements for an MPowa loan?

MPowa’s lending criteria include being at least 18 years old, having regular income and meeting its affordability and credit requirements. MPowa also states that applicants generally need to have been in their current job for at least three months and may need to provide recent bank statements or payslips.

Does MPowa perform a credit check?

Yes. MPowa’s application form asks for permission to perform a credit check, and its lending policy states that it considers factors such as income, employment history, existing commitments and credit-bureau information. Approval is therefore not guaranteed simply because you meet the basic application requirements.

What interest and fees does MPowa charge?

MPowa currently states that short-term credit agreements can include an initiation fee of 16.5% on the first R1,000, then 10% on amounts above R1,000, plus VAT, a R60 monthly service fee plus VAT, and interest of 5% per month. MPowa also states that additional loans in the same calendar year may be charged interest at 3% per month. Always confirm the exact total repayment shown in your individual quotation.

How long does an MPowa loan take to pay out?

MPowa promotes same-day payment for qualifying applications. Its current FAQ says funds may be paid at 5PM on the same day, provided the required documents are received and employment confirmation can be completed. Same-day payout should not be treated as guaranteed because processing depends on completing all required checks and steps.

How do I repay an MPowa loan?

MPowa states that repayment is generally collected by debit order and uses DebiCheck to authorise the repayment mandate. The repayment is typically linked to your pay date. Always check that the amount and date shown in the mandate match your credit agreement before approving it.

Can I get an MPowa loan with bad credit?

A weaker credit profile does not automatically tell you whether MPowa will approve or decline an application. MPowa performs credit and affordability assessments and considers factors such as income, employment, existing commitments and credit history. Meeting the basic requirements does not guarantee approval. If your credit history is making borrowing difficult, you can also compare bad credit loan options in South Africa before applying.

Final Verdict: Is an MPowa Loan Worth Considering?

MPowa may be worth considering if you need a small, short-term loan, have stable income and can repay the full amount on your agreed pay date.

However, the short repayment period means affordability is especially important. Interest, initiation fees and service fees can add meaningfully to the total amount repayable, even on a relatively small loan.

Before accepting an MPowa loan, check the total repayment amount, due date, fees and DebiCheck mandate, and compare the offer with other short-term or personal loan options.

The right choice is the one you can repay comfortably without needing to borrow again to cover the repayment.

FinChoice Loans Review South Africa: Rates, Fees & Requirements

A detailed guide to Finchoice loans, including eligibility considerations, repayment options, and how Finchoice compares with other lenders.

FinChoice Loans

Last Updated: September 2026

FinChoice is a South African digital credit provider offering personal loans and other credit products through its online and mobile platforms. Its current products include personal loans, MobiMoney™ and KwikAdvance.

This FinChoice loans review explains the amounts available, repayment terms, requirements, credit checks, account login and contact details, as well as what to check before accepting a loan offer.

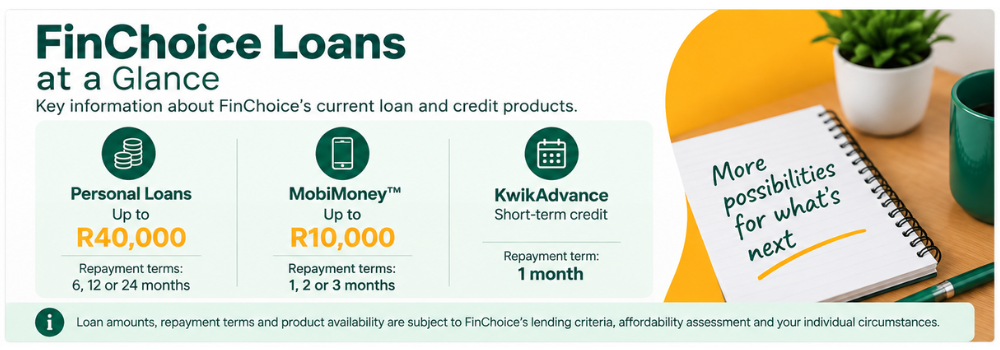
FinChoice offers personal loans of up to R40,000, with repayment terms of 6, 12 or 24 months. It also offers MobiMoney™, a separate flexible credit facility of up to R10,000.

You can also explore other providers in the FatCat Loans lender network before choosing a loan.

Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.

Understanding FinChoice as a Lender

FinChoice operates as a digital credit provider, with applications and account management available through its online and mobile platforms.

Applications remain subject to FinChoice’s lending criteria, affordability assessment and credit checks. The amount and terms offered will depend on the applicant’s individual circumstances.

FinChoice applications remain subject to its lending criteria, affordability assessment and credit checks. The amount and terms offered will depend on the applicant’s individual circumstances.

FinChoice Loans at a Glance

Borrowers often want a quick overview before reading the full review. Here are some of the key features of FinChoice loans and related credit products:

Feature FinChoice information
Personal loan amount Up to R40,000
Personal loan term 6, 12 or 24 months
MobiMoney Up to R10,000
MobiMoney repayment 1, 2 or 3 months
Application Online/mobile
Credit check Yes
Proof of income Last 3 bank statements or payslips
Account access FinChoice mobi login

Because product type, repayment length, and total borrowing cost can vary, borrowers should always review the official quotation carefully before accepting any offer.

FinChoice loan amounts and repayment terms

FinChoice Loan Types

FinChoice currently offers several credit products with different borrowing limits and repayment structures:

FinChoice Personal Loan

FinChoice personal loans are available for amounts of up to R40,000, with repayment over 6, 12 or 24 months. FinChoice states that approved funds can be deposited into your bank account in as little as 24 hours.

FinChoice MobiMoney™

MobiMoney is a flexible credit facility offering access to up to R10,000. Customers can make multiple withdrawals of R100 or more and repay withdrawals over 1, 2 or 3 months.

FinChoice KwikAdvance

KwikAdvance is FinChoice’s short-term, one-month credit product designed for smaller cash needs before payday.

The product and amount available to you will depend on FinChoice’s lending criteria and your individual circumstances.

Eligibility and Approval Considerations

FinChoice applies affordability and credit assessments before approving loan applications. These assessments typically consider:

  • Income level and consistency
  • Existing financial commitments
  • Credit history

Approval is not guaranteed. FinChoice considers factors including income, existing financial commitments, credit information and affordability when assessing an application.

The amount, interest rate and repayment terms offered can therefore differ between applicants.

FinChoice Loan Requirements and Documents

When applying for a FinChoice personal loan, you may need to provide information including:

  • Your South African ID number
  • Your registered cellphone number
  • Employment details
  • Your net monthly income
  • Your last three bank statements or payslips

FinChoice also performs a credit bureau enquiry as part of the application process. Approval and the amount offered depend on its credit criteria, affordability assessment and your individual financial circumstances.

FinChoice Login: How to Access Your Account

To check your loan status, balances or manage your account online:

  1. Go to the official FinChoice website.
  2. Select Login to your account.
  3. Enter your registered cellphone number and password.
  4. Follow the on-screen instructions to access your account.

Once logged in, existing customers can use FinChoice’s online account services to manage their FinChoice products and access available account information.

FinChoice Contact Details

If you need help with an existing FinChoice account, application or payment, you can contact FinChoice through its official customer-service channels.

Customer service 0861 346 246
Email [email protected]
Document uploads [email protected]
Physical address 78 Main Road, Wynberg, Cape Town, 7800
Website www.finchoice.mobi

Contact details checked against FinChoice’s official website in September 2026. Contact channels and operating hours may change, so confirm the latest details directly with FinChoice.

FinChoice login and contact details

Is FinChoice Legitimate and Registered in South Africa?

FinChoice operates through registered financial-services and credit-provider entities. Its official website currently lists:

  • Finchoice Africa Ltd – registered credit provider NCRCP 8162 and authorised financial services provider FSP 46962.
  • Finchoice SA (Pty) Ltd – authorised financial services provider FSP 52725.
  • Finchoice Finance (Pty) Ltd – registered credit provider NCRCP 23514.

You can independently verify registered credit providers using the National Credit Regulator’s Register of Registrants.

What to Check Before Accepting a FinChoice Loan Offer

Before accepting any loan agreement, borrowers should review more than just the speed of approval or the monthly instalment. A lower monthly payment can still lead to a higher total repayment cost over time.

Check the following carefully in your quotation or pre-agreement statement:

  • The total repayment amount over the full term
  • The interest rate and whether pricing is fixed or variable where applicable
  • Any initiation, service, admin, or account fees
  • The exact repayment dates and debit order timing
  • Any credit protection or optional cover included in the loan cost
  • The process for early settlement if you want to repay sooner

Comparing the full cost of credit can help you understand what you will actually repay rather than focusing only on the advertised convenience or speed of access.

Comparing FinChoice With Other Lenders

When comparing FinChoice with providers such as Wonga loan alternatives or ABSA loan options, consider factors such as:

  • Repayment term
  • Monthly affordability
  • Total amount repayable
  • Eligibility and credit requirements
  • How quickly approved funds may be available

Different lenders may suit different borrowing needs, so it is worth comparing the full cost and repayment structure rather than focusing only on approval speed or the advertised loan amount.

If you want to explore other providers, the FatCat Loans lender network gives you an overview of the lenders and loan options available through our platform.

Compare FinChoice loan options with alternative lenders

Frequently Asked Questions About FinChoice Loans

How much can I borrow from FinChoice?

FinChoice currently offers personal loans of up to R40,000. The amount you qualify for depends on FinChoice’s lending criteria, affordability assessment and your individual financial circumstances. FinChoice also offers MobiMoney™, a flexible credit facility of up to R10,000.

What are the FinChoice loan repayment terms?

FinChoice personal loans can currently be repaid over 6, 12 or 24 months. MobiMoney withdrawals can be repaid over 1, 2 or 3 months. Always check the repayment term and total amount repayable shown in your individual quotation before accepting credit.

How do I log in to my FinChoice account?

Go to the official FinChoice mobi website and select Login to your account. Enter your registered cellphone number and password to access your account. First-time mobi users can register through the same website.

What if I forgot my FinChoice password?

Select Forgot password? on the FinChoice login page. FinChoice asks for your cellphone number and ID number and sends a 4-digit verification code to your cellphone as part of the password-reset process.

What are the FinChoice contact details?

You can contact FinChoice on 0861 346 246 or email [email protected]. FinChoice lists its physical address as 78 Main Road, Wynberg, Cape Town, 7800. Always confirm contact information on the official FinChoice website before sharing personal or banking information.

What documents do I need for a FinChoice loan?

FinChoice’s current document-upload service asks for your last three bank statements or payslips as proof of income. The application process also requests information such as your South African ID number, cellphone number, employment details and net monthly income. Additional information may be requested depending on your application.

Does FinChoice perform a credit check?

Yes. FinChoice states during its application process that applicants give permission for a credit bureau enquiry. FinChoice may also use credit-bureau information when assessing affordability and making credit decisions.

Is FinChoice a registered credit provider in South Africa?

FinChoice operates through several registered entities. Its official website currently lists Finchoice Africa Ltd as registered credit provider NCRCP 8162 and authorised financial services provider FSP 46962. It also lists Finchoice Finance (Pty) Ltd as registered credit provider NCRCP 23514 and Finchoice SA (Pty) Ltd as authorised financial services provider FSP 52725.

Fraud and Impersonation Warning

FinChoice states that it will never ask you to share your card number, card PIN, OTP or banking password through any channel.

Before sharing personal or banking details, borrowers should make sure they are using the lender’s official website or official communication channels. Loan scams often copy the branding of real lenders and then ask for upfront payments or sensitive documents.

Watch for warning signs such as:

  • Requests for upfront “release”, “activation” or “processing” fees
  • Messages from unofficial numbers, social accounts, or lookalike domains
  • Pressure to act immediately without reviewing the quotation properly
  • Requests to send sensitive documents over unverified channels

If anything feels suspicious, stop and verify the lender’s official website before continuing. This is especially important when applying for digital credit products.

Final Thoughts

FinChoice offers several digital credit options in South Africa, including personal loans of up to R40,000 and the MobiMoney flexible credit facility.

Before accepting an offer, check the interest rate, fees, repayment term, monthly instalment and total amount repayable shown in your quotation. The right borrowing option depends on your own affordability and financial circumstances.

If you want to consider alternatives, FatCat Loans can help you compare loan options from multiple South African lenders before you apply.

Sources & Verification

We checked the information in this FinChoice loans review against current FinChoice information and South African consumer-credit sources. Key sources include:

Product information, login information and contact details were checked in September 2026. Loan amounts, interest rates, fees, eligibility requirements and other terms can change. Always check your individual quotation and FinChoice’s official website before accepting a credit agreement.

Wonga Loans South Africa (2026): Requirements, Costs & Alternatives

Wonga is one of the best-known online lenders in South Africa, offering short-term credit through a fully digital application process. This guide explains how Wonga loans work, what to consider before applying, and how to compare Wonga with other lenders to find a repayment plan that suits your budget.

Wonga Loans in South Africa

Last Updated: September 2026

Wonga is one of the most recognisable names in the local credit market, especially among borrowers looking for fast, digital loan options. Over time, the brand has become closely associated with short-term lending and online applications.

While this lender is often seen as convenient, it’s still important to understand how its products work, who they suit best, and how they compare with other providers. Applying without comparing alternatives can lead to higher costs or repayment terms that are difficult to manage.

That’s why many borrowers choose to compare loan options from multiple lenders before making a decision. Comparing lenders gives you a clearer view of affordability, repayment flexibility, and whether another provider may be a better fit.

Important: FatCat Loans is a loan comparison platform and is not affiliated with, endorsed by, or owned by the lender mentioned on this page. Loan criteria, fees and availability can change—always confirm details on the lender’s official website.

Wonga is an NCR-registered online credit provider in South Africa offering short-term loans via a fully digital application. Your approved amount, total repayment and repayment dates depend on affordability checks and verification. Borrowers should always apply directly through the lender’s official website or service provider site when submitting an application.

Compare Wonga Loan options with FatCat Loans

Wonga South Africa: Quick Summary

Wonga is a registered online credit provider in South Africa (NCRCP12875) offering short-term personal loans through a fully digital application process. Loan amounts and repayment terms depend on your profile and whether you’re a new or returning customer, and all applications are subject to affordability checks and credit assessment.

Quick Actions (Login & Contact Info)

  • Official Wonga website: Wonga.co.za (always verify the domain before entering your ID number).
  • Wonga login: Go to the official login page, enter your SA ID number, and use the OTP sent to you.
  • Customer care / collections contact: Phone 0861 966 421 and use the official “Explore Wonga” contact page for the Cape Town address.

Who Should Avoid Wonga-Style Short-Term Loans?

Short-term loans can be useful in emergencies, but they’re usually not the best choice if:

  • Your budget is already stretched each month
  • You’re using credit repeatedly to cover basic expenses
  • You’re juggling multiple repayments
  • You need a longer repayment period to keep instalments affordable

In these cases, comparing longer-term personal loans or structured consolidation options is usually safer.

Understanding Wonga as a Lender

Wonga operates as a digital-first credit provider. Unlike traditional banks, it does not rely on physical branches and instead offers an online application and account management process.

This model appeals to borrowers who value speed, convenience, and less paperwork.

Because of this structure, the lender is usually compared with other online providers rather than long-term banking products.

Is Wonga Legit and Regulated in South Africa?

Yes — Wonga Online (Pty) Ltd is a registered credit provider and displays its NCR registration details publicly. When you borrow from any lender in South Africa, you should always confirm that the provider is registered with the National Credit Regulator (NCR) and that the loan agreement clearly shows interest, fees, and repayment dates.

Important: Wonga South Africa operates as a local company, and references to the UK version of Wonga can cause confusion. The South African operation displays its own company and NCR registration details on its official website.

Safety Check: Verify any lender before you apply

Before submitting an application (to Wonga or any alternative), do this quick verification:

  • Confirm the lender displays an NCR registration number and company details, and cross-check on the National Credit Regulator database.
  • Never pay upfront for “processing” or “release” fees (this is a common scam pattern).
  • If you suspect fraud, use our Fraud Alert guide to protect yourself.

Types of Loans Commonly Associated With Wonga

Searches for this lender typically relate to the following types of credit:

  • Short-term personal loans
  • Medium-term instalment loans
  • Fixed-repayment online loan products

These loan options are often used to:

  • Cover unexpected expenses
  • Bridge short-term cash flow gaps between income cycles
  • Handle urgent once-off costs that can’t wait until the next salary date

Because repayment periods are usually shorter, monthly instalments may be higher than those of long-term loans. Understanding this trade-off is essential before applying.

If you’re considering Wonga for urgent costs, it helps to compare similar short-term loans in South Africa to ensure you’re getting a repayment structure you can afford.

Compare loans and apply for a Wonga Loan today

How Much Can You Borrow From Wonga?

Wonga’s advertised loan limits depend on your customer history and affordability profile:

  • Short-term loans from R500 up to R5,000 are promoted on Wonga’s official South African website.
  • In general, first-time borrowers may qualify for lower limits, while returning customers with strong repayment history may qualify for higher amounts — depending on affordability checks and lender criteria.

Your approved amount is based on affordability and risk assessment — not only what the website advertises.

Why Many Borrowers Consider Wonga

Wonga appeals to a specific type of borrower. Many people who search for Wonga credit options are:

  • Salaried individuals who need quicker access to funds than traditional banks may offer
  • Consumers comfortable with online applications
  • Borrowers who prefer a simple digital process with minimal paperwork

Search behaviour often includes phrases such as:

  • Wonga loan alternatives
  • Wonga repayment options
  • Wonga vs other lenders

This indicates that most borrowers are comparing options rather than committing immediately.

Eligibility and Approval Considerations

Like all registered credit providers, Wonga applies affordability and risk assessments before approving a loan. These assessments typically consider:

  • Monthly income
  • Living expenses
  • Existing debt obligations

Approval outcomes and interest rates can vary significantly depending on the applicant’s financial profile. Borrowers with stable income and lower debt levels may receive more favourable terms, while others may find repayments more challenging.

This is why using a platform that allows you to compare lenders in one place can be beneficial before submitting an application.

If you have negative listings or past missed payments, our guide to loans for blacklisted consumers explains what lenders consider and what alternatives may be available.

Wonga Loan Requirements (What You Usually Need)

To apply, applicants typically need:

  • A valid South African ID number
  • One of your active bank accounts for payout and repayment purposes
  • Proof of income, such as a payslip or recent bank statement
  • A working cellphone number and email address for verification and communication

Lenders may also review activity across your bank accounts as part of affordability and verification checks.

Requirements can change, and additional verification may be requested depending on the lender’s compliance process.

Approval outcomes vary based on affordability and credit assessment, and meeting the minimum requirements doesn’t guarantee approval.

Wonga Login (South Africa): Step-by-Step

Existing Wonga customers can access their accounts through the official Wonga login page.

To log in safely:

  1. Visit wonga.co.za/login directly.
  2. Enter the identification or account details requested by Wonga.
  3. Complete any verification step displayed on the official website.
  4. Once logged in, follow the available options to view or manage your account.

If you cannot access your account, check that your details have been entered correctly and use the recovery or support options provided by Wonga. Do not share a password, PIN or one-time PIN with anyone claiming that they can log in or manage the account for you.

Important: FatCat Loans is an independent loan-comparison website. We are not Wonga and cannot access your Wonga account, reset your login details, check an application or manage an existing loan.

For security, confirm that the address in your browser begins with https://www.wonga.co.za/ before entering any personal or banking information. Avoid login links received through unexpected emails, text messages, WhatsApp messages or social-media accounts.

Advantages Often Associated With Wonga Loans

Borrowers often consider Wonga because of:

  • Fully online applications with quick turnaround times (subject to verification)
  • Clear repayment schedules
  • Accessibility for borrowers who may not want lengthy bank applications

For individuals facing urgent financial needs, these features can be appealing.

Important Limitations to Consider

Despite its convenience, Wonga may not be suitable for everyone. Potential limitations include:

  • Shorter repayment periods that increase monthly instalments
  • Higher overall costs compared to longer-term loans
  • Limited flexibility for borrowers managing multiple debts

For these reasons, Wonga is often best suited for short-term financial requirements rather than long-term debt management.

What Do Wonga Loans Cost? (Interest, Fees and Total Repayment)

The biggest mistake borrowers make with short-term credit is focusing only on the amount they receive — instead of the total amount they repay.

Before accepting any Wonga loan offer, check:

  • The total repayment amount
  • The repayment date(s)
  • Any initiation or service fees
  • What happens if payment is late

All loan costs should comply with the National Credit Act, which regulates fees, charges, and interest rates depending on the type of credit agreement.

A responsible lender should clearly show you a breakdown before you accept the agreement. If the instalment feels tight, the loan is likely to create pressure later.

Tip: If you’re using short-term credit repeatedly, it may be a sign that a longer-term personal loan or debt consolidation approach is more suitable.

Before accepting any short-term loan quote, screenshot/record these 5 numbers:

  1. Cash you receive (net payout)
  2. Total repayment (all-in)
  3. Repayment date(s) / debit order date(s)
  4. Initiation fee + monthly service fee (if applicable)
  5. Late fee rules + rescheduling options

Why it matters: many borrowers compare only the loan amount, not the total repayment—this is where short-term credit becomes expensive fast.

What Happens If You Miss a Wonga Repayment?

Missing a repayment can increase your overall cost and may negatively affect your credit profile. Late payments can lead to additional fees and can be recorded on your credit report depending on the lender’s reporting practices.

If you think you may struggle to repay:

  • Contact the lender before the due date
  • Ask about restructuring or alternative arrangements
  • Avoid taking additional short-term credit to cover repayments (this is how debt cycles start)

If you’re already struggling with multiple repayments, it may help to explore debt consolidation options that reduce monthly repayments rather than taking another short-term loan.

Missing payments can affect your profile, so it’s worth learning how to check your credit score in South Africa and monitoring what lenders see before applying again.

Wonga Contact Details (South Africa)

Use official channels so you don’t share personal details with impersonators.

  • Telephone: 0861 966 421
  • Physical address (Cape Town): 1st floor, 14 Kloof Street, Gardens, Cape Town, 8001
  • Registration: Wonga states it is an NCR-registered credit provider (NCRCP12875).

Tip: If you’re contacting them because repayment will be late, reach out before the due date to discuss arrangements (this reduces knock-on fees and credit harm).

Wonga’s South African customer care contact is 0861 966 421, with its Cape Town address listed as 1st floor, 14 Kloof Street, Gardens, 8001. Use official contact pages to avoid impersonation scams, especially when discussing repayments or account access.

Comparing Wonga With Other Loan Providers

Wonga is one of many lenders available to South Africans. Other providers may offer:

  • Longer repayment periods
  • Different affordability models
  • More flexible loan structures

By using FatCat Loans to compare loan and credit options, borrowers can see how this lender compares with other available providers before making a commitment.

This helps reduce the risk of choosing a loan that becomes difficult to manage over time.

Wonga vs Other Online Loan Providers (Quick Comparison)

Provider type Best for Typical repayment style Key risk to watch
Wonga-style online loans Short-term urgent expenses Short repayments / fixed instalments Higher monthly instalments
Bank personal loans Larger amounts + longer terms Monthly instalments over longer term Slower approval process
Retail/Store accounts Small credit limits Monthly minimum payments High interest if you revolve balance
Debt consolidation loans Combining multiple debts One structured repayment Total cost depends on term and rate

The safest approach is to compare multiple offers side-by-side and choose the option that matches your budget, not the one with the fastest approval.

When Wonga May Be a Good Fit

Wonga may suit borrowers who:

  • Need fast access to funds (instant loans)
  • Prefer a fully online application process
  • Have short-term financial needs

In these scenarios, Wonga’s digital model can provide a convenient solution.

When Wonga May Not Be the Right Option

Wonga may be less suitable if you:

  • Are looking for long-term repayment flexibility
  • Are managing multiple existing debts
  • Prefer structured bank-style loan products

In such cases, alternative lenders may offer more appropriate solutions.

Alternatives if Wonga Is Not the Right Fit

If Wonga does not align with your needs, other providers such as Finchoice loan options or ABSA loan solutions may offer different repayment terms or approval criteria.

Exploring alternatives helps ensure that you choose a loan that matches your affordability and financial goals rather than simply opting for the fastest option.

If you need a larger amount or want lower monthly instalments, consider personal loan options with longer repayment terms instead of short-term credit.

How FatCat Loans Helps You Compare Wonga With Other Options

Borrowers who want to compare Wonga with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.

FatCat Loans helps South Africans compare loan options from multiple lenders, including digital lenders like Wonga and more traditional financial institutions. By using a comparison platform, you can:

  • Review different loan structures
  • Compare repayment terms
  • Identify alternatives without applying to multiple lenders individually

This comparison-first approach supports smarter financial decision-making and reduces the likelihood of rejection.

Compare Wonga loan options with alternative lenders.

Frequently Asked Questions About Wonga Loans

Is Wonga a registered lender in South Africa?

Yes. Wonga Online (Pty) Ltd displays its registration as a credit provider with the National Credit Regulator (NCRCP12875).

How much can I borrow from Wonga?

Wonga advertises short-term loans from R500 up to R5,000. Some reviews report higher limits for returning customers depending on affordability and repayment history.

What do I need to apply for a Wonga loan?

Applicants typically need a South African ID number, proof of income, and an active bank account.

How fast does Wonga pay out?

Payout speed varies by verification and banking times, but Wonga promotes fast, online decisions and bank transfers after approval.

Can I get a Wonga loan if I have bad credit?

Approval depends on affordability checks and lender risk criteria. If you have negative listings, compare other lenders and consider reading our guide to loans for blacklisted consumers.

What are the risks of using short-term loans like Wonga?

The main risks include higher monthly instalments, repeat borrowing cycles, and higher total costs if you struggle to repay on time.

Should I compare Wonga with other lenders first?

Yes. Comparing offers can help you find lower monthly repayments, different repayment terms, and more competitive interest rates that better suit your budget.

If you still have questions, see our FAQ about applying for loans.

How do I log in to Wonga in South Africa?

Use the official login page, enter your SA ID number and complete OTP sign-in.

What are Wonga’s official contact details in South Africa?

Phone 0861 966 421 and use the official contact page for the Cape Town address.

How can I verify Wonga is registered with the NCR?

Check that the lender displays an NCR number and confirm it against the National Credit Regulator database (never rely on third-party directories alone).

What should I do if I think a “Wonga agent” is scamming me?

Do not pay upfront fees or share OTPs. Stop contact and follow FatCat Loans’ Fraud Alert steps before continuing.


Final Thoughts

Wonga remains a well-known option in South Africa’s online lending space, particularly for borrowers seeking quick and accessible credit. However, convenience should not be the only factor when choosing a loan.

By taking the time to compare Wonga with other lenders, you gain a clearer understanding of repayment obligations, affordability, and alternative options that may better suit your needs. FatCat Loans simplifies this process by bringing multiple lenders together, helping you make confident and informed financial decisions.

Disclosure:  This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

Sanlam Loans South Africa (2026): Rates, Requirements & Alternatives

Sanlam is one of South Africa’s most established financial services groups, and many borrowers explore Sanlam loans or credit options when planning long-term financial commitments. This guide explains how Sanlam fits into the lending landscape, who its structured credit solutions may suit, and why comparing alternatives can help you choose the most affordable option.

Sanlam Loans South Africa

Last Updated: September 2026

Sanlam is one of South Africa’s most established financial services groups, widely recognised for insurance, investments, and long-term financial planning. Because of this reputation, many South Africans search for Sanlam loans or Sanlam personal loans when comparing credit options from established lenders.

Unlike many short-term lenders, Sanlam’s personal loans are typically positioned as a more structured borrowing solution, with repayment terms designed to support affordability and predictability. However, as with any credit product, the best loan isn’t always the most familiar brand — it’s the one that matches your budget and financial goals.

That’s why it’s worth understanding how Sanlam loans work, what you may qualify for, and how Sanlam compares with other lenders before applying.

If you’re comparing Sanlam with other borrowing options, you can also compare lenders in South Africa through FatCat Loans before deciding which loan structure may suit your needs.

Important: FatCat Loans is a loan comparison service and is not affiliated with, endorsed by or owned by Sanlam. Sanlam may not be one of the lenders available through our comparison service. Loan amounts, rates, fees and eligibility criteria can change. Always confirm the terms of your individual quotation and pre-agreement statement before accepting credit.

Compare Sanlam loan options with alternative lenders

Understanding Sanlam as a Lender

Sanlam provides credit solutions through its broader financial services ecosystem. While it is best known for insurance and investments, Sanlam also offers personal loans through its credit solutions service, aimed at borrowers who prefer structured repayments and predictable budgeting.

Sanlam loans are generally positioned for:

  • borrowers who want a fixed repayment structure
  • medium- to larger loan amounts compared to typical short-term lenders
  • borrowers who value brand credibility and regulated lending processes

Sanlam Loans South Africa: Quick Summary (2026)

Sanlam offers unsecured personal loans through its credit solutions platform, with loan amounts that can reach up to R350,000, depending on affordability and credit assessment. Repayment terms are flexible and can extend up to 84 months for qualifying applicants.

Sanlam operates under South African lending regulations, and its loans are subject to affordability checks and credit bureau assessment, as required by the National Credit Act.

Sanlam Personal Loan Feature Details
Loan amount R5,000 – R350,000
Repayment term 12 – 84 months
Loan type Unsecured personal loan
Interest rate Personalised according to credit profile and affordability
Maximum APR shown Up to 27.29%
Initiation fee Up to R1,207.50
Monthly service/admin fee R69
Application Online
Credit & affordability assessment Yes
Registered credit provider Sanlam Life Insurance Limited – NCRCP43

Loan amounts, rates, fees and terms are subject to Sanlam’s assessment and can change. Always check your individual quotation before accepting credit.

Sanlam Personal Loan Costs (Quick Facts You Can Compare)

Sanlam personal loans are unsecured loans in South Africa where borrowers can apply for R5,000 to R350,000 and repay over 12 to 84 months, with pricing based on credit profile and affordability checks. Sanlam shows a maximum APR of 27.29%, with fees such as an initiation fee (up to R1,207.50) and a R69 monthly admin fee.

Based on Sanlam’s own loan information and calculator examples, borrowers should compare the full cost of credit — not only the monthly instalment.

  • Maximum APR shown: up to 27.29% (your personalised rate depends on your credit score).
  • Indicative interest range shown: 16%–27.75%.
  • Fees shown in Sanlam’s example: initiation fee up to R1,207.50 and a R69 monthly admin/service fee.
  • Worked example (from Sanlam): a R50,000 loan at 24.5% annual interest is shown costing R102,085.93 over 6 years (their example includes the fees listed above).

These figures reflect Sanlam’s published example rather than a guaranteed quotation. Your actual rate, fees and repayment will depend on your individual offer.

Tip: When comparing alternatives, always compare total repayment, APR, fees, and the term side-by-side — not just “approval speed”.

Sanlam Credit Solutions: Credit Dashboard + Credit Score Access

Sanlam positions its Credit Solutions offering as more than just a loan. It promotes a Sanlam Credit Dashboard with access to a free credit score updated monthly, plus support from credit experts to help match solutions to your needs.

Why this matters (YMYL):
Before taking new credit, checking your score and understanding your affordability can help you avoid repayments that strain your budget.

Is Sanlam Legit and Regulated in South Africa?

Yes. Sanlam Life Insurance Limited publicly states that it is a licensed life insurer, authorised financial services provider, and a registered credit provider (NCRCP43) in South Africa.

Consumers can also verify registered credit providers through the National Credit Regulator (NCR).

When borrowing from any lender, you should always confirm:

  • the lender is registered with the National Credit Regulator (NCR)
  • the agreement includes total repayment amount, fees, and repayment schedule
  • the instalment is affordable without putting your household under financial strain

Does Sanlam Offer Personal Loans?

Yes. Sanlam promotes personal loans through its official credit solutions pages, where applicants can apply online and estimate repayments using a loan calculator. Loan offerings and rates vary based on affordability and credit profile.

Sanlam’s loan offering is generally described as:

  • unsecured personal loans
  • fixed instalments
  • structured repayment terms

How a Sanlam Personal Loan Application Works (Step-by-Step)

Sanlam’s process is positioned as a structured personal loan journey:

  • Choose your amount: Sanlam indicates you can apply from R5,000 to R350,000 (in R1,000 increments).
  • Choose your repayment term: typically 12 to 84 months (the best term balances affordability with total cost).

If approved, Sanlam indicates your loan amount could be paid into your bank account within 24 hours, depending on how quickly you submit the required supporting documents.

  • Affordability assessment: Sanlam states it considers your finances and won’t lend more than you can afford.
  • Submit supporting documents: commonly listed by Sanlam as:
    • Copy of SA ID
    • Proof of residential address
    • 3 months’ bank-generated PDF statements / payslips (as proof of income)

Payout timing: depends on document submission speed

What to prepare before you apply (to reduce delays)

Have these ready before you start:

What to Prepare Why It’s Needed
South African ID Identity verification
Proof of residential address Address verification
3 months’ payslips or bank statements Income and affordability assessment
Your monthly income and expenses To assess whether the repayment is affordable

If you want to compare instalments and total repayment across multiple providers first, use our hub: Compare Loans South Africa

If completing the application digitally is important to you, you can also compare online loan options in South Africa from other participating providers.

How Much Can You Borrow From Sanlam?

Sanlam advertises personal loans of up to R350,000 for qualifying applicants, with repayment terms that can extend up to 84 months depending on affordability and risk assessment.

Your approved amount is based on:

  • income stability
  • existing debt commitments
  • credit history and credit score
  • affordability assessment (income vs expenses)

Repayment Terms: How Long Do You Get to Repay?

Sanlam promotes repayment periods that can range from 12 months up to 84 months for qualifying borrowers.

Longer repayment terms can reduce monthly instalments — but may increase the total cost of credit over time. The right term is the one that balances affordability with total repayment cost.

If you prefer borrowing with scheduled monthly repayments, you can also compare instalment loan options in South Africa before deciding which repayment structure best fits your budget.

Sanlam Loan Requirements (What You Usually Need)

To apply for a Sanlam personal loan, applicants generally need:

  • a valid South African ID
  • a South African bank account
  • proof of income (payslip or bank statements)
  • contact details for verification

Approval is always subject to affordability checks and credit assessment.

If you want to check where you stand before applying, this guide on how to check your credit score in South Africa explains what lenders typically review and how to access your report.

Does Sanlam Perform a Credit Check?

Yes. Sanlam assesses your credit profile and affordability before deciding whether to offer a personal loan.

The assessment can consider your credit history, existing financial commitments, income and other information relevant to whether the proposed repayment is affordable.

This means Sanlam does not offer guaranteed approval simply because you meet the basic application requirements.

If you’re unsure how lender enquiries work, read our guide to soft vs hard credit checks in South Africa.

What Do Sanlam Loans Cost? (Interest, Fees and Total Repayment)

Sanlam personal loans are priced based on your credit profile, affordability assessment, and loan term. The most important figure to compare isn’t only the monthly instalment — it’s the total cost of credit, including any fees.

Before accepting any loan offer, always confirm:

  • total repayment amount
  • initiation and service fees
  • interest rate and whether it is fixed or variable
  • early settlement options and penalty rules
  • what happens if a payment is missed

Borrowing is safest when the instalment fits comfortably into your budget, even if an emergency expense comes up.

Sanlam personal loan costs and terms to compare

Sanlam Wealth Bonus®: What It Is (And What to Watch For)

Sanlam highlights a rewards benefit where borrowers can earn up to 10% of the loan amount in rewards (often referenced as Wealth Bonus®).

However, Sanlam also explains that how and when Wealth Bonus “unlocks” depends on the product rules, and that locked Wealth Bonus can be lost if you cancel/lapse (and it can also be impacted by market underperformance, since it behaves like an investment).

How to use this when comparing lenders:

  • Treat rewards as a bonus, not the main reason to borrow.
  • Your primary comparison points should still be: APR, fees, total repayment, and affordability.

Who Typically Chooses Sanlam Loans?

Sanlam loans are often considered by borrowers who:

  • earn a stable income
  • want predictable repayments
  • need medium to higher loan amounts
  • prefer borrowing from a well-known regulated provider

This may make Sanlam more suited to planned borrowing, such as home improvements, consolidation or major purchases, than to urgent short-term cash needs.

Pros and Cons of Sanlam Loans

Like any financial product, Sanlam loans have advantages and limitations. Understanding both can help you decide whether this lender fits your financial situation.

Pros

  • Well-known and regulated South African financial services provider
  • Loan amounts up to R350,000 for qualifying applicants
  • Structured repayment terms up to 84 months
  • Access to Sanlam’s credit dashboard with a free credit score

Cons

  • Approval depends on strict affordability and credit checks
  • Longer repayment terms can increase total loan cost
  • May not be ideal for very small or urgent short-term loans
  • Interest rates vary depending on credit profile

If you’re unsure whether Sanlam fits your needs, comparing multiple lenders can help you evaluate different loan amounts, repayment terms and borrowing costs.

When Sanlam May Be a Good Fit

Sanlam may suit you if you:

  • need a larger personal loan amount
  • want structured repayments over a longer term
  • have stable income and meet affordability requirements
  • prefer a regulated lender with strong brand credibility

When Sanlam May Not Be the Right Option

Sanlam may be less suitable if you:

  • need urgent same-day access to funds
  • have irregular income and struggle to show consistent affordability
  • are already managing multiple repayments
  • need very short-term credit for a small amount

In these cases, other lenders may offer faster solutions — but the total cost may differ significantly.

Checklist before applying for a Sanlam personal loan

Comparing Sanlam With Other Lenders (Quick Guide)

Sanlam is often compared to:

  • bank personal loans (longer terms, sometimes stricter approval)
  • alternative lenders (faster approvals, often smaller amounts)
  • digital credit providers (convenient, but usually shorter terms)

If you want to compare options side-by-side, exploring personal loan options with longer repayment terms can help you see whether another provider offers better affordability for your budget.

If You’re Struggling With Multiple Debts, Compare Consolidation Options

If you already have multiple repayments, taking another personal loan may create more strain. In many cases, consolidation could reduce monthly pressure by combining repayments into one structured instalment.

If you’re juggling multiple commitments, explore debt consolidation loan options in South Africa and compare the new repayment, term and total cost with your existing debts before proceeding.

Compare Sanlam loan options with alternative lenders

How FatCat Loans Helps You Compare Sanlam With Other Options

Borrowers who want to compare Sanlam with other providers can use FatCat Loans’ lender network to explore multiple loan options in one place.

FatCat Loans helps South Africans compare loan and credit options from multiple providers in one place. Rather than applying to multiple lenders individually, you can:

  • compare repayment terms and affordability
  • evaluate alternatives objectively
  • choose the option that best fits your financial profile

Comparing options before applying can help you understand different repayment structures, costs and eligibility requirements before deciding which type of loan may suit your circumstances.

Scam Warning: How to Spot Fake “Sanlam Loan” Offers

Sanlam explicitly warns consumers to be cautious with suspicious loan communications and highlights red flags such as messages that pressure you to act quickly or demand upfront payments.
Sanlam also warns more broadly about the rise of loan scams targeting consumers who struggle to access verified credit.

If you see any of these red flags, stop and verify first:

  • Upfront payment requested “to release the loan”
  • “Guaranteed approval” without checks
  • Unrealistically low interest promises
  • Urgency tactics (“today only”, “act now”)

For more safety checks, visit our Fraud Alert page.

Frequently Asked Questions About Sanlam Loans

Does Sanlam offer personal loans?

Yes. Sanlam promotes unsecured personal loans through its official credit solutions platform, with loan amounts up to R350,000 depending on affordability and credit assessment.

How much can I borrow from Sanlam?

Sanlam advertises personal loans up to R350,000 for qualifying applicants.

How long can I repay a Sanlam personal loan?

Sanlam promotes repayment terms from 12 up to 84 months depending on your profile and affordability assessment.

Is Sanlam a registered credit provider?

Yes. Sanlam Life Insurance Limited states that it is a registered credit provider (NCRCP43).

Can I get a Sanlam loan with bad credit?

Approval depends on Sanlam’s affordability and credit assessment. A weaker credit profile may affect the rate, amount or approval outcome, but there isn’t one score that guarantees acceptance or rejection. If you’re finding mainstream borrowing difficult, you can also compare bad credit loan options in South Africa.

What interest rate does Sanlam charge on personal loans?

Sanlam shows interest rates can vary by credit profile, and displays an indicative range (e.g., 16%–27.75%) with a maximum APR shown of 27.29%. Your exact rate depends on your credit score and affordability assessment.

What fees should I expect on a Sanlam personal loan?

Sanlam’s calculator example includes an initiation fee (shown up to R1,207.50) and a monthly admin/service fee of R69. Always confirm the total cost of credit on your quote before accepting.

How long does a Sanlam loan payout take?

If approved, Sanlam indicates funds could be paid within 24 hours, depending on how quickly you provide supporting documents.

Sources & Verification (How we keep this guide accurate)

This page is maintained by the FatCat Loans South Africa Editorial Team and is reviewed against primary sources including:

  • Sanlam’s official personal loan product information (amounts, terms, fees, example repayments)
  • Sanlam Credit Solutions information (credit dashboard and solutions overview)
  • South Africa’s lending framework under the National Credit Act
  • National Credit Regulator registration information

Editorial Policy & Disclaimer

This guide is written for South African consumers and is intended for informational purposes only. It does not constitute financial, legal, or credit advice. Loan terms, rates, and eligibility vary by provider and individual affordability assessments. FatCat Loans is a comparison platform, not a lender. Always read your loan quotation and agreement carefully before accepting credit.

ABSA Loans Review South Africa (2026)

Our 2026 ABSA Loans Review covers personal loan amounts, interest rates, fees, requirements, repayment terms and how to apply.

Introduction to ABSA Loans

Last Updated: August 2026

ABSA is one of South Africa’s largest and most established banks, offering several personal lending options for both short-term and longer-term borrowing.

Its standard Personal Loan currently offers R3,000 to R350,000, with repayment terms from 12 to 84 months. ABSA also offers smaller Express and Instant Loans, as well as a Revolving Credit Facility for borrowers who want ongoing access to approved credit.

Interest rates on ABSA Personal Loans are personalised according to the borrower’s credit profile, with ABSA currently advertising rates starting from 13.75% APR. Your actual rate will depend on your individual circumstances and ABSA’s assessment.

In this ABSA Loans Review South Africa 2026, we look at ABSA’s current loan amounts, interest rates, fees, requirements, repayment terms and application process. We’ll also compare its different loan products and explain what to consider before applying.

Important Transparency Note

FatCat Loans is an independent loan comparison service and is not affiliated with ABSA. We do not provide loans directly.

Quick Verdict: Is ABSA a Good Lender?

ABSA offers a broad range of personal borrowing products, from short-term loans of a few hundred rand to Personal Loans of up to R350,000.

Its standard Personal Loan may be worth considering for borrowers who want a larger loan with structured monthly repayments and up to 84 months to repay. Existing ABSA customers also have access to additional short-term and revolving credit options.

ABSA Personal Loan at a Glance

Feature ABSA Personal Loan
Loan amount R3,000 – R350,000
Repayment term 12 – 84 months*
Interest rate Personalised
Published starting APR From 13.75% p.a.
Minimum income R2,000/month for loans of 12+ months
Credit life insurance Mandatory
Non-ABSA customers Can apply
Self-employed applicants Can be considered with additional documents

ABSA states that repayment terms from two months may be available to existing customers. All applications are subject to credit assessment, affordability and approval.

Best For

ABSA may be worth considering if you:

  • need a personal loan of up to R350,000
  • want up to 84 months to repay
  • have regular, verifiable income
  • prefer borrowing from an established bank
  • want predictable monthly repayments
  • already bank with ABSA
  • want to consolidate existing personal loans

May Not Suit

You may want to compare other options if you:

  • don’t meet ABSA’s credit or affordability requirements
  • want to borrow without a credit assessment
  • don’t want mandatory credit life insurance
  • receive a personalised rate that isn’t competitive
  • want to compare several lenders before committing

Our view: ABSA has a strong range of borrowing options, but whether its Personal Loan represents good value depends on the personalised interest rate, fees, insurance cost and total repayment offered to you.
ABSA personal loan overview

Understanding ABSA as a Lender

ABSA is a full-service South African bank offering personal lending alongside transactional accounts, savings, credit cards, home loans, vehicle finance, insurance and other financial products.

Unlike FatCat Loans or a loan broker, ABSA is the lender. If your application is approved and you accept the credit agreement, ABSA provides the funds and you repay the loan directly to the bank.

One of the main differences between ABSA and many smaller lenders is the breadth of its credit range. ABSA currently offers Personal Loans, Express Loans, Instant Loans and a Revolving Credit Facility, allowing borrowers to choose between different loan sizes and repayment structures.

Existing ABSA customers may also have access to provisional Personal Loan offers through ABSA’s digital banking channels.

Is ABSA a Legitimate and Safe Lender?

Yes. ABSA is an established South African bank operating within the country’s formal banking and consumer-credit regulatory framework.

Borrowers should still be cautious when applying for loans online. Scammers may impersonate established banks or claim that an upfront payment is required before a loan can be released.

If you decide to apply directly to ABSA, use its official website, Banking App, telephone service or branch network.

Never send money to an individual who claims they can guarantee an ABSA loan approval.

What Types of Personal Loans Does ABSA Offer?

ABSA offers several unsecured borrowing products. The main differences are the amount you can borrow, how long you have to repay and whether the credit can be reused.

ABSA product Amount Repayment How it works
Personal Loan R3,000 – R350,000 12–84 months* Standard fixed-term personal loan
Express Loan R1,500 – R8,000 1–6 months Small short-term loan
Instant Loan R350 – R8,000 Up to 35 days Very short-term loan for qualifying ABSA customers
Revolving Credit Facility R15,000 – R350,000 Revolving Reuse available credit without a new application
Switch and Save R15,000 – R350,000 12–84 months Switch/consolidate existing personal loans

ABSA currently publishes these ranges on its loan comparison and individual product pages.

ABSA states that shorter Personal Loan terms may be available to existing customers. All products are subject to their individual eligibility requirements and approval.
Types of ABSA loans compared

ABSA Personal Loan

The standard ABSA Personal Loan is designed for larger planned or unexpected expenses.

Borrowers can currently apply for R3,000 to R350,000, with standard repayment terms ranging from 12 to 84 months. Existing ABSA customers may have access to shorter terms starting from two months.

The interest rate is personalised according to your credit profile, and the loan is repaid in monthly instalments over the agreed period.

ABSA Express Loan

The Express Loan is designed for much smaller amounts that can be repaid quickly.

ABSA currently offers R1,500 to R8,000 over one to six months. Applicants need to be at least 18 and show minimum monthly income of R1,500.

ABSA states that the interest rate is fixed. It currently publishes a maximum monthly interest rate of 5% for a first loan, or 3% if another qualifying loan is taken in the same calendar year, with service and initiation fees also applying.

Because the repayment period is short, compare the total cost and monthly repayment, not just the relatively small amount borrowed.

ABSA Instant Loan

ABSA’s Instant Loan is a very short-term credit product available to qualifying ABSA customers.

You can currently access R350 to R8,000, with repayment due on your next salary date within a maximum of 35 days. Applicants need an ABSA account into which their salary is paid and regular monthly income of at least R3,000.

ABSA currently states that interest ranges from 0% to 5%, depending on the customer profile and number of Instant Loans taken during the calendar year. An initiation fee also applies.

Because the loan is repaid so quickly, make sure the deduction won’t leave you unable to cover normal expenses after your next payday.

ABSA Revolving Credit Facility

The Revolving Credit Facility works differently from a standard Personal Loan.

ABSA currently offers facilities from R15,000 to R350,000. Once you’ve repaid 15% of the facility limit, you can access funds again up to the available limit without submitting another application.

The facility has no fixed maximum term and ABSA states that applicants need:

  • regular monthly income of at least R8,000
  • an ABSA account into which their salary is paid
  • a valid South African ID
  • proof of residential address
  • to be at least 18

Interest is personalised, with ABSA currently publishing an APR up to a maximum of prime + 14%.

A revolving facility can provide useful flexibility, but repeatedly accessing repaid credit can also keep you in debt for longer.

ABSA Personal Loan Amounts, Terms and Interest Rates

For borrowers considering ABSA’s standard Personal Loan, the amount, repayment period and interest rate will determine how affordable the loan is and how much it ultimately costs.

ABSA currently offers Personal Loans from R3,000 to R350,000, with standard repayment terms from 12 to 84 months. Existing ABSA customers may have access to shorter terms starting from two months.

Typical ABSA Personal Loan Features

Feature ABSA Personal Loan
Loan amount R3,000 – R350,000
Standard repayment term 12 – 84 months
Existing-customer terms From 2 months may be available
Minimum income for 12+ month loan R2,000 per month
Interest rate Personalised
Published starting APR From 13.75% p.a.
Credit life insurance Mandatory
Non-ABSA customers Can apply
Self-employed applicants Can be considered with additional documents

Loan amounts, rates and terms are subject to ABSA’s credit assessment, affordability checks and approval.

ABSA Personal Loan Interest Rates

ABSA does not charge every Personal Loan customer the same interest rate.

Instead, the bank uses personalised pricing, meaning the rate you’re offered will depend on your individual credit and affordability profile.

ABSA currently advertises a personalised Annual Percentage Interest Rate (APR) starting from 13.75% per year.

Factors that may influence your rate include:

  • your credit history
  • your income
  • your existing debts
  • your monthly expenses
  • your overall affordability and credit profile

The advertised 13.75% starting APR should not be treated as a guaranteed rate. Your personalised rate may be higher.

Before accepting a loan, check the interest rate, fees, credit protection cost, monthly instalment and total amount repayable shown in your quotation.

Example ABSA Personal Loan Repayment

ABSA provides an illustrative example showing how a Personal Loan could be repaid:

Example Amount
Loan amount R50,000
Example interest rate 18% p.a.
Repayment term 36 months
Estimated monthly repayment R2,113

ABSA states that this example includes applicable service and initiation fees.

This is an illustration only and not a guaranteed ABSA quotation. Your actual monthly repayment will depend on the amount borrowed, your personalised interest rate, repayment period and other applicable costs.

A lower monthly repayment doesn’t necessarily mean a cheaper loan. Extending the repayment period can make monthly instalments more manageable while increasing the total amount of interest paid.
ABSA personal loan rates and terms

ABSA Loan Fees and Credit Protection Explained

The interest rate isn’t necessarily the only cost of an ABSA loan.

Depending on the product and your individual agreement, borrowing costs can include:

  • interest
  • a once-off initiation fee
  • monthly service fees
  • credit life insurance

ABSA’s own R50,000 Personal Loan example states that its estimated monthly repayment includes service and initiation fees.

The exact costs applicable to your loan should be shown in the pre-agreement statement and quotation you receive before accepting the credit agreement.

Is Credit Life Insurance Compulsory With an ABSA Personal Loan?

Yes. ABSA states that credit life insurance is mandatory for its Personal Loans.

ABSA’s Credit Protection Plan can provide cover for specified events including:

  • death
  • permanent disability
  • temporary disability
  • terminal illness
  • critical illness
  • loss of income under the applicable plan

Depending on the insured event and applicable cover, the policy may settle the outstanding loan balance or temporarily cover loan instalments.

Credit protection provides valuable cover, but the premium also contributes to the overall cost of borrowing.

Before accepting a loan, compare the total cost of credit rather than looking only at the advertised interest rate or monthly instalment.

Can You Consolidate Debt With ABSA?

Yes. ABSA offers a Switch and Save option that allows qualifying borrowers to move existing personal loans to ABSA and potentially combine multiple loans into one facility.

ABSA currently allows qualifying personal loans of up to R350,000 to be switched. The bank states that it can settle your existing loans directly with your current lenders, reducing the amount of administration required from you.

Borrowers may also be able to request additional funds as part of the new loan, subject to ABSA’s credit assessment, affordability requirements and approval.

Potential benefits of consolidation can include:

  • combining several loan repayments into one
  • having one repayment date to manage
  • receiving a personalised interest rate
  • potentially restructuring the repayment period

However, debt consolidation does not automatically reduce the total cost of your debt.

Before switching, compare the new interest rate, fees, insurance costs, repayment period and total amount repayable with your existing loans.

A longer repayment period could reduce your monthly instalment while increasing the total amount of interest you pay.

Who Qualifies for an ABSA Personal Loan?

ABSA assesses every Personal Loan application individually, so meeting the basic eligibility requirements does not guarantee approval.

For a Personal Loan with a repayment period of 12 months or longer, ABSA currently states that applicants need to:

  • be at least 18 years old
  • earn a regular monthly income of at least R2,000
  • have a bank account into which their income is paid
  • meet ABSA’s credit and affordability requirements

For smaller Personal Loans over two to six months, applicants need regular monthly income of at least R1,500 and an active ABSA account into which their income is paid.

ABSA will also assess factors such as your credit profile, income, existing debts, monthly expenses and ability to afford the proposed repayments.

Does ABSA Have a Minimum Credit Score?

ABSA does not publish a specific minimum credit score that guarantees approval for its standard Personal Loan.

Instead, the bank considers your broader credit profile and affordability when assessing an application.

A stronger credit history may improve your chances of approval or help you qualify for more favourable terms, but approval and pricing remain subject to ABSA’s assessment.

What Documents Do You Need for an ABSA Personal Loan?

ABSA currently states that Personal Loan applicants may need:

  • a valid South African ID book or Smart ID card
  • the last three months’ payslips or bank statements
  • proof of residence not older than three months if you don’t bank with ABSA

ABSA also publishes specific requirements for self-employed applicants, including:

  • an ITA34 Tax Certificate
  • six months’ financial statements
  • an official letter from an accountant or bookkeeper confirming the financial health of your accounts

This means being self-employed doesn’t automatically prevent you from applying, although ABSA will need sufficient financial information to assess your income and affordability.

Can You Apply if You Don’t Bank With ABSA?

Yes. You do not need to be an existing ABSA customer to apply for its standard Personal Loan.

Non-ABSA customers may need to provide additional documentation, including recent proof of residence.

Some other ABSA lending products have different requirements. For example, the Instant Loan and Revolving Credit Facility require qualifying applicants to have an ABSA account into which their salary is paid.

How to Apply for an ABSA Personal Loan

ABSA provides several ways to apply for a Personal Loan.

1. Online

You can start a Personal Loan application through ABSA’s website.

2. ABSA Banking App or Digital Banking

Existing ABSA customers can apply through the bank’s digital banking platforms.

3. By Phone

ABSA accepts Personal Loan applications and enquiries by telephone.

4. At a Branch

You can also visit an ABSA branch and apply with assistance from a consultant.

ABSA confirms these application channels on its current Personal Loan page.

During the application, ABSA will assess your personal details, income, credit profile and affordability.

If your application is approved, review the quotation carefully before accepting it. Pay particular attention to:

  • loan amount
  • interest rate
  • repayment period
  • monthly instalment
  • initiation and service fees
  • credit protection premium
  • total amount repayable

You are not required to accept a loan simply because your application has been approved.

How Long Does ABSA Take to Approve and Pay Out a Loan?

The time required to process an ABSA Personal Loan can vary depending on your application, the channel used and whether additional documents or verification are required.

ABSA currently states that customers applying for a Personal Loan through its Banking App could receive immediate payout into their ABSA transactional account if approved.

This should not be interpreted as guaranteed instant approval or immediate funding for every applicant.

ABSA still needs to complete the necessary credit and affordability assessments.

Its Instant Loan works differently. Qualifying ABSA customers can apply digitally or through an ABSA ATM, and ABSA states that the money is made available in the transactional account after the quotation and terms have been accepted.

What Existing ABSA Customers Should Know

Already banking with ABSA can make certain parts of the borrowing process more convenient.

ABSA states that existing customers may already have a provisional Personal Loan offer available, which can be checked online.

Existing customers can also apply through ABSA’s digital banking platforms, and qualifying Banking App applicants may receive approved Personal Loan funds directly into their ABSA transactional account.

Some ABSA credit products are specifically linked to an existing banking relationship.

For example:

  • the Instant Loan requires an ABSA account into which your salary is paid
  • the Revolving Credit Facility also requires an ABSA salary account
  • shorter Personal Loan repayment terms may be available to existing customers

Being an existing customer does not, however, guarantee loan approval or a particular interest rate.

ABSA will still assess your credit profile and affordability.

Advantages of ABSA Personal Loans

ABSA has several features that may make its Personal Loan worth considering, particularly for borrowers looking for larger amounts or longer repayment periods.

High Maximum Loan Amount

ABSA currently offers Personal Loans of up to R350,000, subject to affordability, credit assessment and approval.

This provides considerably more borrowing capacity than many smaller short-term loan products.

Repayment Terms Up to 84 Months

Standard Personal Loan repayment terms range from 12 to 84 months, giving borrowers flexibility when structuring their monthly repayments.

A longer term can reduce the monthly instalment, although it can also increase the total interest paid.

Personalised Interest Rates

ABSA uses personalised pricing rather than charging every borrower the same rate.

Applicants with stronger credit and affordability profiles may qualify for more favourable pricing, although the actual rate isn’t known until ABSA assesses the application.

Several Loan Types

ABSA’s lending range covers very different borrowing needs.

Alongside its standard Personal Loan, ABSA offers:

  • Express Loans for smaller short-term borrowing
  • Instant Loans for qualifying ABSA customers
  • a Revolving Credit Facility
  • Switch and Save for qualifying loan consolidation

This allows borrowers to consider different credit structures rather than treating every borrowing need as a standard long-term personal loan.

Non-ABSA Customers Can Apply

You don’t need to move your everyday banking to ABSA to apply for its standard Personal Loan.

Non-ABSA customers can apply, although additional supporting documents may be required.

Self-Employed Applicants Can Be Considered

ABSA publishes specific documentation requirements for self-employed applicants.

This is useful for borrowers whose income isn’t demonstrated through conventional monthly payslips, although approval remains subject to ABSA’s assessment.

Debt Consolidation Option

ABSA’s Switch and Save product allows qualifying borrowers to move existing personal loans to ABSA, with the bank settling those loans directly.

This can simplify several qualifying loan repayments into a single facility, although borrowers should still compare the total cost before consolidating.

Potential Drawbacks of ABSA Loans

ABSA offers a broad lending range, but that doesn’t mean its products will suit every borrower.

Approval Is Not Guaranteed

ABSA conducts credit and affordability assessments before approving a loan.

Meeting the minimum income or basic eligibility requirements does not guarantee that you’ll be approved for the amount requested.

The Starting APR Isn’t Available to Everyone

ABSA currently advertises Personal Loan rates starting from 13.75% APR, but this is a starting rate rather than the rate every borrower receives.

Your personalised rate may be higher depending on your credit and affordability profile.

Credit Life Insurance Is Mandatory

ABSA states that credit life insurance is compulsory for its Personal Loans.

The insurance provides important protection for specified events, but the premium also contributes to your overall borrowing cost.

Longer Repayment Terms Can Cost More Overall

Repaying a loan over as long as 84 months can reduce the size of your monthly instalment.

However, a longer repayment period can also increase the total amount of interest paid.

Some Products Require an ABSA Salary Account

Although non-ABSA customers can apply for the standard Personal Loan, some other products have stricter banking requirements.

The Instant Loan and Revolving Credit Facility require qualifying applicants to have an ABSA account into which their salary is paid.

Revolving Credit Requires Discipline

Being able to access repaid credit again can be convenient, but repeatedly drawing from a revolving facility can keep you in debt for longer.
Compare Personal Loan Options

Who Should Consider an ABSA Personal Loan?

An ABSA Personal Loan may suit borrowers who:

  • have regular, verifiable income
  • meet ABSA’s credit and affordability requirements
  • need between R3,000 and R350,000
  • want structured monthly repayments
  • want up to 84 months to repay
  • are comfortable with mandatory credit life insurance
  • prefer borrowing from an established bank
  • want the option of consolidating qualifying existing personal loans

Existing ABSA customers may also find the digital application process particularly convenient.

The most important factor, however, is the personalised loan offer you receive. Even if ABSA appears suitable on paper, compare the actual interest rate, fees and total repayment before accepting.

When Should You Compare Other Lenders?

It may be worth comparing other lenders if:

  • ABSA declines your application
  • you’re approved for less than you need
  • the personalised interest rate is higher than expected
  • another lender offers a lower total cost of credit
  • you need a different loan amount or repayment structure
  • you want to compare potential options before committing

Don’t assume that the bank where you already hold an account will automatically provide the cheapest personal loan.

Different lenders use different credit and pricing models, so the rate and amount available to the same borrower can vary.

When comparing offers, focus on:

  • interest rate
  • monthly repayment
  • initiation and service fees
  • credit life insurance
  • repayment term
  • total amount repayable

The cheapest-looking monthly instalment isn’t necessarily the cheapest loan overall.

ABSA vs Other South African Lenders

ABSA is one of several major providers of unsecured personal loans in South Africa.

Rather than asking which lender is universally “best”, compare the actual offer available to you. Loan amounts, interest rates and approval decisions depend on the individual applicant.

ABSA vs Standard Bank

ABSA and Standard Bank are both major South African banks offering unsecured personal loans with repayment periods extending over several years.

ABSA currently offers standard Personal Loans of up to R350,000, while Standard Bank’s Term Loan currently offers up to R300,000.

Both use personalised pricing, meaning the interest rate you’re offered will depend on your individual credit and affordability profile.

If you qualify with both, compare:

  • the approved loan amount
  • personalised interest rate
  • monthly repayment
  • fees
  • credit life insurance
  • repayment period
  • total amount repayable

For a detailed comparison, read our Standard Bank Loans Review.

ABSA vs FNB

ABSA and FNB both offer personal lending as part of a much wider range of banking services.

Existing customers may find applying through their own bank’s digital channels convenient, but convenience shouldn’t be the only factor when choosing a loan.

If you receive offers from both banks, compare the personalised rate, fees, insurance costs, monthly repayment and total cost.

For more information, read our FNB Loans Review.

ABSA vs African Bank

ABSA and African Bank both provide unsecured personal lending, but their wider banking models and product ranges differ.

ABSA offers several unsecured borrowing products ranging from very short-term Instant Loans through to Personal Loans and revolving credit.

Rather than choosing based purely on the maximum advertised amount, compare the actual loan offer available based on your circumstances.

For a detailed comparison, read our African Bank Loans Review.

ABSA vs Sanlam

ABSA and Sanlam operate different financial-services models, although borrowers researching larger personal loans may encounter both when comparing borrowing options.

The most useful comparison is the personalised offer rather than the brand name.

Compare the interest rate, fees, insurance costs, repayment period and total amount repayable before deciding.

For more information, read our Sanlam Loans Review.

ABSA vs Capfin

ABSA and Capfin both provide unsecured personal loans, but their product structures, loan limits and eligibility requirements differ.

ABSA may be more relevant to borrowers seeking larger loan amounts or longer repayment periods, while Capfin offers its own structured personal lending product.

If both are available to you, compare the actual costs and repayment terms rather than assuming either will automatically be cheaper.

For a detailed comparison, read our Capfin Loans Review.

ABSA Customer Service and Reputation

ABSA is an established South African banking group offering both digital and physical customer-service channels.

Customers can manage or access banking services through:

  • the ABSA Banking App
  • Online Banking
  • telephone support
  • ABSA branches
  • ATMs and self-service channels

Digital Banking

Existing customers can manage many aspects of their banking through ABSA’s digital platforms.

Depending on eligibility, customers may also be able to view provisional loan offers, apply for credit and receive approved Personal Loan funds through their existing ABSA banking relationship.

Branch Support

ABSA also maintains a physical branch network, which may appeal to borrowers who prefer having the option of speaking to someone in person.

What About ABSA Customer Reviews?

Customer experiences with any large bank can vary considerably.

Online reviews of ABSA may relate to transactional accounts, cards, home loans, vehicle finance, insurance or other banking services rather than Personal Loans specifically.

For that reason, general online ratings aren’t necessarily a reliable measure of ABSA’s Personal Loan product.

When considering a loan, the more useful information is contained in your personalised quotation — particularly the interest rate, fees, insurance premium, repayment period and total amount repayable.

Does Applying for an ABSA Loan Affect Your Credit Score?

ABSA assesses an applicant’s credit profile and affordability before deciding whether to approve a Personal Loan.

A formal credit application can involve accessing your credit information, and applications for credit may be recorded on your credit profile.

Your existing debts and repayment history can also influence the lending decision.

This is one reason to avoid submitting unnecessary applications to numerous lenders simply to see who might approve you.

Before applying, check the lender’s eligibility requirements and make sure the product is suitable for the amount and repayment period you need.

Responsible Borrowing Tips

Before accepting an ABSA loan — or any other personal loan — consider whether the repayments will remain affordable alongside your normal living expenses.

Ask yourself:

  • Do I need to borrow the full amount offered?
  • Can I comfortably afford the monthly repayment?
  • What is the total amount I’ll repay?
  • How much will fees and insurance add?
  • Could I afford a shorter repayment period?
  • What would happen if my expenses increased?
  • Have I compared the offer with other suitable lenders?

A lender may approve you for more than you originally planned to borrow. That doesn’t mean you need to accept the maximum amount.

Borrowing less and repaying the debt sooner can substantially reduce the overall cost, provided the monthly repayments remain affordable.
ABSA loan comparison checklist

How We Review Loan Providers

FatCat Loans reviews lenders using publicly available information from the lender and relevant regulatory or authoritative sources.

For this ABSA review, we considered factors including:

  • loan amounts and repayment periods
  • published interest-rate information
  • fees and additional borrowing costs
  • eligibility requirements
  • application options
  • credit protection requirements
  • different loan products
  • debt consolidation options
  • transparency of product information

Loan products, rates and eligibility requirements can change. We recommend checking the latest terms in your personalised quotation before accepting any credit agreement.

Expert Verdict: Is an ABSA Personal Loan Worth It?

ABSA offers one of the broader personal lending ranges available from a major South African bank, covering everything from small short-term loans to Personal Loans of up to R350,000.

Its standard Personal Loan offers repayment terms of up to 84 months, with personalised interest rates currently advertised from 13.75% APR. ABSA also offers Express Loans, Instant Loans, revolving credit and a debt consolidation option.

The main consideration is the personalised offer you receive.

Before accepting an ABSA loan, compare:

  • the amount approved
  • your personalised interest rate
  • monthly repayment
  • fees and credit protection costs
  • repayment period
  • total amount repayable

Our Verdict

ABSA may be a strong option for borrowers with regular income who meet its credit and affordability requirements, particularly those looking for larger loan amounts or longer repayment terms.

However, an established banking relationship doesn’t automatically mean ABSA will offer you the lowest-cost loan.

Compare the actual offer with other suitable lenders before deciding.

Compare Personal Loan Options

Frequently Asked Questions About ABSA Loans

How much can I borrow from ABSA?

ABSA currently offers standard Personal Loans from R3,000 to R350,000, subject to affordability, credit assessment and approval.

What is the minimum income for an ABSA Personal Loan?

For a Personal Loan of 12 months or longer, ABSA currently requires regular monthly income of at least R2,000.

What interest rate does ABSA charge on personal loans?

ABSA uses personalised pricing and currently advertises Personal Loan rates starting from 13.75% APR. Your actual rate may be higher.

Can I get an ABSA loan if I don’t bank with ABSA?

Yes. Non-ABSA customers can apply for the standard Personal Loan, although additional supporting documents may be required.

What documents do I need for an ABSA Personal Loan?

You may need a South African ID, three months’ payslips or bank statements and recent proof of residence if you don’t bank with ABSA. Self-employed applicants require additional financial documents.

How long does ABSA take to pay out a personal loan?

ABSA says qualifying Banking App customers could receive approved Personal Loan funds immediately into their ABSA transactional account. Other applications may take longer if additional checks or documents are required.

Does ABSA offer short-term loans?

Yes. ABSA offers Express Loans from R1,500 to R8,000 and Instant Loans from R350 to R8,000 for qualifying applicants.

Can I consolidate debt with ABSA?

Yes. ABSA’s Switch and Save option allows qualifying borrowers to switch and consolidate existing personal loans into an ABSA loan.

What credit score do I need for an ABSA loan?

ABSA does not publish a specific minimum credit score for its standard Personal Loan. Approval depends on your overall credit profile and affordability.

Is credit life insurance compulsory on an ABSA Personal Loan?

Yes. ABSA states that credit life insurance is mandatory for its Personal Loans.

Disclaimer: FatCat Loans is an independent loan comparison service and does not provide loans or make lending decisions. Loan amounts, interest rates, fees, repayment terms and eligibility requirements may change and are subject to the lender’s assessment. Always confirm the latest terms directly with the lender before accepting a credit agreement.
African Bank Loans: What South Africans Should Know Before Applying

Our African Bank Loans review explains current loan amounts, repayment terms, rates, fees, requirements and the application process, plus what to consider before borrowing.

Introduction to African Bank Loans

Last Updated: September 2026

African Bank is a South African bank offering unsecured personal loans with fixed repayments. Qualifying borrowers can currently access personal loans of up to R350,000, with repayment periods extending up to 72 months.

Unlike short-term lenders that typically provide smaller amounts repayable over a few weeks or months, African Bank’s personal loans are designed for larger borrowing needs that can be repaid over several years.

However, the amount you’re approved for, your interest rate and the total cost of borrowing depend on your credit profile, affordability and African Bank’s assessment.

This African Bank Loans review looks at its current loan amounts, repayment terms, interest rates, fees, requirements, application process and credit checks, as well as what to consider before accepting an offer.

Important: FatCat Loans is a loan comparison service and is not affiliated with, endorsed by or owned by African Bank. Loan amounts, rates, fees and eligibility criteria can change. Always confirm the terms of your individual quotation with African Bank before accepting credit.

African Bank Loans at a Glance

Feature African Bank Personal Loan
Loan type Unsecured personal loan
Maximum loan amount Up to R350,000
Repayment term Up to 72 months
Interest rate Personalised based on your credit profile and affordability assessment
Rate structure Fixed for the agreed loan term
Initiation fee May apply according to your credit agreement
Monthly service fee May apply according to your credit agreement
Credit-life insurance May form part of the cost of credit
Credit check Yes
Affordability assessment Yes
Online application Yes
Branch application Yes
Lender African Bank Limited
NCR registration NCRCP7638

Loan amounts, repayment terms, interest rates and fees are subject to African Bank’s lending criteria, affordability assessment and your individual credit profile. Always check your personalised quotation and pre-agreement statement before accepting credit.

African Bank loan amounts, terms and requirements

Understanding African Bank as a Lender

African Bank operates as a registered retail bank in South Africa with a strong focus on personal lending. Unlike short-term or digital-only lenders, African Bank follows a more traditional banking model, combining structured credit assessments with longer repayment periods.

Because of this, African Bank is commonly associated with:

  • Formal affordability assessments
  • Fixed repayment structures
  • Medium- to long-term loan products

African Bank is often compared with other banks and institutional lenders rather than short-term credit providers.

African Bank Limited is also a registered credit provider under NCRCP7638. This means its lending is subject to South Africa’s consumer-credit rules, including requirements around affordability assessments and credit disclosure.

What Types of Loans Does African Bank Offer?

African Bank’s lending options are designed primarily around structured personal credit rather than very small payday-style borrowing.

African Bank Personal Loan

African Bank’s standard personal loan allows qualifying borrowers to access up to R350,000, with repayment terms extending up to 72 months.

The loan is unsecured, meaning you don’t generally provide a house or vehicle as security. Instead, approval and pricing depend on factors such as your income, expenses, existing financial commitments, credit profile and affordability.

Personal loans may be used for purposes such as home improvements, education costs, major purchases or unexpected expenses.

African Bank Consolidation Loan

African Bank also provides debt-consolidation options designed to combine qualifying existing credit commitments into a more manageable repayment structure.

Debt consolidation doesn’t make debt disappear. Existing debts are replaced or settled using new credit, so it’s important to compare the new interest rate, fees, repayment period and total cost with what you’re currently paying.

A lower monthly repayment can improve short-term cash flow, but extending the debt over a longer period can sometimes increase the total amount repaid.

African Bank 12% Loan

You may also come across searches and promotions for an African Bank 12% loan.

Don’t assume that 12% is the standard rate available to every African Bank applicant. Promotional or qualifying rates can have specific eligibility criteria, loan limits and terms.

Always check whether a particular advertised rate applies to you and compare the complete cost shown in your personalised quotation rather than choosing a loan based on the headline interest rate alone.

Common uses for an African Bank personal loan

It’s often useful to estimate your monthly repayments before applying so you understand what may fit your budget.

Who Typically Considers African Bank Loans?

African Bank loans are commonly considered by:

  • Salaried individuals with stable, verifiable income
  • Borrowers seeking structured repayment plans
  • Consumers who prefer traditional banking institutions

Because African Bank offers longer repayment periods than many short-term lenders, it may appeal to borrowers who need a larger amount but want to spread the cost over a structured monthly repayment period.

However, a longer term doesn’t automatically make a loan more affordable overall. Smaller monthly instalments can mean paying interest and fees for longer.

African Bank Loan Requirements and Eligibility

African Bank assesses applications individually. Meeting the basic requirements doesn’t guarantee that your application will be approved or that you’ll qualify for the maximum advertised amount.

The assessment can consider factors including:

  • your age and identity
  • regular and verifiable income
  • existing debts and monthly commitments
  • normal living expenses
  • your credit history
  • your ability to afford the proposed repayment

African Bank performs both credit and affordability assessments before granting credit.

This means the amount one applicant qualifies for can be very different from the amount available to another person, even where they earn similar incomes.

What Documents Do You Need for an African Bank Loan?

The documents required can depend on your circumstances and application channel, but you should be prepared to provide information that allows African Bank to verify your identity, income and affordability.

This may include:

  • South African ID: to verify your identity
  • Proof of income: such as a recent payslip
  • Bank statements: African Bank may require recent statements showing your income
  • Proof of residence: this may be required depending on your circumstances
  • Banking details: for verification, payment and repayment purposes

Having the required documents available can help prevent delays, but providing them doesn’t guarantee approval.

African Bank Interest Rates and Fees

The cost of an African Bank loan isn’t determined by the amount borrowed alone.

Your total cost can include interest, fees and credit-life insurance, so it’s important to review the complete quotation rather than focusing only on the monthly instalment.

Interest rate

African Bank uses personalised, risk-based pricing.

This means your interest rate can depend on factors such as your credit profile, income, affordability, amount borrowed and repayment period.

Once agreed, the applicable rate is generally fixed for the loan term, giving you greater certainty about your scheduled repayments.

Initiation fee

An initiation fee may be charged when the loan is established.

The amount applicable to your loan should be clearly disclosed in your pre-agreement statement and quotation.

Monthly service fee

A monthly service fee can also form part of the cost of maintaining the credit agreement.

Although a monthly fee may appear relatively small, remember that it can be charged repeatedly over a multi-year loan.

Credit-life insurance

Credit-life insurance may also form part of the cost of borrowing.

Depending on the policy and agreement, this type of insurance can provide cover for the outstanding debt in specified circumstances such as death, disability or certain forms of loss of income.

Check the premium, benefits, exclusions and conditions applicable to your particular policy.

Total cost of credit

The most useful figure isn’t necessarily your monthly instalment.

Look at the total amount repayable over the entire loan term.

For example, extending a loan from three years to six years may reduce the monthly instalment, but it also means you’re potentially paying interest, service fees and insurance for much longer.

Always compare:

  • the amount you receive
  • your interest rate
  • monthly repayment
  • fees
  • insurance
  • number of repayments
  • total amount repayable

How Much Could an African Bank Loan Cost?

Because African Bank uses personalised pricing, there isn’t one repayment figure that applies to every borrower.

Two people borrowing the same amount over the same period could potentially receive different interest rates based on their individual credit and affordability assessments.

For this reason, your personalised quotation is more useful than a generic repayment example.

When you receive an offer, compare:

What to check Why it matters
Loan amount How much credit you’re actually receiving
Interest rate The rate charged on your agreement
Loan term How long you’ll be repaying the debt
Monthly instalment What must fit into your monthly budget
Fees Additional charges that increase borrowing costs
Credit-life premium Insurance costs that may form part of your repayment
Total repayment The total rand amount you’ll repay over the agreement

The final figure is particularly important. A loan with a comfortable monthly instalment isn’t necessarily inexpensive if you’re making that payment for several years.

How Does the African Bank Loan Calculator Work?

An online loan calculator can help you understand how changing the loan amount or repayment period could affect your monthly repayment.

However, a calculator result shouldn’t be treated as guaranteed approval or a final quotation.

Your actual African Bank offer can depend on:

  • the amount you apply for
  • your chosen or approved repayment term
  • your personalised interest rate
  • applicable fees
  • credit-life insurance
  • your credit profile
  • your affordability assessment

Use calculator results as a budgeting guide and rely on your final pre-agreement statement and quotation when assessing the actual cost of the loan.

Advantages of African Bank Loans

Large personal loan amounts

Qualifying borrowers can access personal loans of up to R350,000.

Longer repayment periods

Terms extending up to 72 months can allow larger borrowing amounts to be spread over several years.

Fixed repayment structure

A fixed agreed rate and structured instalments can make monthly budgeting more predictable.

Established South African bank

African Bank is an identifiable regulated bank and registered credit provider.

Online access

Borrowers can begin the loan process digitally rather than relying exclusively on a branch.

Potential Drawbacks of African Bank Loans

Your advertised maximum isn’t guaranteed

The fact that African Bank offers personal loans of up to R350,000 doesn’t mean every applicant can borrow that amount.

Rates are personalised

You won’t necessarily know your final borrowing cost until African Bank assesses your application.

Longer terms can increase total costs

Extending repayments can reduce the monthly instalment but may increase the total interest, fees and insurance paid over the life of the loan.

Credit and affordability checks apply

African Bank doesn’t offer guaranteed approval. Your application remains subject to its lending criteria.

Insurance and fees can add to borrowing costs

The interest rate isn’t necessarily the only cost you’ll pay, so check the total amount repayable before accepting an offer.

How to Apply for an African Bank Loan

Step 1: Decide how much you need

Before applying, consider the amount you genuinely need rather than automatically requesting the maximum available.

Step 2: Start your application

African Bank provides digital application options, and assistance may also be available through its other customer-service channels.

Step 3: Provide your personal and financial information

You’ll need to provide information that allows African Bank to verify your identity, income and financial circumstances.

Step 4: Complete the credit and affordability assessment

African Bank assesses your credit profile and whether the proposed repayment is affordable based on your financial circumstances.

Step 5: Receive your offer

If approved, you’ll receive the terms available to you. The amount and rate may differ from headline advertising because pricing is personalised.

Step 6: Review the quotation

Before accepting, check your:

  • loan amount
  • interest rate
  • repayment period
  • monthly instalment
  • initiation fee
  • monthly service fee
  • credit-life insurance
  • total amount repayable

Step 7: Accept the agreement

Only accept the loan once you understand the repayment obligation and are confident it fits your budget.

Step 8: Receive the funds

Once the agreement has been accepted and African Bank’s remaining requirements have been completed, approved funds can be paid to the relevant bank account.

Does African Bank Perform a Credit Check?

Yes. African Bank assesses your creditworthiness as part of its lending process.

A credit assessment helps the bank understand factors such as your existing debts, repayment history and overall credit profile.

African Bank also needs to assess affordability.

This means claims about “guaranteed African Bank loans” or “African Bank loans with no credit check” should be treated cautiously because they don’t accurately describe the normal lending process.

If you’re unsure how lender enquiries work, read our guide to soft and hard credit checks in South Africa.

Can You Get an African Bank Loan With Bad Credit?

Having a weaker credit profile doesn’t allow us to predict whether African Bank will approve or decline your application.

The bank considers your application according to its own lending criteria and affordability requirements.

Factors that may influence the outcome include:

  • your repayment history
  • existing debts
  • recent credit applications
  • income
  • expenses
  • affordability

There isn’t one universal credit-score number that guarantees African Bank approval.

If you’re struggling to qualify for mainstream personal credit, you can learn more about loan options for bad credit in South Africa.

Be cautious about repeatedly submitting applications to multiple lenders after being declined. Multiple credit applications over a short period can result in additional enquiries appearing on your credit profile, while doing nothing to address the affordability or credit issues that caused the original decline.

How Long Does an African Bank Loan Take to Approve?

African Bank doesn’t guarantee that every application will be approved or paid out within the same timeframe.

Processing can depend on factors such as:

  • whether your application is complete
  • income and document verification
  • credit assessment
  • affordability checks
  • whether additional information is required
  • acceptance of the final agreement

A quick online application shouldn’t be confused with guaranteed instant approval.

If you need money for a time-sensitive expense, confirm the expected processing and payout timeframe directly with African Bank rather than assuming the funds will arrive on a particular day.

Who Might an African Bank Loan Suit?

An African Bank personal loan may be worth considering if you:

  • have stable and verifiable income
  • need a larger personal loan rather than very short-term credit
  • want structured monthly repayments
  • want to spread a significant expense over a longer period
  • can comfortably afford the repayment
  • understand the complete cost of the agreement

It may be less suitable if:

  • you’re already struggling to meet existing debt repayments
  • you need guaranteed approval
  • you want very small, very short-term borrowing
  • the monthly instalment would leave little money for essential expenses
  • you’d need to borrow again simply to make the repayments

The important question isn’t simply whether African Bank is willing to lend you the money.

It’s whether the repayment comfortably fits your budget for the entire loan term.

African Bank vs Other Personal Loan Providers

African Bank isn’t the only provider offering larger personal loans in South Africa.

Before choosing a lender, compare the amount available, repayment period, personalised interest rate, fees, insurance and total amount repayable.

African Bank vs ABSA

Both African Bank and ABSA offer personal loans to South African borrowers, with approval and pricing based on individual circumstances.

Rather than choosing solely on the maximum advertised loan amount, compare the actual offer available to you from each provider — particularly the interest rate, repayment term and total cost.

Read our full ABSA Loans review for current product information.

African Bank vs Sanlam

Sanlam is another established financial-services provider offering personal credit options.

The right choice depends on the amount you need, the rate you’re offered, repayment period, fees and whether the resulting instalment comfortably fits your budget.

See our Sanlam Loans review for a closer look at its offering.

African Bank vs Short-Term Lenders

African Bank’s mainstream personal loan serves a different purpose from small short-term loans.

A longer personal loan can spread the cost over several years, while short-term credit generally needs to be repaid much sooner.

Neither is automatically cheaper.

Compare the total amount repayable, not simply the repayment period or advertised interest rate.

Checklist before accepting an African Bank loan

Is African Bank Legit?

Yes. African Bank Limited is an established South African bank and registered credit provider.

African Bank identifies itself under registration number 2014/176899/06 and credit-provider registration NCRCP7638.

Being a registered provider doesn’t mean every loan it offers will be suitable for every borrower. You should still assess the interest rate, fees, insurance, repayment term and total cost before accepting credit.

Consumers can also use the National Credit Regulator as an independent source of information about regulated credit in South Africa.

Compare African Bank With Other Loan Options

African Bank is one borrowing option, but applying directly to a single lender isn’t the only way to explore personal credit.

FatCat Loans is a comparison service rather than a lender. You can submit one online request to see whether loan options may be available from participating providers.

We’re not affiliated with African Bank and can’t guarantee that African Bank will be one of the options presented.

Using a comparison service can help you explore available options before deciding what type of loan may suit your circumstances.

Before accepting any offer, compare:

  • amount borrowed
  • interest rate
  • fees
  • insurance
  • repayment period
  • monthly repayment
  • total amount repayable

Compare African Bank With Other Loan Options

African Bank Loan Scams and Safety Tips

Well-known lender names can be used by scammers to make fraudulent loan offers appear legitimate.

If someone contacts you claiming to represent African Bank:

  • verify the contact details through African Bank’s official website
  • be cautious of unsolicited WhatsApp, SMS or social-media loan offers
  • never share your banking PIN, password or one-time PIN with someone offering a loan
  • don’t assume an offer is genuine simply because it uses African Bank’s name or logo
  • be suspicious of anyone promising guaranteed approval regardless of your finances
  • confirm unexpected payment requests directly with African Bank before sending money

If you’re unsure whether a communication is genuine, contact African Bank using contact information obtained independently from its official website rather than the details contained in the suspicious message.

Frequently Asked Questions About African Bank Loans

How much can I borrow from African Bank?

African Bank currently advertises personal loans of up to R350,000. The amount available to you depends on your credit profile, income, affordability and African Bank’s assessment.

What interest rate does African Bank charge?

African Bank uses personalised pricing, so there isn’t one standard interest rate that applies to every borrower. Your actual rate should be shown in your personalised quotation before you accept the loan.

What do I need to qualify for an African Bank loan?

You’ll need to meet African Bank’s eligibility, credit and affordability requirements. The bank may require identification, proof of income, bank statements and other supporting information depending on your application.

How long does African Bank take to approve a loan?

Processing times can vary. Approval depends on factors such as completing the application, providing the required documents, credit and affordability assessments and any additional verification African Bank requires.

Does African Bank check your credit?

Yes. African Bank assesses creditworthiness and affordability when considering loan applications. Approval is not guaranteed.

Is African Bank registered with the NCR?

Yes. African Bank Limited is identified as a registered credit provider under NCRCP7638.

Final Verdict: Is an African Bank Loan Worth Considering?

African Bank is an established South African bank offering personal loans of up to R350,000 with repayment periods extending up to 72 months for qualifying borrowers.

That makes it potentially worth considering if you need a larger personal loan and want to repay it through structured monthly instalments rather than using very short-term credit.

However, the maximum advertised amount isn’t guaranteed, and African Bank uses personalised pricing. The rate, amount and terms you’re offered will depend on your individual credit profile and affordability assessment.

Longer repayment periods also need careful consideration.

Spreading a loan over several years can make the monthly instalment easier to manage, but it can also mean paying interest, service fees and insurance for much longer.

Before accepting an African Bank loan, compare the amount you’ll receive, monthly repayment, interest rate, fees, insurance, repayment period and total amount repayable.

Most importantly, make sure the repayment comfortably fits your budget without compromising essential expenses or forcing you to borrow again.

Personal Loan Explained: A Complete Guide for South Africans (2026)

This complete 2026 guide explains how personal loans work in South Africa, including eligibility, interest rates, fees, repayment terms, and credit score impact—helping borrowers make informed, responsible decisions.

Introduction to Personal Loan Explained

Updated January 2026

If you’re considering borrowing money in 2026, understanding how a personal loan works is an essential first step. This personal loan explained guide breaks down the entire process — from the application and approval to interest rates, fees, loan terms, and responsible borrowing practices under the National Credit Act (NCA).

Unlike informal loans or expensive short-term credit, a personal loan offers structured monthly repayments, transparent pricing, and strong consumer protection. But because every lender evaluates applicants differently — and because interest rates can vary widely — borrowers who understand how personal loans really work make better, more confident decisions.

This guide goes deep into the mechanics of personal loans in South Africa and gives you the expert-level knowledge you need to use credit responsibly and effectively.

Find a Personal Loan That Fits Your Needs

This guide explains how personal loans work in South Africa. If you’re ready to compare offers and apply securely, start here:

Personal Loan Explained: What It Is and How It Works

A personal loan is a fixed-term, unsecured credit agreement that allows you to borrow a lump sum and repay it in equal monthly instalments over a period of 6 to 72 months.

“Unsecured” means:

You do not need to provide any assets (like a car or house) as security.

Approval is based on:

  • Your income level
  • Your affordability
  • Your credit score
  • Your existing debt
  • Your repayment history
  • Your banking behaviour
  • Stability of employment

Because the loan is unsecured, lenders rely heavily on your creditworthiness rather than collateral.

Next step: If you want to compare lenders after you understand the basics, use our hub page:  Compare Loans South Africa.

Best option if you want to apply (recommended)

If your goal is to compare multiple personal loan offers and apply securely, use our main service page here:

Apply for Personal Loans South Africa

Or browse all loan types in one place: Compare Loans South Africa

The Personal Loan Life Cycle

Understanding the stages of a personal loan helps you know what to expect.

Stage What Happens Why It Matters
1. Application You submit your personal details, income, and banking documents. Lenders gather information to assess your risk level.
2. Affordability Assessment Lender checks income vs expenses. Required by the NCA to avoid reckless lending.
3. Credit Check Your credit report and score are reviewed. Influences approval and interest rate.
4. Loan Offer You receive the loan amount, interest rate, term, and fees. Ensures full transparency before signing.
5. Pay-out Money is paid into your bank account. Timing varies from minutes to 48 hours.
6. Repayment Fixed monthly instalments until the loan is settled. Predictable budgeting.

Personal loan checklist (before you apply)

Before you accept any personal loan offer, make sure you understand the full cost and repayment commitment:

  • Total repayment amount: Don’t only compare monthly instalments — confirm the total amount you’ll repay over the full term.
  • Fees included: Check whether initiation fees, monthly service fees, and credit life insurance are included in the estimate.
  • Affordability: Only borrow what comfortably fits your budget after essentials like rent, groceries, transport, and debit orders.
  • Term choice: Longer terms reduce monthly instalments, but often increase the total interest you pay.
  • Early settlement: Ask whether you can settle early and whether any admin fees apply.

Loan Amounts: How Much You Can Borrow

Personal loans in South Africa can range from:

  • R1,000 to R10,000 for small, short-term needs
  • R10,000 to R50,000 for moderate financial goals
  • R50,000 to R150,000 for home improvements, education, or large expenses
  • R150,000 to R300,000+ for high-income earners with strong credit histories

The final approved amount depends on:

  • Income
  • Affordability
  • Credit score
  • Banking behaviour
  • Existing debt

If you’re unsure whether your financial profile fits typical lending requirements, you can review examples on the online loans category or the bad credit loans section for alternative options.

Understanding Personal Loan Terms (6–72 Months)

Your loan term influences both affordability and total cost.

Short Terms (6–24 months)

✔ Higher monthly instalments
✔ Lower total interest paid
✔ Faster loan completion
✔ Better for small or medium borrowing

Longer Terms (24–72 months)

✔ Lower monthly instalments
✔ Higher total interest paid
✔ Easier affordability
✔ Better for large loan amounts

Example comparison:

Assume a R20,000 loan at 21% interest:

Term Monthly Instalment Total Repayment Best For
12 months ± R1,860 ± R22,320 You want to pay less interest
36 months ± R844 ± R30,384 Balanced affordability
60 months ± R600 ± R36,000 Lower monthly instalments

You can run your own estimates anytime using our loan repayment calculator.

Personal Loan Interest Rates Explained

Interest on personal loans is risk-based, meaning lenders charge more or less interest depending on your risk profile.

Factors that help lower interest:

  • Strong credit score
  • Stable employment
  • Low debt-to-income ratio
  • Good banking behaviour
  • Clean repayment history

Factors that increase interest:

  • Poor credit score
  • Missed or late payments
  • High levels of existing debt
  • Salary inconsistencies
  • Bank account reversals or unpaid debit orders

Typical interest ranges:

Borrower Profile Interest Range
Excellent credit 13%–19%
Average credit 20%–28%
Bad credit 28%–33%+

All interest rates are capped and regulated by the National Credit Act.

If you’re rebuilding your credit, you can explore the bad credit loans section for lenders who consider lower scores.

Personal Loan Fees Explained

All personal loans in SA include:

1. Initiation Fee

A once-off fee added to your loan amount.
The cost depends on loan size but is capped under the NCA.

2. Monthly Service Fee

A flat fee up to R69 per month.

3. Interest Rate

Based on your risk profile.

4. Credit Life Insurance

Protects repayments in the event of death, disability, or retrenchment.
Optional for some lenders, required by others.

These fees together determine your monthly instalment and total repayment.

What You Can Use a Personal Loan For

Personal loans are extremely flexible. Popular uses include:

  • Medical emergencies
  • Car repairs or maintenance
  • Home renovation
  • School or university fees
  • Appliances and furniture
  • Travel
  • Moving costs
  • Debt consolidation
  • Side-business funding

If your need is urgent, you can explore options through our emergency loans section or quick loan options, which can pay out faster.

Types of Personal Loans in South Africa

Below are the most common personal loan categories and how they differ:

General Personal Loans

Best for everyday borrowing.

Bad Credit Loans

Designed for applicants with impaired credit scores.

Instant Loans

Focus on fast approval and pay-out.

Quick Loans

Suitable for small emergencies.

Short-Term Loans

Typically repaid in 1–6 months.

Online Loans

Fully digital application process.

Instalment Loans

Longer-term repayments with structured instalments.

Consolidation Loans

Used to combine multiple debts into one structured loan.

How Lenders Decide Whether to Approve You

Understanding how lenders think helps you increase your chances of approval.

Affordability

This is the biggest factor. Lenders must verify that you can repay the loan.

Credit Score

Shows how reliable you are at repaying debt.

Employment Stability

Full-time employment or consistent income increases approval odds.

Debt-to-Income Ratio

If too much of your income already goes to debt, you may be declined.

Banking Behaviour

Lenders carefully check bank statements for:

  • unpaid debit orders
  • repeated overdraft usage
  • reversals
  • large unexplainable spending
  • gambling transactions

Example: Full Personal Loan Cost Breakdown

Let’s analyse a typical loan:

Loan amount: R30,000
Term: 36 months
Interest rate: 22%
Service fee: R69
Initiation fee: R1,150

Estimated monthly instalment: ± R1,200
Total repayment: ± R43,200

Use the loan repayment calculator for your personalised calculation.

When a Personal Loan Makes Sense

A personal loan is a strong choice when:

✔ You need predictable monthly instalments
✔ You have stable income
✔ You’re consolidating high-interest debt
✔ You want structured repayments
✔ You need to finance essential expenses or emergencies

When a Personal Loan Is NOT a Good Idea

Avoid personal loans if:

❌ You’re already struggling with debt
❌ You’re borrowing for luxury items
❌ You lack income stability
❌ You can save instead of borrowing
❌ You plan to apply at many lenders in a short period

If you’re unsure, you can review alternatives through the debt consolidation section or seek advice from a financial counsellor.

How to Improve Your Chances of Approval

Experts recommend:

  • Paying all accounts on time
  • Checking your credit score regularly
  • Reducing unnecessary monthly expenses
  • Avoiding new debt before applying
  • Not applying at multiple lenders simultaneously
  • Keeping your bank account free of reversals

These changes can significantly improve your affordability.

Common Mistakes to Avoid With Personal Loans

Avoid these costly errors:

❌ Choosing the longest term only because instalments are lower
❌ Borrowing more than you actually need
❌ Ignoring fees and insurance costs
❌ Using informal lenders
❌ Missing repayments
❌ Taking a loan to pay off another loan (unless structured as consolidation)

Personal Loan Explained – Frequently Asked Questions

What is a personal loan?

An unsecured loan repaid in fixed monthly instalments.

How fast can I get a personal loan?

Some lenders approve applications on the same day.

Can I get a personal loan with bad credit?

Yes — explore options in the bad credit loans section.

How do I know what I can afford?

Use the loan repayment calculator on our website.

Are personal loan fees regulated?

Yes, under the National Credit Act.

Is credit life insurance compulsory?

Some lenders require it; others offer it as optional protection.

Can a personal loan improve my credit score?

Yes — consistent on-time repayments can improve your rating.

Compare and apply safely

Personal loans can be a useful financial tool when used responsibly, but approval depends on affordability checks and lender criteria.

If you want to compare personal loan options and apply in a safe, transparent way, start here:  Personal Loans South Africa

Or compare all loan types: Compare Loans South Africa

Conclusion

Having the fundamentals of a personal loan explained empowers you to choose the right lender, term, and amount with confidence. With clear knowledge of how interest, fees, and affordability assessments work, you can avoid unnecessary costs and make financially sound decisions.
Disclosure:  This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

Reviewed by the FatCat Loans Editorial Team. Read our publishing standards here: Editorial Policy.

Unsecured Personal Loans South Africa: No Collateral (2026)

This 2026 guide explains unsecured personal loans in South Africa, covering how they work, approval times, interest rates, eligibility requirements, and why no collateral is needed—making them a fast and flexible borrowing option.

Why Unsecured Personal Loans Are in High Demand in South Africa

More South Africans than ever are searching for unsecured personal loans South Africa — flexible loans that don’t require collateral, offer quick approval, and help individuals manage everything from emergencies to long-term financial goals.

As living costs rise and access to traditional lending becomes more selective, unsecured loans offer a simple, accessible way to borrow without putting your car, home, or valuable assets at risk. Whether you’re covering medical expenses, home repairs, education costs, or consolidating smaller debts, these loans provide financial breathing room when you need it most.

In this comprehensive guide, we unpack how unsecured personal loans South Africa work, who qualifies, how lenders assess applications, and how FatCat Loans connects you with reliable, NCR-approved lenders in minutes.

For background on other loan types, you can also explore

👉 Personal Loans South Africa
👉 Instant Loans
👉 Bad Credit Loans
👉 Instalment Loans
👉 Consolidation Loans

What Are Unsecured Personal Loans South Africa?

The term unsecured personal loans South Africa refers to loans that do not require collateral. Unlike secured loans — where you must provide an asset such as a car or property — unsecured loans rely on your income, credit profile, and affordability.

An unsecured personal loan is a loan you qualify for without using an asset as security (like a car or property). Instead, lenders approve you based on your income, affordability, and credit profile. Because there’s no collateral, the loan is higher risk for the lender — which is why interest rates can be higher than secured loans.

In simple terms, unsecured personal loans in South Africa usually offer:

  • No collateral required

  • Flexible loan amounts

  • Repayment terms from 6 to 72 months

  • Approval based on affordability rules under the National Credit Act (NCA)

  • Faster online applications with most lenders

These loans are ideal for South Africans who want financing without risking their assets or going through complex bank procedures.

To understand how lenders are regulated, visit the National Credit Regulator (NCR).

How Unsecured Personal Loans South Africa Work

Unsecured loans follow a straightforward process. Here’s a complete breakdown of how they work from start to finish:

Step 1 — Apply Online

You complete a quick digital application through a platform like FatCat Loans, which connects you with multiple NCR-registered lenders at once.

Step 2 — Lender Assessment

Lenders review:

  • Your credit history

  • Income stability

  • Bank account activity

  • Debt-to-income ratio

This step determines whether you meet affordability requirements.

Step 3 — Approval Decision

Once your application is processed, lenders provide:

  • The approved loan amount

  • Interest rate

  • Repayment term

  • Total cost of credit

Decisions are often instant.

Step 4 — Funds Disbursed

After signing your loan proposal and agreement, the lender pays the funds into your bank account — usually within 24 hours.

Step 5 — Repayment

You repay the loan through fixed monthly instalments over your chosen term.

If you want to compare different loan structures, explore How Debt Consolidation Loans Work in South Africa (2025 Guide)

What Do Unsecured Personal Loans Cost in South Africa? (Interest + Fees Explained)

The total cost of an unsecured personal loan depends on more than just the interest rate. South African lenders may charge:

  • interest (based on your risk profile and the loan type)

  • initiation fees (once-off setup fee)

  • monthly service fees

  • insurance (optional or included in some agreements)

Even when two loans offer the same amount, the total repayment can differ dramatically depending on the repayment term, interest rate, and added fees.

Tip: Always compare the total repayment amount, not just the monthly instalment.

Real Example: How Interest Rate Changes Your Repayment

Let’s say you borrow R30,000 over 24 months:

  • At a lower rate, your repayment may feel manageable

  • At a higher rate, your repayment increases — and the loan may cost significantly more overall

That’s why borrowers with strong affordability and a cleaner credit profile often qualify for better pricing, while borrowers with higher risk may receive prime + pricing.

If you want to understand how the base pricing benchmark affects your interest rate, read our guide to the South Africa prime rate.

Why Choose Unsecured Personal Loans South Africa

Unsecured personal loans South Africa appeal to millions of borrowers because of their flexibility, accessibility, and simplicity.

Here’s why they’re so popular:

1. No Collateral Required

You don’t risk losing your home, vehicle, or assets because the loan is unsecured.

2. Fast Digital Approvals

Most online lenders offer instant feedback and same-day pay-outs.

3. Flexible Loan Amounts

Borrow between R1,000 and R350,000 depending on your income and affordability.

4. Predictable Monthly Payments

Fixed instalments make budgeting easier.

5. Lower Entry Barriers

If banks have turned you away, unsecured lenders may still approve you based on your affordability.

6. Multi-Purpose Use

Use funds for anything, including:

  • Medical expenses

  • Home improvements

  • School fees

  • Car repairs

  • Moving costs

  • Debt consolidation

Learn more about improving your credit profile in our Debt Consolidation Meaning South Africa guide.

Who Qualifies for Unsecured Personal Loans South Africa?

Each lender has unique criteria, but most require:

  • South African ID (age 18–65)

  • Steady monthly income — salary, pension, or grant

  • Active bank account for 3+ months

  • Proof of residence

  • Recent payslips or bank statements

If your credit score is lower than average, you may still qualify through lenders offering Bad Credit Loans South Africa

Unsecured Personal Loan Application Checklist (Before You Apply)

Before submitting your application, make sure you have:

✅ South African ID number
✅ Recent bank statements (last 3 months)
✅ Proof of income (payslip or verified deposits)
✅ Proof of residence
✅ A realistic repayment plan based on your monthly budget

If your finances are tight, it’s safer to estimate what you can realistically afford to repay before applying — this reduces rejection risk and helps you avoid taking on unaffordable debt.

What Affects Approval Decisions?

Understanding lender criteria helps you strengthen your application. Here’s what lenders look at:

1. Income Stability

Regular monthly deposits, consistent employment, and predictable earnings increase your chances of approval.

2. Affordability Score

Lenders compare your income with your existing expenses and debts to ensure you aren’t overcommitted.

3. Credit History

While unsecured loans don’t require perfect credit, a clean repayment record may unlock:

  • Lower interest rates

  • Higher loan amounts

  • Longer repayment terms

4. Debt-to-Income Ratio (DTI)

A lower DTI ratio shows lenders you can manage repayment.

5. Bank Account Behaviour

Lenders check for:

  • Returned debit orders

  • High overdraft usage

  • Irregular deposits

  • High discretionary spending

If you need help improving approval chances, read our Debt Consolidation Loan Approval South Africa (2025 Guide)

Benefits of Unsecured Personal Loans South Africa

1️⃣ Flexible Use of Funds

Unlike student loans or car finance, unsecured loans can be used for any personal need.

2️⃣ Fixed Repayment Plan

The amount remains the same throughout the loan term, offering predictability.

3️⃣ No Asset Risk

You are not required to hand over security or collateral.

4️⃣ Faster Processing Times

Most lenders operate digitally — reducing approval times dramatically.

5️⃣ Helps Build Credit

Timely repayment strengthens your credit profile.

To check current interest rate movements, visit the South African Reserve Bank (SARB).

Unsecured Personal Loans South Africa vs Secured Loans

Here’s how unsecured loans compare to secured credit:

Feature Unsecured Personal Loans Secured Loans
Collateral Required ❌ No ✅ Yes
Approval Speed Fast Slower
Loan Amount Moderate Higher potential
Risk to Borrower Low Higher (asset risk)
Eligibility More flexible More restrictive

Unsecured loans typically offer flexibility and speed, while secured loans offer higher amounts and lower interest — but with more risk.

How Much Can You Borrow with Unsecured Personal Loans South Africa?

Loan ranges depend on the lender but typically fall between:

  • R1,000 – R350,000

  • 6 to 72-month repayment terms

If you want to explore larger financing options, see Personal Loans South Africa

Unsecured Personal Loans for Bad Credit

Even if your credit record isn’t perfect, some lenders specialise in affordability-based approvals. These loans may come with:

  • Higher interest rates

  • Lower initial amounts

  • Shorter repayment terms

Explore these options on our Bad Credit Loans South Africa

Using an Unsecured Loan for Debt Consolidation

One of the most popular uses for unsecured personal loans South Africa is debt consolidation.

By merging multiple smaller debts — like store accounts or microloans — into one instalment, you gain:

  • Lower monthly repayments

  • One payment instead of many

  • A clearer repayment timeline

  • Reduced financial pressure

To better understand how consolidation works, explore:
👉 Debt Consolidation Loans South Africa
👉 The Meaning of Debt Consolidation in South Africa

When an Unsecured Personal Loan Is NOT a Good Idea

Unsecured personal loans can help in the right situation — but they’re not always the best solution.

Avoid taking an unsecured loan if:

  • you plan to use it for luxury purchases or lifestyle spending

  • you’re borrowing to repay another loan (debt cycling risk)

  • your budget is already tight and you’re relying on “future income”

  • you can’t comfortably afford the instalment even with reduced expenses

If your main issue is multiple repayments, it may be safer to explore a structured consolidation option instead of taking another loan.

Responsible Borrowing Tips

To get the most benefit from unsecured loans:

📌 Borrow only what you need

Overborrowing increases financial pressure.

📌 Compare lenders before applying

Interest rates vary widely — FatCat Loans helps you compare instantly.

📌 Repay on time

This protects your credit profile and future borrowing options.

📌 Avoid taking multiple loans at once

This can damage affordability and reduce credit health.

📌 Use funds wisely

Emergency expenses, education, home repairs, and consolidation are all smart uses.

Examples of Unsecured Personal Loan Providers in South Africa (2026)

Lender Loan Amount Interest Rate Best For
African Bank Up to R350,000 From 15% Affordable, flexible terms
ABSA Bank R3,000 – R250,000 From 14% Trusted, established lender
Direct Access R1,000 – R20,000 Custom Short-term, smaller loans
Wonga R500 – R8,000 3% monthly Quick emergency funding

Loan limits and costs vary by provider and are subject to affordability and credit checks.

Compare these lenders instantly on FatCat Loans for the best rates and terms.

When Are Unsecured Personal Loans South Africa a Good Choice?

These loans are ideal for:

  • Emergency medical or household expenses

  • Repairing or maintaining your vehicle

  • Funding school or university needs

  • Managing wedding or event costs

  • Covering relocation expenses

  • Consolidating debt into one structured payment

Avoid using unsecured loans for:

  • Luxury items

  • Non-essential purchases

  • High-risk investments

    Apply for unsecured personal loans South Africa with FatCat Loans.

Frequently Asked Questions (FAQs) About Unsecured Personal Loans South Africa

What are unsecured personal loans South Africa?

Unsecured personal loans South Africa are loans that don’t require you to provide any collateral, such as a car or property. Approval is based on your income, credit profile, and overall affordability, making these loans ideal for emergencies, education, home repairs, or debt consolidation.

Who qualifies for unsecured personal loans South Africa?

Most lenders require you to:

  • Be a South African citizen aged 18–65

  • Earn a steady monthly income

  • Have an active bank account for at least 3 months

  • Provide payslips or bank statements

  • Show affordability under NCA regulations

Even if you have a lower credit score, many lenders may still approve your application based on affordability.

How quickly can I get the funds?

Approval often happens instantly, and payout typically occurs within 24 hours after signing your loan agreement. Through platforms like FatCat Loans, you can compare lenders and apply online in minutes.

Can I get unsecured personal loans South Africa with bad credit?

Yes — some lenders specialise in assisting borrowers with less-than-perfect credit. They assess your income and ability to repay rather than focusing only on your credit score. Visit the Bad Credit Loans page on FatCat Loans to explore these options.

What can I use unsecured personal loans South Africa for?

These loans are flexible and can be used for:

  • Medical bills

  • Car or home repairs

  • School or university fees

  • Moving costs

  • Emergency expenses

  • Debt consolidation

There are no restrictions on how you spend the funds.

Are unsecured personal loans South Africa safe?

Yes. As long as you borrow from NCR-accredited lenders, unsecured personal loans are regulated under the National Credit Act. FatCat Loans only works with trusted, compliant South African lenders to ensure safe, transparent borrowing.

Do I need a good credit score to get an unsecured personal loan?

Not always. Some lenders focus more on affordability and income stability than score alone, but a stronger score usually improves your interest rate and loan amount.

Can I get an unsecured personal loan without a payslip?

Some lenders may accept bank statements showing consistent deposits instead of payslips, especially for self-employed or informal income earners. Approval depends on affordability and risk assessment.

Is an unsecured loan better than using a credit card?

It depends. Unsecured loans usually offer fixed repayments and structured terms, while credit cards can become expensive if you only pay the minimum balance monthly.

How many unsecured loan applications should I submit?

Avoid applying to multiple lenders individually. Too many credit checks can affect your profile. A comparison platform helps you review options with less risk.

What happens if I settle my unsecured loan early?

Some lenders may reduce interest costs when you settle early, but terms vary. Always check the settlement calculation and whether fees apply.

Conclusion: Flexible, Fast, and Accessible Borrowing for South Africans

Unsecured personal loans South Africa are one of the most flexible lending solutions available today. With no collateral required, quick online applications, competitive interest rates, and manageable repayment terms, they provide the financial support South Africans need to navigate life confidently.

Whether you’re facing an urgent expense or planning a larger personal goal, FatCat Loans helps you compare trusted, NCR-registered lenders in minutes — giving you a safe, transparent path to approval.

🎯 Get started today!
Apply for unsecured personal loans South Africa through FatCat Loans — fast, secure, and 100% online.

Disclosure:  This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.