10 Things to Sell to Make Money Online (South African Guide for 2026)

Not sure what to sell to make money online? Here are 10 proven things to sell in South Africa, plus tips on pricing, platforms, SEO, and avoiding Facebook Marketplace scams.

Introduction to 10 Things to Sell to Make Money Online

Updated January 2026

If you’ve been asking what to sell to make money, you’re not alone. More South Africans are turning to online selling to earn extra income, build a side hustle, or test a business idea without needing a big startup budget.

The good news is that you don’t need a warehouse, staff, or expensive equipment to start. You do need a product people actually want, a safe way to sell it, and listings that build trust.

In this guide, you’ll learn:

  • the best things to sell online (with South Africa-friendly ideas)

  • where to sell safely and how to avoid scams

  • how to price for profit (not just to “get a sale”)

  • simple SEO tips to help your products get found

Trust note: This article is for educational purposes only and does not guarantee income. Always follow local rules (especially for food or skincare products), and only invest what you can afford to lose when testing a new side hustle.

Quick answer: what to sell to make money

The best things to sell to make money online include digital printables, second-hand clothing, handcrafted jewellery, books, customised tech accessories, and gift boxes. If you’re looking for what to sell to make money in South Africa, start with items that are easy to deliver locally and protect yourself from scams on platforms like Facebook Marketplace and Gumtree.

Key highlights

  • Digital products can be high profit because you create them once and sell repeatedly

  • Second-hand and handmade items are great low-cost ways to start

  • Clear photos, honest descriptions, and reliable delivery build trust and repeat buyers

  • Pricing properly is the difference between a hobby and a profitable business

  • South Africa has many scammers online—seller safety should be part of your strategy

What can I sell? Start with these 10 proven ideas

There are endless options for what to sell, but these 10 items are consistently popular and practical for beginners.
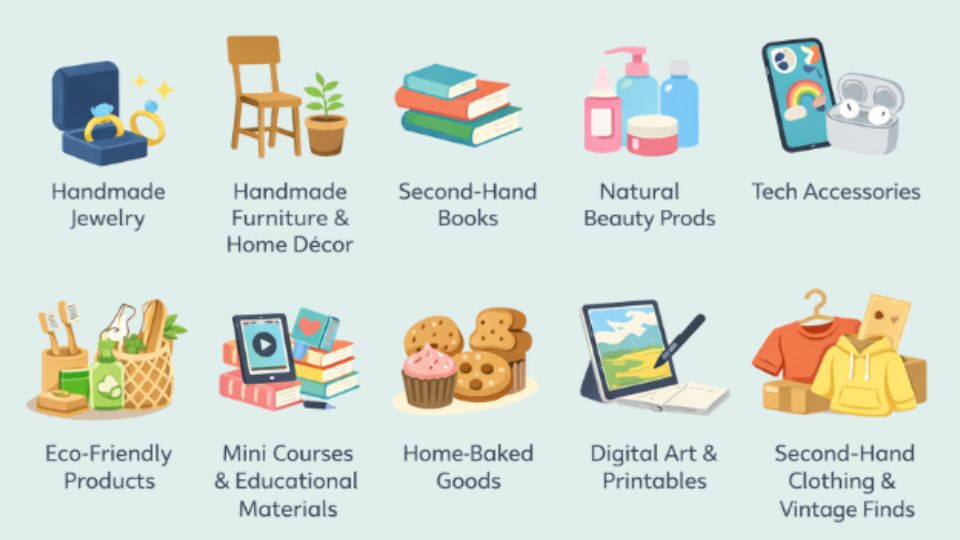
Flat vector illustration of the different things you can sell to make money in South Africa.

1) Handcrafted jewellery

Handmade jewellery sells well because it feels personal and unique—especially for gifts.

What to sell:

  • beaded bracelets

  • name necklaces

  • minimalist rings

  • statement earrings

Why it works: low materials cost, easy shipping, strong demand.

2) Second-hand clothing and vintage finds

If you’re wondering what can I sell to make money in South Africa, second-hand clothing is one of the fastest ways to start—because you can begin with what you already own.

Things to sell:

  • branded jackets and hoodies

  • sneakers and denim

  • handbags and accessories

  • kids clothing bundles

Pro tip: include measurements and a clear condition note to reduce returns and complaints.

3) Digital art and printables

Digital products are one of the best answers to what can I sell to make money because they don’t require stock, packaging, or couriers.

Popular digital products:

  • planners and trackers

  • wall art prints

  • invitation templates

  • business templates (invoices, price lists, checklists)

  • kids learning sheets

Why it works: you make it once and sell it many times.

If you ever decide to build a long-term online store, Shopify’s guides are a good place to start—see Shopify’s ecommerce tips for beginners.

4) Eco-friendly products

Eco-friendly products sell well because buyers want sustainable options that still feel affordable and practical.

Things to sell:

  • reusable shopping bags

  • refill containers

  • eco cleaning products

  • bamboo alternatives

Trust tip: avoid exaggerating sustainability claims—only say what you can prove.

5) Home-baked goods (local pre-orders)

Baked goods can sell well locally, especially for events and celebrations.

Ideas:

  • cupcakes and cookies

  • brownies

  • celebration cakes (pre-order only)

  • holiday treat boxes

Safety note: food-related products require extra care. Be transparent about ingredients and allergens, and follow safe handling practices. For general health guidance, you can refer to the NICD’s public health information.

6) Educational materials and mini courses

Education support is in demand, which makes this a strong category for things to sell to make money online.

What to sell:

  • study notes and summaries

  • printable worksheets

  • exam prep packs

  • mini courses (Excel, CV writing, budgeting basics)

If you want course platforms, you can explore Udemy or Teachable.

Tip: don’t promise guaranteed results—focus on clear learning outcomes.

7) Customised tech accessories

Tech accessories are popular because people use them daily and love personalisation.

Things to sell:

  • phone cases

  • laptop sleeves

  • AirPods covers

  • cable organisers

Profit tip: bundle items (e.g., case + cable organiser) to increase order value.

8) Natural beauty products (be careful with claims)

Beauty products can sell well, but they require extra trust because they’re applied to the body.

Safer product types:

  • handmade soaps

  • body scrubs

  • bath salts

  • lip balms

Note: don’t claim your product “treats” medical conditions unless you’re qualified and legally compliant. Keep claims honest and descriptive (e.g., “moisturising”, “fragranced”, “gentle”).

9) Second-hand books

Books are easy to list, easy to ship, and always in demand—especially textbooks and exam-related material.

What sells well:

  • textbooks

  • business books

  • kids book bundles

  • exam prep guides

Profit tip: bundle similar books to raise cart value.

10) Handmade furniture and small home décor

Furniture can be high profit, but heavy shipping can be a challenge—so start with items that sell well locally.

Things to sell:

  • floating shelves

  • plant stands

  • bedside pedestals

  • wooden trays and décor items

Tip: offer pickup and meet in public places.

Digital vs physical products: which is better to start with?

Product type Examples Best for Pros Watch-outs
Digital products Printables, templates, study guides Selling nationwide or globally No shipping, high margins, repeat sales Needs good design + clear download instructions
Physical products (small) Jewellery, phone cases, books Beginners + delivery Easier to ship, good repeat sales Packaging and courier delays
Physical products (large) Furniture, bulk bundles Local pickup High value per sale Heavy logistics, higher scam risk
Food products Cookies, cupcakes, cakes Local pre-orders Strong demand for events Food safety, allergens, delivery risk

Where to sell your products online in South Africa

Here are common platforms depending on your product:

  • Facebook Marketplace (fast local sales, higher scam risk)

  • Bob Shop (South Africa-friendly marketplace)

  • Instagram (best for building a brand and repeat buyers)

  • Etsy (best for handmade and digital products)

  • Shopify (best if you want your own online store)

If you want to compare platforms and build a more stable store long-term, start with Shopify’s guide to selling online.

Staying safe: online selling scams in South Africa (Facebook Marketplace & Gumtree)

South Africa is notorious for scammers, especially on platforms like Facebook Marketplace and Gumtree. If you’re learning what to sell to make money in south africa, seller safety should be part of your plan.

Common scams (and how to avoid them)

1) Fake proof of payment (POP)
Scammers send a screenshot and pressure you to hand over the item.
✅ Only release the item once the money reflects in your bank account.

2) Courier collection scams
They claim a courier will collect and you’ll get paid later.
✅ Avoid this. Use couriers you arrange yourself after confirmed payment.

3) OTP / banking login scams
They pretend to be “payment support” and ask for OTPs or logins.
✅ Never share OTPs, PINs, or online banking login details.

4) Refund scams
They claim they overpaid and ask you to refund the difference.
✅ Never refund unless payment has fully cleared.

Quick seller safety checklist

✅ Payment must reflect (not just a screenshot)

✅ Meet in public places for collections

✅ Don’t click unknown payment links

✅ Don’t share OTPs or banking details

✅ Trust your gut—if it feels rushed or confusing, walk away

How to maximise profits (without burning out)

Price for profit (not just to sell fast)

Pricing should include:

  • materials

  • packaging

  • delivery costs

  • platform fees

  • your time

  • profit margin

Use simple SEO in your listings

If you want your products to show up in search results, use clear keywords in your product title and description.

Example:

  • “Handmade beaded bracelet (custom colours)” is better than

  • “Pretty bracelet”

Build trust so buyers come back

Repeat business comes from:

  • great photos

  • honest descriptions

  • realistic delivery times

  • fast, polite replies

If you’re building your income carefully and want to manage money responsibly, you can explore personal loan options (only if it fits your budget and you can repay comfortably).
Find out what to sell to make money in South Africa with FatCat Loans.

Common challenges (and how to handle them)

Shipping and handling: Use tracking and pack well.
Inventory: Start small, test demand, reinvest profits.
Returns: Have a clear policy and keep communication polite and professional.
Time management: Set a daily routine (even 20–30 minutes) for messages and fulfilment.

Conclusion: what to sell, what can I sell, and how to start

If you’re still asking what can i sell or what to sell, the best approach is to start with items that are:

✅ in demand
✅ easy to source
✅ easy to deliver
✅ profitable after costs

The simplest way to begin is to choose one category (like second-hand clothes, books, or printables), list 10–20 items, and learn what sells. That’s how most profitable online sellers start.

FAQs

What to sell to make money fast?

Second-hand items like clothes, books, and small household goods often sell fastest because you can list them immediately and deliver locally.

What can I sell to make money from home?

Digital products, printables, handmade items, and study packs are great options because you can create and manage them from home.

What are the best things to sell online in South Africa?

Second-hand clothing, customised accessories, books, gift boxes, and digital products are popular in South Africa.

What can I sell to make money in South Africa without spending a lot?

Start with items you already own, or digital products that have low creation costs.

Is it safe to sell on Facebook Marketplace in South Africa?

It can be, but scams are common. Only release items once payment reflects, avoid courier payment tricks, and never share OTPs or banking details.
Expert Insights: How Long Credit Score Takes to Improve

Improving your credit score is a process that requires time, patience, and consistent effort. In this blog, we will delve into the key aspects of credit improvement and provide expert insights on how long it takes to see improvements in your credit score.

Key Factors

→ Building a good credit score takes time and consistent effort.

→ Factors such as payment history, credit utilisation, and credit affect your credit score.

→ A good credit score is important for financial health, as it can lead to lower interest rates and better loan.

→ Initial steps to improve your credit score include checking your credit report for errors and setting up payment reminders.

→ Strategies for building a stronger credit profile include reducing credit utilisation ratios and diversifying credit accounts.

→ Handling debt and delinquencies effectively is crucial for improving your credit score.

→ Credit inquiries and new accounts can impact your credit score, so it’s important to be cautious.

→ Long-term credit improvement practices include maintaining older credit accounts and regularly monitoring your credit for fraud and accuracy.

Improving your credit score is a process that requires time, patience, and consistent effort. It’s important to understand the factors that contribute to your credit score and take the necessary steps to build a strong credit profile. By doing so, you can increase your chances of obtaining better loan terms, lower interest rates, and overall financial stability. In this blog, we will delve into the key aspects of credit improvement and provide expert insights on how long it takes to see improvements in your credit score.

Understanding Credit Scores and Their Importance

Before we discuss the timeline for credit score improvement, let’s first understand what credit scores are and why they are important. A credit score is a three-digit number that represents your creditworthiness. It is calculated based on the information in your credit report, which is a detailed record of your credit history. Credit bureaus, such as TransUnion and Experian, collect and maintain these credit reports. Lenders and creditors use credit scores to assess your creditworthiness and make decisions about granting credit.

What Makes Up Your Credit Score?

Several factors contribute to your credit score, and understanding them is crucial for improving your credit. The main components of a credit score include:

→ Payment history: This refers to your track record of making payments on time. Late payments or missed payments can have a negative impact on your credit score.

→ Credit utilization ratio: This is the percentage of your available credit that you are currently using. A high credit utilization ratio can indicate financial distress and negatively affect your credit score.

→ Credit history: The length of your credit history plays a role in determining your credit score. A longer credit history demonstrates your ability to manage credit responsibly.

→ New credit: Opening multiple new credit accounts within a short period can be perceived as a risk by lenders and may lower your credit score.

Why a Good Credit Score Matters for Financial Health

Having a good credit score is essential for maintaining financial health. Lenders and creditors use credit scores to determine the interest rates and loan terms they offer you. A higher credit score can result in lower interest rates, which can save you a significant amount of money over time. It also gives you access to a wider range of credit options, including credit cards, personal loans, and mortgages. With a good credit score, you have more negotiating power and can secure better terms and conditions for your financial needs. Additionally, a good credit score reflects your ability to manage credit responsibly, which is important for future financial endeavours.

Initial Steps to Take for Improving Your Credit Score

Now that we understand the importance of a good credit score, let’s discuss the initial steps you can take to start improving your credit. The first step is to obtain a copy of your credit report from each of the major credit bureaus. Review your credit report carefully to identify any errors or discrepancies. Disputing and correcting these errors can have a positive impact on your credit score. Next, it’s essential to develop good credit habits, such as paying your bills on time and in full. Timely payments show lenders that you are responsible and can be trusted with credit.

Checking Your Credit Report for Errors

Checking your credit report for errors is an important step in improving your credit score. Errors in your credit report can lower your credit score and may affect your ability to obtain credit. Start by obtaining a copy of your credit report from each of the major credit bureaus. Carefully review the information for accuracy, including personal details, account balances, and payment history. If you identify any errors, such as accounts that don’t belong to you or incorrect payment information, you can dispute them with the credit bureaus. They are required by law to investigate and correct any inaccuracies within a reasonable time frame.

Setting Up Payment Reminders and Auto-Payments

One of the most crucial factors in improving your credit score is your payment history. Late payments or missed payments can have a significant negative impact on your credit score. To ensure timely payments, consider setting up payment reminders or auto-payments. Here are some strategies to help you stay on top of your payments:

→ Set up automatic payments for your bills, ensuring they are paid on time.

→ Use calendar reminders or apps to notify you of upcoming due dates.

→ Consider enrolling in electronic alerts that can be sent to your email or mobile phone.

→ Create a budget to help you manage your finances and allocate funds for your monthly payments.

Strategies for Building a Stronger Credit Profile

Building a stronger credit profile involves implementing strategies that focus on improving key areas of your credit history. Two important aspects to consider are reducing your credit utilization ratio and diversifying your credit accounts.

→ Reducing credit utilization ratios below 30%: Keeping your credit utilization ratio low demonstrates responsible credit management and can positively impact your credit score.

→ Diversifying credit accounts responsibly: Having a mix of different credit accounts, such as credit cards and loans can demonstrate your ability to manage various types of credit responsibly and contribute to a good credit score.

Reducing Credit Utilization Ratios Below 30%

One effective strategy for improving your credit score is to reduce your credit utilization ratio. Your credit utilization ratio is the percentage of your available credit that you are currently using. Keeping this ratio below 30% demonstrates responsible credit management and can positively impact your credit score. Here are some tips to help you reduce your credit utilization ratio:

→ Pay down credit card balances: Start by paying off credit card debt and keeping balances as low as possible.

→ Increase your credit limits: If you have a good payment history, consider requesting a credit limit increase on your credit cards. This can increase your available credit and lower your credit utilization ratio.

→ Consider balance transfers: If you have high-interest credit card debt, you may want to explore balance transfer options to consolidate your debt and potentially lower your credit utilization ratio.

Diversifying Credit Accounts Responsibly

Diversifying your credit accounts responsibly is another strategy that can contribute to a stronger credit profile. Lenders and creditors like to see a mix of different types of credit accounts when assessing your creditworthiness. Here are some steps you can take to diversify your credit accounts:

→ Consider opening a new credit card: Having a mix of credit cards and other types of credit, such as instalment loans, can demonstrate your ability to manage different types of credit responsibly.

→ Use caution when opening new accounts: While diversifying your credit mix is important, it’s essential to avoid opening too many new accounts within a short period. Multiple new accounts can negatively impact your credit score and suggest financial instability.

Handling Debt and Delinquencies Effectively

Effectively managing debt and addressing delinquencies is crucial for improving your credit score. Taking proactive steps to handle your debts can positively impact your credit profile. Here are some strategies to consider:

→ Prioritising outstanding debts: Make a list of all your outstanding debts and prioritize them based on interest rates and payment terms. Focus on paying off high-interest debts first.

→ Negotiating payoffs: If you’re struggling to make payments, consider reaching out to your creditors to negotiate payoffs or repayment plans. This can demonstrate your commitment to resolving your debts and may help improve your credit score.

Prioritizing Outstanding Debts and Negotiating Payoffs

One effective strategy for handling debt and improving your credit score is to prioritize outstanding debts and negotiate payoffs. Prioritizing your debts allows you to allocate your resources effectively and focus on paying off high-interest debts first. Here are some steps to consider:

→ List all your outstanding debts: Make a comprehensive list of all your debts, including credit card balances, personal loans, and any other outstanding obligations.

→ Assess interest rates: Determine the interest rates for each debt and prioritize paying off the debts with the highest interest rates first. This can save you money in the long run.

→ Negotiate with creditors: If you’re struggling to make payments, consider reaching out to your creditors to negotiate payment plans or potentially reduce interest rates. This shows a proactive approach to managing your debts and can have a positive impact on your credit score.

The Impact of Paying Off Collections on Your Credit Score

Paying off collections can have a significant impact on your credit score. Collection accounts occur when your unpaid debts are sold to third-party collection agencies. These accounts have a negative impact on your credit score and can hinder your ability to obtain credit in the future. Here’s how paying off collection accounts can help improve your credit score:

→ Remove negative information: Paying off collections can result in the removal of negative information from your credit report. While the original collection account will remain on your report, the updated status can improve your credit score.

→ Demonstrate responsible credit management: By resolving collection accounts, you demonstrate to lenders that you are taking responsibility for your debts and can be trusted with credit. This can positively impact your creditworthiness and improve your credit score over time.

Find out how long it takes to improve your credit score.

The Role of Credit Inquiries and New Accounts

Credit inquiries and new accounts can impact your credit score, so it’s important to understand their role in credit improvement. When you apply for new credit, lenders typically make a hard inquiry into your credit report. Multiple hard inquiries within a short period can lower your credit score. Additionally, opening new accounts can impact the average age of your credit history, which is a factor in determining your credit score.

How Hard Inquiries Affect Your Credit Score

Hard inquiries can have a temporary negative impact on your credit score. When you apply for new credit, lenders request your credit report to assess your creditworthiness. Each hard inquiry can lower your credit score by a few points. However, the impact is typically minimal and short-lived. Here are some key points to keep in mind:

→ Multiple hard inquiries for the same type of credit within a short period are generally treated as a single inquiry and have a minimal impact on your credit score.

→ Hard inquiries remain on your credit report for two years but only affect your credit score for the first 12 months.

→ The impact of hard inquiries diminishes over time, and as long as you continue to use credit responsibly, your credit score will recover.

The Truth About Opening New Credit Lines

Opening new credit lines can be a double-edged sword when it comes to improving your credit score. On one hand, it can increase your available credit and potentially lower your credit utilization ratio. On the other hand, it can lower the average age of your credit history, which is another factor in determining your credit score. Here are some important points to consider:

→ Opening new credit lines should be done responsibly and with caution.

→ When opening new accounts, consider the impact on your credit mix, credit utilization ratio, and average age of credit.

→ Requesting credit limit increases on existing accounts can be a viable option to increase your available credit without the potential negative impact of opening new accounts.

Long-Term Credit Improvement Practices

Long-term credit improvement is about developing good credit practices and maintaining a positive credit history. Here are two practices to focus on:

→ Maintaining older credit accounts for length of history:

The age of your credit accounts contributes to your credit score. Keeping older accounts open, even if they have a zero balance, can help improve your credit score over time because they show lenders that you have a track record of responsible credit management. Additionally, closing older accounts can lower the average age of your credit history, which may negatively affect your credit score. Keeping these accounts open can help maintain a longer average age of credit.

→ Regularly monitoring your credit for fraud and accuracy:

Regularly checking your credit reports for errors or fraudulent activity is crucial for maintaining good credit. Monitoring your credit can help detect and address any issues promptly, such as accounts that don’t belong to you, incorrect payment history, unauthorized activity or signs of identity theft, ensuring the accuracy and integrity of your credit history. You are entitled to a free credit report from each of the major credit bureaus once a year. Take advantage of this opportunity to review your credit reports and ensure their accuracy.

Conclusion

Improving your credit score takes time and effort, but it’s worth the investment for your financial well-being. By understanding what influences your score and taking proactive steps like checking for errors, setting up payment reminders, and managing debt responsibly, you can gradually build a stronger credit profile. Remember to diversify credit accounts, monitor for fraud, and be patient as you work towards long-term improvement. Small changes can have a big impact over time, so stay committed to your financial goals and watch your credit score reflect your responsible habits.

Frequently Asked Questions

How Long Does It Typically Take to See Credit Score Improvements?

The timeline for seeing credit score improvements varies depending on individual circumstances. Generally, it takes three to six months of positive credit activity to see noticeable changes in your credit score. However, significant improvements may take longer, and long-term credit improvement is a continuous process.

Can Small Changes Make a Big Difference in My Credit Score?

Yes, small changes in your credit habits can make a big difference in your credit score over time. Consistently practicing good credit habits, such as making on-time payments and keeping credit utilization low, can have a positive impact on your credit score and overall creditworthiness.

What to Do If Your Credit Score Isn’t Improving?

If your credit score isn’t improving despite your efforts, there may be potential issues that need to be addressed. Consider reviewing your credit reports for any negative information or errors that may be impacting your score. Additionally, consult with a financial professional for guidance on improvement strategies tailored to your specific situation.

Debt Consolidation Meaning in South Africa: How It Works

Dealing with multiple debts can be overwhelming and stressful. This is where debt consolidation comes in. Debt consolidation is a financial strategy that involves combining multiple debts into a single loan or credit card. In this blog, we will explore what debt consolidation is, how it works, and the factors to consider before consolidating your debts.

Debt Consolidation Meaning in South Africa

Updated October 2026

Debt consolidation means combining two or more existing debts into one new loan, usually with a single monthly repayment. In South Africa, people may consider debt consolidation when they have several credit accounts, personal loans or store accounts with different repayment dates and interest rates.

The main purpose is to make existing debt easier to manage. Depending on the interest rate, fees and repayment period of the new loan, consolidation may also reduce monthly repayments or borrowing costs. However, savings are not guaranteed.

This guide explains what debt consolidation means, how it works in practice, which debts may be included and when it might be worth considering.

What Does Debt Consolidation Mean in South Africa?

Debt consolidation is a form of refinancing. Instead of continuing to repay several separate debts, you take out a new loan and use it to settle eligible existing balances.

If the consolidation is completed successfully, you repay the new loan according to its agreed terms.

Debts that may be eligible for consolidation include:

  • Credit card balances
  • Store accounts
  • Personal loans
  • Short-term loans
  • Other qualifying unsecured credit agreements

Eligibility depends on the lender, the type of debt and your financial circumstances. Not every account or outstanding balance can necessarily be consolidated.

Important: Debt consolidation does not cancel or forgive what you owe. It replaces eligible existing debt with a new repayment obligation.

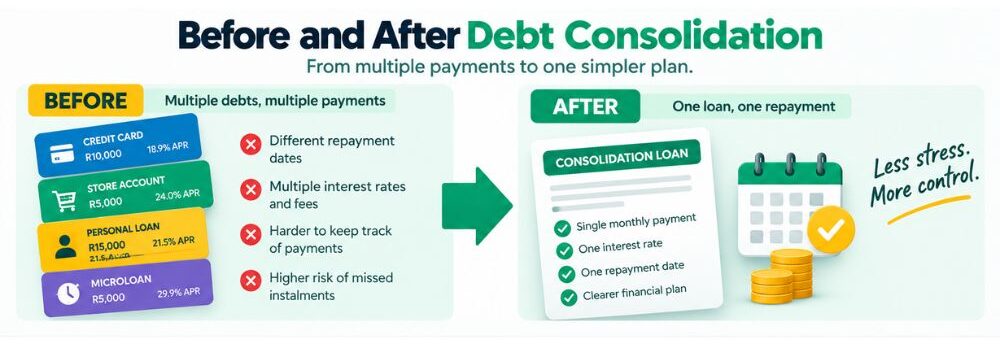
Debt Consolidation Example in South Africa

Imagine you have three outstanding debts:

  • Credit card: R10,000
  • Store account: R5,000
  • Personal loan: R15,000

Your total outstanding debt is R30,000.

If a lender approves a suitable R30,000 consolidation loan, the money could be used to settle those three balances. You would then repay the new loan through one monthly instalment rather than making three separate payments.

This example illustrates how consolidation works. It does not mean your monthly repayment or total borrowing cost will necessarily decrease.

The new loan’s interest rate, fees and repayment term determine whether it is financially worthwhile. A longer repayment period can reduce the monthly instalment while increasing the total interest paid.

Before and after debt consolidation in South Africa

For a more detailed explanation, read our guide to how debt consolidation loans work in South Africa.

Benefits of Debt Consolidation

Knowing what consolidation means empowers you to make informed financial decisions. Here are some key benefits:
1️⃣ Fewer Monthly Payments:

Managing one repayment may make budgeting easier.

2️⃣Potentially Lower Borrowing Costs:

Possible if the new loan’s total cost is lower, including fees.

3️⃣ More Predictable Repayments:

A fixed-term loan can provide a defined repayment schedule.

For more financial guidance, explore resources at the National Credit Regulator (NCR).

4️⃣ Possible Monthly Cash-Flow Relief:

A lower instalment may help, but extending the term can cost more overall.

5️⃣ An Opportunity to Simplify Debt Management:

Consolidation may help with organisation, but doesn’t automatically improve a credit score or resolve overspending.

What If Debt Consolidation Is Not Right for You?

Debt consolidation is not suitable for everyone. If you cannot comfortably afford the repayments on a new loan, borrowing more money may make your financial position worse.

Other options worth exploring include:

  • Contacting existing creditors: Ask whether alternative payment arrangements may be available.
  • Reviewing your household budget: Identify essential expenses and determine what you can realistically afford to repay.
  • Prioritising existing debt repayments: Consider a structured repayment strategy if you can meet your obligations without refinancing.
  • Seeking debt counselling: If you are over-indebted, an NCR-registered debt counsellor can assess whether debt review may be appropriate.

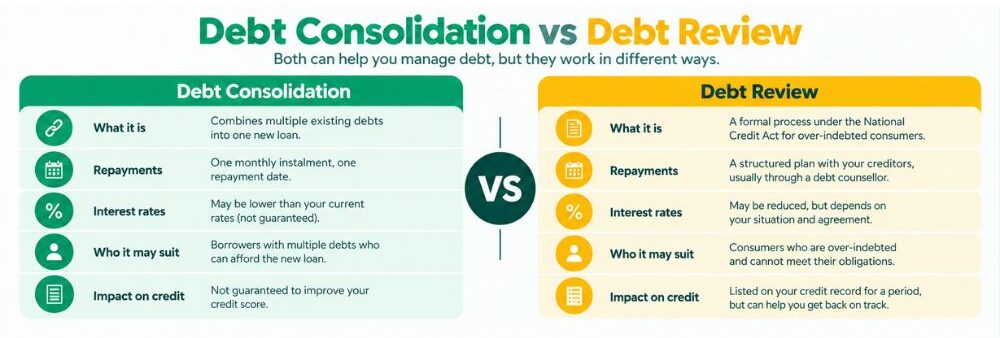
Debt review is different from taking out a consolidation loan. It is a regulated process under South Africa’s National Credit Act and may be more appropriate for consumers who are unable to meet their existing credit obligations.

You can find information about registered debt counsellors and consumer protections through the National Credit Regulator.

Debt consolidation vs debt review in South Africa

Does Your Credit Score Matter for Debt Consolidation?

Yes. Your credit history is one of several factors lenders may consider when assessing a debt consolidation loan application in South Africa.

Lenders may assess:

  • Credit history: How you have managed previous credit agreements and repayments.
  • Income: Whether you have sufficient, verifiable income to support the proposed repayments.
  • Existing debt: Your current credit commitments and outstanding balances.
  • Affordability: Whether you can reasonably afford the new loan alongside your essential living expenses and other financial obligations.

A stronger credit profile may improve your chances of qualifying for more favourable terms, but approval and interest rates depend on the lender’s assessment. A good credit score does not guarantee approval.

Before applying, consider checking your credit report through a registered South African credit bureau. This can help you identify inaccurate information and understand your existing credit commitments.

For more information about eligibility, read our guide to debt consolidation loan approval in South Africa.

How Debt Consolidation Works from Start to Finish

Understanding debt consolidation is only the first step. Here’s how the actual process works:

Step 1 – List Your Debts

Write down:

  • Balances
  • Interest rates
  • Minimum monthly payments
  • Due dates

This helps you determine whether consolidation will save you money.

Step 2 – Explore Debt Consolidation Loan Options

Research available debt consolidation loan options and compare important details such as interest rates, fees, repayment periods and total repayment costs.

FatCat Loans is a loan comparison and matching service, not a lender. You can use the platform to explore available loan options, but eligibility, approval and final loan terms are determined by the lender.

Step 3 – Submit Your Application

If you decide to proceed, you may need to provide information and supporting documents for the lender’s affordability and credit assessment.

Depending on the lender, this may include:

  • Valid identification
  • Proof of income or other income information
  • Recent bank statements
  • Proof of residential address
  • Details of your existing debts

Requirements vary between lenders. Submitting an application does not guarantee approval.

Step 4 – Settle the Existing Debts

If your consolidation loan is approved and paid out, the funds are used to settle the eligible debts included in the arrangement.

Depending on the lender and loan agreement, funds may be paid directly to creditors or provided to you for settlement.

Confirm that the intended debts have been settled and retain any settlement confirmations. Paying off a credit account does not necessarily mean the account has been closed.

Step 5 – Repay the New Loan

You then repay the consolidation loan according to its agreed interest rate, repayment schedule and loan term.

Continue making repayments on time and avoid accumulating new debt on accounts that remain open.

Common Debt Consolidation Mistakes to Avoid

Understanding what debt consolidation means also involves recognising the risks. Some common mistakes include:

Taking on New Debt After Consolidation

If you continue borrowing on credit cards or store accounts after settling their balances, you could end up with both the consolidation loan and new outstanding debts.

Looking Only at the Monthly Instalment

A lower monthly repayment does not necessarily mean a cheaper loan. Extending the repayment period may increase the total interest paid.

Overlooking Fees and Loan Terms

Check the applicable interest rate, initiation fees, monthly service fees, total repayment amount and any relevant early-settlement terms before accepting an offer.

Not Comparing the Total Cost

Compare the total amount repayable on the new loan with the cost of continuing to repay your existing debts. Consider the repayment period as well as the monthly instalment.

Failing to Confirm Existing Debts Are Settled

After consolidation, check that the intended creditors have received payment and that the relevant balances have been updated. Keep settlement records and check whether any accounts remain open.

Compare debt consolidation options

Frequently Asked Questions About Debt Consolidation

What does debt consolidation mean in simple terms?

Debt consolidation means combining two or more existing debts into one new loan. The new loan is used to settle eligible outstanding balances, leaving you with one repayment arrangement for the consolidated debt.

Does debt consolidation reduce the amount you owe?

Not automatically. Debt consolidation usually replaces existing debt rather than reducing or cancelling it. Whether it saves money depends on the new interest rate, fees and repayment period.

Does debt consolidation improve your credit score?

Not automatically. Your credit score may change depending on the new credit application, your repayment history, outstanding balances and how you manage your accounts after consolidation. Making repayments on time can support a healthier credit history over time.

Can anyone qualify for a debt consolidation loan?

No. Lenders assess factors such as income, affordability, credit history and existing financial obligations. Approval is not guaranteed, and consumers under debt review are generally restricted from taking on further credit.

Is debt consolidation the same as debt review?

No. Debt consolidation involves taking out a new loan to settle eligible existing debts. Debt review is a regulated process under South Africa’s National Credit Act for consumers who are over-indebted. It involves a registered debt counsellor and does not work in the same way as refinancing.

If you are considering combining existing debts, you can explore debt consolidation loan options in South Africa to learn more about the available options and what to consider before applying.

Conclusion: Understanding Debt Consolidation in South Africa

Debt consolidation means combining eligible existing debts into one new loan, usually with a single monthly repayment. For some South Africans, this can make repayments easier to organise and may offer more suitable loan terms.

However, consolidation does not eliminate debt or guarantee lower borrowing costs. Before deciding whether it is worthwhile, compare the new loan’s interest rate, fees, repayment period and total amount repayable against your existing commitments.

If you are struggling to afford essential expenses or meet your current debt repayments, consider speaking to your creditors or an NCR-registered debt counsellor before taking on further credit.

FatCat Loans is a loan comparison and matching service, not a lender. Loan approval, affordability assessments and final credit terms are determined by the lender.

South Africa Prime Rate (2026): Current Prime Interest Rate & Guide

The South Africa Prime Rate (prime interest rate) affects what you pay on home loans, vehicle finance, personal loans and credit cards. This guide explains the current prime rate, how it changes, how it compares to the repo rate, and what even small rate moves can mean for your monthly repayments.

South Africa Prime Rate

Updated March 2026

Understanding how interest rates shift can feel overwhelming, but knowing the South Africa Prime Rate gives you a clear advantage when managing your finances. Whether you’re applying for a loan, planning a mortgage, or simply tracking economic trends, the South Africa Prime Rate plays a major role in what you pay and how you plan for the future. Even a small rate change can affect what you pay each month — especially on long-term debt like a home loan.

The South Africa Prime Rate is also commonly referred to as the prime rate, and it affects home loans, vehicle finance, personal loans and credit cards.

What Is a Prime-Linked Loan?

A prime-linked loan is priced relative to South Africa’s prime rate (often shown as “prime + X%”). Offers and margins vary by credit provider and affordability assessment.

To estimate repayments at different rates, use the loan calculator.

If you’re comparing loan options, see our guide to personal loans in South Africa to understand how lenders price interest relative to prime.

Key Highlights to the South Africa Prime Rate

→ Current lending rate (South Africa): 10.25% (as of 2 January 2026)

→ Prime is influenced by the repo rate, set by the South African Reserve Bank (SARB)

→ Prime is typically around 3.50% above the repo rate, though banks may adjust borrower pricing above or below prime

→ Prime rate changes impact home loans, vehicle finance, personal loans, and credit cards

→ Borrowers can often reduce their rate by improving credit score and comparing offers across banks

Current Prime Interest Rate in South Africa (Updated)

As of 2 January 2026, the prime rate (prime lending rate) in South Africa is 10.25%. The South African Reserve Bank (SARB) also reports the repo rate at 6.75%, and commercial banks typically price prime as repo rate + 3.50%.

Quick summary:

  • Repo rate: 6.75%

  • Lending rate: 10.25%

  • Difference: Prime is usually 3.50% above repo

Source: South African Reserve Bank (SARB) – Current Market Rates

Understanding South Africa’s Prime Rate

The prime rate, also known as the prime lending rate or lending rate, is the benchmark rate used by commercial banks to determine the interest rates they charge for loans. It serves as a reference point for other interest rates in the economy.

In South Africa, it is influenced by the repo rate set by the South African Reserve Bank (SARB). Understanding the prime rate is crucial for individuals considering home loans or other forms of borrowing, as it directly affects the cost of their loans.

The prime rate is important because it affects the cost of borrowing for individuals and businesses. Even a small change in the benchmark lending rate can affect your monthly repayment.

Historical Overview of the South Africa Prime Rate

Historical trends of the prime rate in South Africa have shown periods of rate hikes and cuts. Over the past couple of years, there have been several rate hikes as the SARB aimed to combat inflation. However, experts predict that the rate hikes may be coming to an end, and there is even a possibility of rate decreases in the future. It is important for borrowers to stay informed about historical trends in order to assess the potential impact of future rate changes on their loans and mortgages.

Here’s a quick snapshot of the most recent South Africa Prime Rate changes, which typically move in line with SARB repo rate decisions.

Effective date Prime lending rate Change What happened (quick context)
20 Nov 2025 10.25% -0.25% SARB reduced the repo rate, which lowered prime shortly after.
1 Aug 2025 10.50% -0.25% Continued easing cycle as inflation pressures eased and growth remained weak.
30 May 2025 10.75% -0.25% Further cut as policy shifted toward supporting economic activity.
31 Jan 2025 11.00% -0.25% Early cut after the rate-hike cycle ended and inflation moderated.
22 Nov 2024 11.25% -0.25% SARB began lowering rates after holding or hiking through the high-inflation period.
20 Sep 2024 11.50% -0.25% First cut in the cycle as inflation conditions improved and policy outlook softened.

For the latest official update, refer to the SARB’s “Current Market Rates” page, which publishes both repo rate and prime lending rate figures.

Factors Influencing the South Africa Prime Rate

Several factors influence the prime rate in South Africa. Economic indicators, such as inflation and economic growth, play a significant role in determining the prime rate. The South African Reserve Bank (SARB) also plays a crucial role in setting the repo rate, which ultimately influences the prime rate. Understanding these factors can help borrowers anticipate and prepare for potential changes in the prime rate.

The Role of the South African Reserve Bank (SARB)

The South African Reserve Bank (SARB) is responsible for formulating and implementing monetary policy in South Africa. One of its key tools is the repo rate, which is the rate at which the SARB lends to commercial banks. Changes in the repo rate directly affect the prime rate, as commercial banks add a margin to the repo rate to determine the prime lending rate. The SARB closely monitors economic indicators and adjusts the repo rate accordingly to manage inflation and economic stability. Rate changes by the SARB have a direct impact on the cost of borrowing for individuals and businesses.

Economic Indicators Affecting the South Africa Prime Rate

Several economic indicators play a role in determining the prime rate. Inflation, economic growth, and market conditions are key factors that influence the prime rate. When inflation is high or the economy is growing rapidly, there is a higher chance of interest rate hikes, which can lead to an increase in the prime rate. On the other hand, if inflation is low or the economy is sluggish, interest rate cuts may occur, resulting in a decrease in the prime rate. Monitoring these economic indicators can provide insights into potential changes in the prime rate.

What Makes the SARB Raise or Cut Interest Rates?

The SARB’s core mandate is to protect price stability and manage inflation expectations. In practice, the SARB’s MPC decisions are influenced by:

  • Inflation trends (CPI) and inflation expectations

  • Economic growth (GDP) and employment pressures

  • Global interest rate conditions and exchange rate volatility

  • Oil prices, food prices, and administered costs

  • Broader financial stability risks

This is why South Africa’s prime rate changes often happen when inflation pressures rise — and why rate cuts typically occur when inflation eases and growth slows.

How the Current Prime Rate Affects Borrowers

As of 2 January 2026, the South Africa Prime Rate (lending rate) is 10.25%. This rate directly affects borrowing costs across home loans, vehicle finance, personal loans, and some credit products — which means changes can influence your monthly repayment and affordability.

How the Current Prime Rate Affects Loans and Mortgages

How Much Does the Prime Rate Change Your Monthly Repayment? (Real Example)

Even a small small prime rate move can change your repayment more than most borrowers expect.

Here’s a simple example using a R1,000,000 home loan over 20 years:

  • At prime rate 10.25%, your monthly repayment is approximately R9,900 – R10,100

  • If prime increases by 0.25%, your repayment can rise by roughly R150 – R200 per month

  • If prime decreases by 0.25%, your repayment could fall by roughly R150 – R200 per month

Why this matters: Rate changes compound across the full loan term — so even small movements can add up to thousands of rand over time.

The current South Africa Prime Rate has implications for various types of loans and mortgages. Here are a few ways it affects borrowers:

  • Home loans: The interest rate on home loans is directly linked to the prime rate. As the South Africa Prime Rate increases or decreases, the interest rate on a home loan will also change, impacting the monthly repayments.
  • Vehicle finance: Similar to home loans, the interest rate on vehicle finance is influenced by the prime rate. Changes in the prime rate can affect the monthly repayments for vehicle finance.
  • Other loans: Personal loans, credit cards, and other forms of borrowing may also be impacted by changes in the prime rate, as the interest rates on these loans are often linked to the prime rate.

Note: Repayments are estimates and will vary based on loan term, fees, and lender pricing margins.

If you want to see how the benchmark lending rate changes affect your repayment, you can estimate your monthly repayments using our calculator.

Comparing Current Rates to Historical Trends

It is important to compare the current prime rate to historical trends in order to assess the potential impact on loans and mortgages. By understanding how the current rate compares to past rates, borrowers can gain insights into the potential direction of future rate changes. Monitoring historical trends can also help borrowers make informed decisions about when to lock in a prime rate for their loans or mortgages.

Prime Rate Versus Repo Rate

The South Africa Prime Rate and the repo rate are two important concepts in the South African financial system. While both are interest rates, they serve different purposes in the borrowing and lending process. The repo rate is set by the South African Reserve Bank (SARB) and determines the cost at which commercial banks can borrow funds from the SARB. The prime rate, on the other hand, is the rate at which commercial banks lend to their most creditworthy customers. Understanding the difference between these rates is important for borrowers and investors in assessing the cost of borrowing and making financial decisions.

Understanding the Difference

The prime rate and the repo rate are distinct interest rates that play different roles in the South African financial system. The repo rate is set by the South African Reserve Bank (SARB) and serves as a benchmark for the cost of funds for commercial banks. It is the rate at which the SARB lends money to commercial banks, and changes in the repo rate can have a ripple effect on various interest rates in the economy, including the prime rate. The prime rate, on the other hand, is set by individual commercial banks and is the rate at which they lend to their most creditworthy customers. It is typically higher than the repo rate and reflects the bank’s margin for profit.

Prime Rate vs Your Personal Loan Rate (Prime + / Prime – Explained)

The lending rate is a benchmark — but your actual loan rate is usually quoted as:

  • Prime – X% (better credit, larger deposit, lower risk)

  • Prime + X% (higher risk, smaller deposit, adverse credit)

For example:

  • Someone with strong credit and a large deposit might get prime – 1.0%

  • Someone with a weaker credit profile might get prime + 3.0%

That’s why two borrowers can take out the same loan amount and pay very different monthly repayments.

Key takeaway: Prime rate sets the baseline — your credit score and affordability determine how far above or below prime your offer will be.

Impact of Repo Rate Changes on the South Africa Prime Rate

Changes in the repo rate set by the South African Reserve Bank (SARB) have a direct impact on the prime rate. When the repo rate is increased, commercial banks may also raise their prime rates in response, leading to higher borrowing costs for consumers. Conversely, when the repo rate is decreased, commercial banks may lower their prime rates, resulting in lower borrowing costs. It is important for borrowers to monitor repo rate changes as they can have a significant impact on the affordability of loans and mortgages.

Strategies to Benefit from the Prime Rate

Borrowers can take advantage of the South Africa Prime Rate to secure lower interest rates on their loans and mortgages. Here are a few strategies to consider:

  • Improve credit score: A higher credit score can lead to lower interest rates. Borrowers should focus on maintaining a good credit record by paying bills on time and reducing debt.
  • Increase deposit size: A larger deposit can reduce the risk for lenders, resulting in lower interest rates. Savvy borrowers should consider saving for a larger deposit before applying for a loan.
  • Use a loan comparison service: Comparing loan offers from multiple banks can help borrowers find the best deal with lower interest rates.

South Africa Prime Rate with FatCat Loans

Tips for Homebuyers and Mortgage Holders

If you’re a homebuyer or mortgage holder looking to benefit from the prime rate, here are some tips to consider:

  • Save for a larger deposit: A higher deposit can lead to lower interest rates and reduced monthly repayments.
  • Understand transfer costs: In addition to the loan amount, consider the additional costs associated with buying a property, such as transfer costs. These costs can impact the overall affordability of a home loan.
  • Compare loan offers: Use a home loan comparison service to compare loan offers from multiple banks. This can help you find the best deal with lower interest rates and favourable terms.

Advice for Investors and Savers

Investors and savers can also benefit from the South Africa Prime Rate. Here are some tips for maximizing returns:

  • Savings accounts: Look for savings accounts that offer competitive interest rates. As the prime rate decreases, savings account interest rates may also decrease, affecting the return on savings.
  • Lower monthly repayments: If you have existing loans or mortgages, a decrease in the prime rate may lead to lower monthly repayments. Consider using the savings to increase investments or savings.

When Does South Africa’s Prime Rate Change?

The lending rate usually changes after the South African Reserve Bank announces a repo rate decision through its Monetary Policy Committee (MPC). If the SARB changes the repo rate, banks typically adjust prime shortly after.

The SARB publishes updated figures on its official “Current Market Rates” page, which is the most reliable way to confirm South Africa’s latest prime rate.

Conclusion: Making Smart Financial Decisions with the South Africa Prime Rate

Understanding South Africa’s prime rate helps you make better financial decisions.

It affects home loans, vehicle finance, personal loans, and many other forms of borrowing.

Historical trends, economic indicators, and the SARB play vital roles in determining the current prime rate. By monitoring these factors, individuals can strategize to benefit from favourable rates. Stay informed about the latest South Africa Prime Rate changes to make informed financial choices. Whether you are a homebuyer, investor, or saver, being proactive in understanding and leveraging the prime rate can lead to significant financial advantages. Prepare for potential rate fluctuations by staying updated on expert opinions and economic forecasts.

Frequently Asked Questions: Prime Rate South Africa

What is the lending rate in South Africa right now?

As of 2 January 2026, South Africa’s lending rate (prime lending rate) is 10.25%, according to the South African Reserve Bank’s published market rates.

What is the difference between prime rate and repo rate?

The repo rate is the rate at which the SARB lends to commercial banks. The prime rate is the rate banks use as a benchmark to lend to consumers and businesses. Prime is usually higher than repo and is often priced as repo + a margin.

How often does the prime interest rate change?

Prime interest rate changes typically occur after the SARB announces a repo rate change at a Monetary Policy Committee (MPC) meeting. If repo stays unchanged, prime usually stays unchanged as well.

How does the prime interest rate affect home loan repayments?

Most home loans are priced at prime + or – a margin, so when prime rises, repayments increase, and when prime falls, repayments decrease. This can significantly affect affordability over time.

What does “prime minus” mean?

“Prime minus” means your interest rate is below the prime interest rate — for example, prime – 1%. This is usually offered to borrowers with strong credit scores, high affordability, and larger deposits.

Can my bank change my interest rate if prime changes?

Yes. For variable-rate loans, banks adjust your interest rate when prime changes, which changes your repayment. Fixed-rate loans may not change during the fixed period, but may revert later.

Where can I check the latest prime interest rate?

The most accurate source is the SARB’s official “Current Market Rates” page, which publishes the prime lending rate and repo rate.

Disclosure:  This article is for informational purposes only and does not constitute financial advice. Loan terms, rates, and eligibility vary by lender and province. FatCat Loans is a loan comparison platform, not a lender. Always review lender agreements carefully before accepting a loan.

Understanding What Is a Personal Loan Agreement

In this blog, we will delve into the details of personal loan agreements, discussing their importance, key components, legal implications, and how to craft your own agreement. Whether you’re considering borrowing or lending money, understanding personal loan agreements can help you make informed decisions and protect your interests.

How Personal Loan Agreements Work in South Africa

Last Updated: October 2026

A personal loan agreement sets out the terms and conditions that apply when you borrow money. For a personal loan from a credit provider in South Africa, it should clearly explain important information such as the amount borrowed, interest and applicable fees, repayments and other obligations under the agreement.

Reading this information carefully before accepting a loan can help you understand how much the credit will cost, when repayments are due and what may happen if you do not meet your obligations.

This guide focuses primarily on personal loans provided by credit providers in South Africa. Private loans between friends or family may involve different legal considerations.

Key Things to Know About Personal Loan Agreements

  • A personal loan agreement records the terms and conditions applying to the credit provided.
  • Important information can include the loan amount, interest and fees, repayment schedule and other obligations.
  • Read the agreement and any pre-agreement information carefully before accepting the credit.
  • Check the total cost and make sure the repayments are affordable within your budget.
  • Keep a copy of the agreement and related documents for your records.

What Is a Personal Loan Agreement?

A personal loan agreement is the agreement between the borrower and credit provider that records the applicable terms and obligations of the credit arrangement.

Depending on the credit product, this can include the amount of credit provided, interest and fees, repayment amounts, repayment dates, the duration of the agreement and what may happen if the borrower fails to meet the agreed obligations.

Before accepting an agreement, check that you understand both the monthly repayment and the overall cost of the credit.


Key Components of a Loan Agreement

A personal loan agreement consists of several key components that define the terms and conditions of the loan. These components include:

  • Loan amount: The amount of credit being provided.
  • Interest and fees: The interest rate and applicable charges associated with the credit.
  • Repayment terms: How much you are expected to repay and when repayments are due.
  • Loan term: The period over which the credit is expected to be repaid.
  • Default provisions: Information about what may happen if you fail to meet your obligations.
  • Security, where applicable: If the credit is secured, the agreement should identify the relevant security and associated terms.

Why Your Personal Loan Agreement Matters

Your loan agreement gives you important information about the credit you are accepting and your repayment obligations. It also provides a record of the terms agreed between you and the credit provider.

Before accepting the agreement, check the loan amount, interest and fees, repayment amount, repayment dates and total cost. If anything is unclear, ask the credit provider for an explanation before proceeding.

Keep a copy of your agreement so you can refer back to the applicable terms if you have questions or experience a problem later.

Personal Loan Agreements and South African Credit Law

Personal loans provided by credit providers in South Africa may fall within the framework of the National Credit Act (NCA). The Act includes requirements relating to matters such as responsible lending, disclosure of credit costs and affordability assessments.

Before accepting credit, review the information supplied by the credit provider carefully and make sure you understand the costs and repayment obligations. You can also check whether a credit provider is registered with the National Credit Regulator (NCR).

If you are unsure about your rights or obligations under a particular agreement, consider obtaining independent legal or financial advice.

What to Check Before Accepting a Personal Loan Agreement

Before accepting a personal loan, take time to review the information provided. Important details to check include:

  • The amount you are borrowing.
  • The interest rate and applicable fees.
  • Your repayment amount and repayment dates.
  • The length of the repayment period.
  • The total cost of the credit.
  • Any consequences or permitted charges associated with missed payments.
  • Any conditions relating to early repayment or settlement.

Understanding these details can help you compare the agreement with other personal loan options before deciding whether the credit is suitable for you.

Understanding Interest, Fees and Repayment Terms

The interest rate is one part of the cost of borrowing, but it should not be considered in isolation. Review the applicable fees and other charges as well as the repayment amount and repayment period.

When comparing loan options, consider the total cost of the credit rather than focusing only on the advertised interest rate or monthly repayment.

The repayment schedule should also fit within your budget alongside your existing living expenses and financial commitments.

What Can Happen If You Miss a Repayment?

Missing a repayment can have financial consequences. Depending on the agreement and your circumstances, these may include permitted charges, collection activity and negative information being reflected in your credit history.

If you think you may struggle to make a repayment, contact the credit provider as early as possible. Ask what options may be available and make sure you understand any changes to your repayment obligations.

Conclusion

A personal loan agreement is an important document that explains the cost of your credit and your repayment obligations. Before accepting an agreement, review the loan amount, interest and fees, repayment schedule, total cost and any other important conditions.

If you don’t understand something in the agreement, ask for clarification before accepting the loan. Taking time to understand the terms can help you make a more informed borrowing decision.

Learn more about a Personal Loan Agreement in South Africa with FatCat Loans.

Frequently Asked Questions About Personal Loan Agreements

What should I check before accepting a personal loan agreement?

Check the amount being borrowed, interest and applicable fees, repayment amount, repayment dates, repayment period and total cost. You should also review any terms dealing with missed payments or early settlement.

Should I receive information about the cost of a personal loan before accepting it?

You should be given information that allows you to understand the applicable costs and repayment obligations before entering into the credit agreement. Read the documents carefully and ask the credit provider to explain anything you do not understand.

Can the terms of a personal loan agreement be changed?

Changes to a credit agreement depend on the agreement, applicable law and the circumstances involved. Do not assume that repayment terms can simply be changed on request. If you need to change your repayment arrangements, contact the credit provider and ask what options may be available.

What should I do if I cannot make a loan repayment?

Contact the credit provider as early as possible and explain the situation. Ask what options may be available and make sure you understand any effect a new arrangement could have on your repayment obligations.

What about loans between family members or friends?

Private lending arrangements can involve different considerations from consumer credit provided by a registered credit provider. A written agreement can help record what has been agreed. Read our guide to borrowing money from family in South Africa for more information.

Bad Credit Loans South Africa: A Complete Guide for 2026

Bad credit doesn’t have to stop you from accessing financial support. This 2026 guide explains how bad credit loans work in South Africa, who qualifies, what to consider before applying, and how responsible borrowing can help you regain financial stability and rebuild your credit profile.

Bad Credit Loans in South Africa: Best Options

Last Updated:  September 2026

If you have a poor credit history, getting approved for a loan in South Africa can be more difficult — but it doesn’t necessarily mean you have no options. Some lenders consider your income, existing financial commitments and ability to afford repayments alongside your credit history.

Bad credit loans can include personal loans, short-term loans and instalment loans available to applicants with weaker credit profiles. However, these loans may be more expensive, so it is important to compare interest rates, fees, repayment terms and the total cost of credit before applying.

There is no single “best” bad credit loan for everyone. The right option depends on how much you need to borrow, what you can comfortably afford to repay and the loan terms available to you. FatCat Loans is a loan comparison platform, not a lender, and approval is never guaranteed.

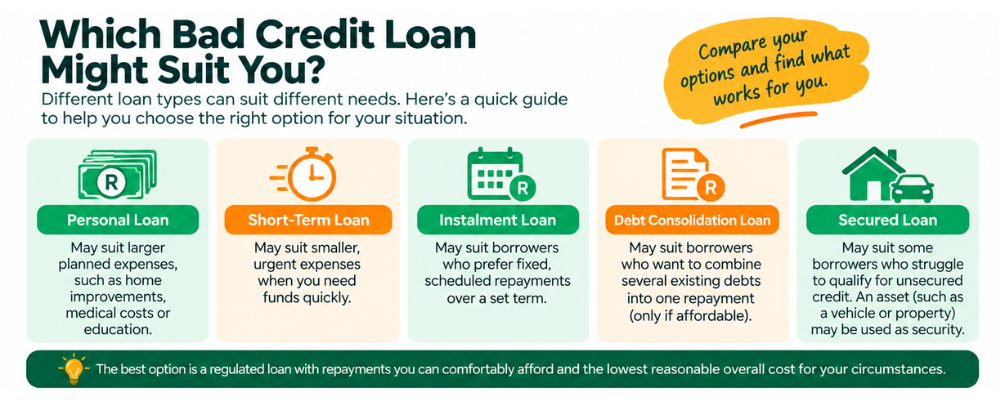
Best Loan Options for Bad Credit in South Africa

The best type of loan depends on why you need the money, how much you need to borrow and what repayments you can afford.

Loan type May be suitable for What to consider
Personal loan Larger planned expenses A weaker credit profile may result in fewer options or a higher interest rate
Short-term loan Smaller, urgent expenses The cost can be high relative to the amount borrowed
Instalment loan Borrowers wanting fixed scheduled repayments Longer repayment terms can increase the total cost
Debt consolidation loan Combining several existing debts Only worthwhile if the new repayment structure is affordable and makes financial sense
Secured loan Some borrowers who struggle to qualify for unsecured credit An asset used as security may be at risk if you cannot repay

The best option is generally a regulated loan with repayments you can comfortably afford and the lowest reasonable overall cost for your circumstances. Don’t choose a loan simply because it offers the fastest application or the lowest monthly repayment.

Bad credit loan options in South Africa

What Is a Bad Credit Loan?

“Bad credit loan” is a general term for loans that may be available to people with a weaker or limited credit history. It isn’t a separate regulated category of loan in South Africa.

If you’re comparing borrowing options specifically for a weaker credit profile, you can learn more about bad credit loans in South Africa, including how eligibility, affordability checks and repayments work.

There is no universal credit score that automatically counts as “bad credit”. Lenders use their own criteria and may consider your credit history alongside your income, existing debts, expenses and ability to afford repayments.

Poor credit doesn’t automatically mean you’ll be declined, but it may reduce your available options or affect the rate and terms you’re offered.

Can You Get a Loan With Bad Credit in South Africa?

It may be possible to qualify for a loan with bad credit, but approval should never be guaranteed.

South African credit providers are required to assess whether a borrower can afford the proposed credit. This means your income, expenses, existing financial obligations and credit information may all be considered before a lender decides whether to approve an application.

Be cautious of advertisements promising “guaranteed approval”, “no credit checks” or loans regardless of your financial circumstances. A legitimate lender should assess whether the loan is affordable before granting credit.

How We Assess Loan Options

When discussing loan options, FatCat Loans considers factors such as lender regulation, borrowing costs, fees, repayment terms, eligibility requirements, application process and affordability.

We don’t consider a loan “best” simply because it offers fast decisions or accepts applications from people with weaker credit histories. The overall cost and your ability to comfortably repay the loan matter too.

Where to Compare Bad Credit Loans Online

FatCat Loans is a comparison platform, not a lender. You can submit your details to explore loan options from participating providers that may suit your circumstances. Any loan remains subject to the lender’s eligibility requirements, affordability checks and final approval.

Where a soft credit check is used during the comparison process, this does not affect your credit score. A lender may carry out additional checks during its own application process.

How Does Bad Credit Affect Loan Applications?

Missed or late payments, defaults and high levels of existing debt can affect your credit profile. A weaker credit history may reduce the number of lenders willing to offer you credit or affect the amount, interest rate and terms you’re offered.

Before applying, consider checking your credit report for incorrect or outdated information so you understand what lenders may see when assessing your application.

Get your free credit report

How to Compare Bad Credit Loan Options

When comparing loans, don’t focus only on whether a lender is willing to approve your application. Consider what the loan will actually cost and whether the repayments fit your budget.

Interest Rates and Fees

A weaker credit profile may result in a higher interest rate, but rates and costs vary between lenders and loan types. Check the interest rate as well as any initiation fee, monthly service fee and credit-life insurance that may apply.

South African credit costs are regulated under the National Credit Act, with maximum interest rates and certain fees depending on the type of credit agreement.

Total Cost of Credit

The monthly instalment doesn’t tell you the full cost of a loan. Before accepting an offer, check the lender’s quotation for the total amount you will repay over the full term.

A loan with a lower monthly repayment can sometimes cost more overall if it is repaid over a longer period.

Repayment Term

A shorter term generally means larger monthly repayments but less time for interest and recurring fees to accumulate. A longer term can make the monthly repayment smaller, but may increase the overall cost.

Choose a repayment term based on what you can comfortably afford — not simply the lowest monthly instalment available.

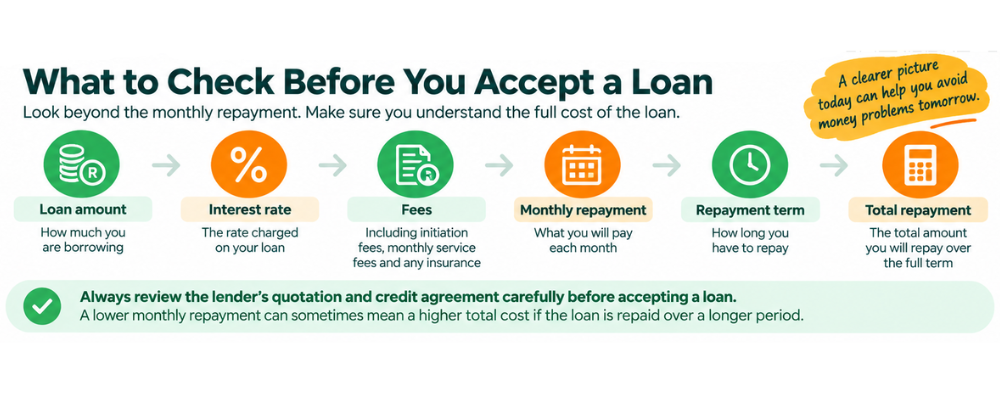
Before You Accept a Loan

Check the lender’s quotation and make sure you understand:

  • the amount you’re borrowing;
  • the interest rate;
  • the initiation fee;
  • any monthly service fee;
  • any credit-life insurance or other permitted charges;
  • the monthly repayment;
  • the repayment period; and
  • the total amount you will repay.

If two lenders offer the same loan amount, comparing the total repayment can give you a much clearer picture than comparing the monthly instalment alone.

What to check before accepting a loan

Step-by-Step: How to Apply for the Best Bad Credit Loans South Africa

Step Action Description / Tips
1. Research Lenders Compare regulated lenders and suitable loan options. Compare loan types, eligibility requirements and costs before applying.
2. Gather Documents Prepare ID, proof of income, and bank statements. Lenders require these to verify affordability.
3. Complete the Application Fill in details accurately and honestly. Incorrect information can cause delays.
4. Submit the Application Upload your documents and send. Ensure everything is attached before submitting.
5. Await Approval Wait for the lender’s decision. Decision times vary. Some lenders may provide an initial decision quickly, but additional checks or documents can delay final approval.
6. Review Loan Terms Check interest rate, fees, and repayment schedule. Make sure it’s manageable before signing.
7. Accept and Receive Funds Accept the loan offer and receive the funds. Only accept the loan once you understand the total cost and are comfortable with the repayment schedule.

Submitting an application does not guarantee approval. The lender will make the final decision based on its lending criteria and affordability assessment.

How to Improve Your Chances of Loan Approval

No legitimate lender can guarantee approval, but you can prepare before applying:

  • Check your credit report for incorrect or outdated information.
  • Borrow only what you need and consider whether the repayment is comfortably affordable.
  • Provide accurate information about your income, expenses and existing debts.
  • Compare before applying rather than submitting multiple full applications simply to see who approves you.
  • Consider your existing debt. If another repayment would make it difficult to cover essential living costs, additional borrowing may not be appropriate.

When a Bad Credit Loan May Not Be the Right Choice

Being eligible for a loan doesn’t necessarily mean that borrowing is the best option.

Think carefully before taking on additional credit if:

  • you’re already struggling to make existing debt repayments;
  • you would need to borrow again to repay the new loan;
  • the repayment would leave you short of money for food, housing, transport or other essential expenses;
  • you’re using new credit simply to keep up with other high-cost debts; or
  • you’re currently under debt review.

If you’re struggling with existing debt, consider speaking to an NCR-registered debt counsellor about your options before taking on more credit.

Borrowing should solve a manageable financial need rather than create a cycle where you need new credit to repay old credit.

How to Avoid Bad Credit Loan Scams in South Africa

People searching for loans after being declined elsewhere can be particularly vulnerable to scams. Before dealing with a lender:

  • Check its NCR registration. Verify unfamiliar credit providers through the National Credit Regulator.
  • Be suspicious of guaranteed approval. Legitimate lenders should assess your application and affordability.
  • Don’t pay suspicious upfront fees. Be cautious if you’re asked to transfer money before loan funds can supposedly be released.
  • Protect your banking details. Never provide passwords, PINs or one-time passwords to someone claiming they need them to approve a loan.
  • Read the credit agreement. Check the interest, fees, repayment schedule and total amount repayable before accepting.

Remember that a professional-looking or secure website does not prove that a lender is legitimate, as scammers may impersonate genuine businesses.

Compare loan options with FatCat Loans

FAQs About Bad Credit Loans in South Africa

Can I get a loan with bad credit in South Africa?

Possibly. Having a poor credit history doesn’t automatically prevent you from qualifying for a loan. Lenders may consider your credit history alongside your income, existing financial commitments and ability to afford the repayments. Approval is not guaranteed.

What credit score do I need to get a loan?

There is no single credit score that guarantees loan approval in South Africa. Credit bureaus use different scoring systems, and lenders have their own eligibility criteria and affordability assessments.

Which type of loan is best if I have bad credit?

It depends on your circumstances. Personal loans may suit larger planned expenses, while short-term or instalment loans may be available for smaller borrowing needs. Compare the total cost, repayment term and affordability rather than choosing a loan based only on speed or the monthly repayment.

Are bad credit loans more expensive?

They can be. A weaker credit profile may result in a higher interest rate or fewer available options. The cost also depends on the type of credit, lender, amount borrowed, repayment term and applicable fees.

Can I get a bad credit loan without a credit check?

Be cautious of lenders advertising guaranteed loans with “no credit checks”. Legitimate credit providers should assess whether credit is affordable before approving an application.

How can I tell if an online lender is legitimate?

Check the lender’s details and NCR registration, read the loan agreement carefully and be suspicious of guaranteed approval or requests for suspicious upfront payments. You can verify registered credit providers through the National Credit Regulator.

Final Thoughts

Having bad credit can make borrowing more difficult, but it doesn’t necessarily mean that every lender will decline your application. The options available will depend on your individual circumstances, affordability and the lender’s criteria.

If you decide that borrowing is appropriate, compare more than the monthly repayment. Look at the interest rate, fees, repayment period and total amount repayable, and only accept credit that you can comfortably afford.

FatCat Loans can help you explore loan options from participating providers. FatCat Loans is a comparison platform, not a lender, and cannot guarantee that you will be approved.

Sources & review: This guide has been reviewed using consumer credit information published by the National Credit Regulator (NCR). Credit regulations, lender criteria and borrowing costs can change, so always check current information before applying.

Disclosure: This article is for general informational purposes only and does not constitute financial advice. Loan availability, rates, fees, terms and eligibility vary by lender and applicant. FatCat Loans is a loan comparison platform, not a lender, and does not make credit decisions or guarantee approval. Always review the lender’s quotation and credit agreement carefully before accepting credit.

How To Secure Long Term Loans with Poor Credit in South Africa

Securing long-term loans with poor credit can be challenging, but it’s not impossible. In South Africa, there are options available for individuals with poor credit to obtain the funds they need for various purposes. In this blog, we will explore how to secure long-term loans with poor credit in South Africa.

How To Secure Long Term Loans with Poor Credit in South Africa

Last Updated:  October 2026

Having a poor credit history can make it more difficult to qualify for a long-term loan in South Africa, but a low credit score does not automatically mean that every application will be declined.

Credit providers use their own lending criteria and may consider your credit history alongside your income, expenses, existing debts and ability to afford the repayments. The amount, interest rate and repayment period available will depend on the provider and your individual financial circumstances.

If you have a weaker credit profile, understanding what lenders assess and preparing your finances before applying can help you make a more informed borrowing decision.

For more information about borrowing with a weaker credit profile, see our guide to bad credit loans in South Africa.

Long-Term Loans with Poor Credit in South Africa: Key Points

  • Understanding your credit score and its impact on loan eligibility is important before applying for any financial product.
  • Assessing your financial situation and improving your credit score ahead of time can increase your chances of loan approval.
  • Understanding interest rates and fees is crucial to maintain your financial health even when taking on a loan.

Understanding Poor Credit and Its Impact on Loan Eligibility

Before diving into the details of securing long-term loans with poor credit in South Africa, it is important to understand what poor credit means and how it can impact your loan eligibility. Your credit score is a numerical representation of your creditworthiness. It takes into account factors such as your payment history, amount of debt, length of credit history, and new credit applications.

In South Africa, credit bureaus use information reported by credit providers and other relevant information to calculate credit scores and maintain credit reports. Scoring models and ranges can differ between credit bureaus, so there is no single score scale used by every lender.

Having a bad credit record or a poor credit history can make it more difficult to secure loans, as lenders may view you as a higher risk borrower. This can result in higher interest rates, stricter terms and conditions, or even outright loan rejections.

Essential Steps Before Applying for Long Term Loans

Before applying, there are a few essential steps you should take to increase your chances of approval.

Step 1: Assessing Your Financial Situation

Assessing your financial situation is a crucial step before applying for a long-term loan with poor credit in South Africa. Consider your personal circumstances, including your income, expenses, and existing debts. This will help you determine if taking on a long-term loan is the right financial solution for you.

Calculate how much you can afford to pay each month towards loan repayments, ensuring that it fits within your budget. It is important to be realistic and not overextend yourself financially. By carefully assessing your financial situation, you can make an informed decision about whether a long-term loan is the right choice for you and avoid any potential financial strain in the future.

Step 2: Improving Your Credit Score

If your loan is not urgent, it may be worth taking a period of time to work on your credit score. A few months of effort could help you increase your score and ultimately get you a better loan later on. During a period of time, build your credit score by doing the following:

  • Make all your payments on time, including credit card payments, loan instalments, and utility bills.
  • Reduce your overall debt by paying off any outstanding loans or credit card balances.
  • Check your credit report regularly for any errors or discrepancies and contact the credit bureau to rectify them.

By following these tips and practicing responsible financial habits, you can gradually improve your credit score and increase your chances of securing a long-term loan with better terms.

Secured vs. Unsecured Loans: What’s Best for You?

When considering long-term loans with poor credit in South Africa, it is important to understand the difference between secured and unsecured loans.

Secured loans require an asset to be provided as security for the credit agreement. Depending on the type of agreement, failing to meet the repayments could put the secured asset at risk.

Unsecured loans do not normally require an asset as collateral. Interest rates, fees, loan amounts and repayment periods vary between credit providers and applicants.

The choice between secured and unsecured loans depends on your personal circumstances and willingness to provide collateral. If you have valuable assets and are confident in your ability to repay the loan, a secured loan may offer more favourable terms. However, if you don’t want to risk losing your assets or don’t have collateral to offer, an unsecured loan may be a better option.

Apply for long term loans up to R250,000

How to Apply for Long Term Loans with Poor Credit South Africa

Applying for long-term loans with poor credit in South Africa has become easier with online application processes. Your first step should always be to evaluate how much you need and start preparing your realistic repayment plan. Yes, do this even before applying!

Once you know approximately how much you need and what repayment you could reasonably afford, you can compare available loan options. Look at the interest rate, fees, repayment period, monthly repayment and total cost rather than choosing an offer based only on the advertised rate.

Documents Needed for Loan Approval

To streamline the application process, you can gather all your documents. The following will most likely be needed to complete your application:

  • Proof of identity: This can be a valid ID document or passport.
  • Proof of income: Lenders usually require proof of income to assess your ability to repay the loan. This can include recent payslips or bank statements showing regular income.
  • Bank account details: You will need to provide your bank account details for the loan funds to be deposited and for repayment purposes.
  • Credit check: Lenders will often conduct a credit check to assess your creditworthiness and determine the terms of the loan.

How to Prepare Before Applying

There is no strategy that can guarantee approval for a long-term loan. However, you can prepare before submitting an application by:

  • Checking your credit report for information you believe is incorrect.
  • Reviewing your income, expenses and existing debt repayments.
  • Working out how much you could realistically afford to repay each month.
  • Preparing the identification, income and banking documents requested by the credit provider.
  • Avoiding borrowing more than you genuinely need.

Approval ultimately depends on the credit provider’s lending criteria, affordability assessment and your individual financial circumstances.

Understanding Interest Rates and Fees

Understanding interest rates and fees is crucial when applying for a long-term loan with poor credit in South Africa.

Poor credit can have a significant impact on the interest rates offered by lenders when applying for a long-term loan in South Africa. It is important to be aware of how poor credit affects interest rates and to carefully consider the affordability of the loan before proceeding.

Evaluate the rate, additional fees, and penalties associated with your loan. Compare lenders to find the most competitive rates, and be realistic about your ability to repay the loan. Consider the impact of the rate, for example, if you ended up paying your loan back later than expected. This consideration can ensure you are ready for all possibilities and fully understand the risks.

Avoiding Common Pitfalls When Borrowing with Poor Credit

When borrowing with poor credit in South Africa, it is crucial to avoid common pitfalls that can further worsen your financial situation. One common pitfall is dealing with loan sharks or engaging in predatory lending practices. These lenders often charge exorbitant interest rates and use aggressive tactics to collect payments. It is important to research and choose reputable lenders who offer fair terms and transparent practices.

This is why we highly encourage you to:

#1: Compare lenders
#2: Understand the fees you are dealing with
#3: Prepare a repayment plan ahead of time.

Practice responsible borrowing by following these 3 tips, and by only borrowing what you can afford to repay and making timely repayments.

Frequently Asked Questions

Can I get a long-term loan with poor credit?

Possibly. A poor credit history can make borrowing more difficult, but it does not automatically mean that every application will be declined. Credit providers consider their own lending criteria as well as factors such as income, expenses, existing debts, credit information and affordability.

What is the minimum credit score to get a loan in South Africa?

There is no single minimum credit score used by every South African credit provider. Credit bureaus and lenders may use different scoring models and lending criteria. Your credit score can influence an application, but lenders may also consider your income, expenses, existing debts and ability to afford the repayments.

Can I get a loan with a very low credit score?

A very low credit score may make it more difficult to qualify for credit, but a score alone does not determine the outcome of every application. Approval depends on the credit provider’s criteria and assessment of your overall financial circumstances.

Are long-term loans cheaper than short-term loans?

Not necessarily. A longer repayment period can reduce the monthly repayment, but paying interest and fees over a longer period may increase the total amount repaid. Compare the total cost of credit as well as the monthly instalment before accepting an offer.

What should I compare before accepting a long-term loan?

Compare the interest rate, fees, monthly repayment, repayment period and total amount repayable. Make sure the repayments remain affordable alongside your existing financial commitments.

What To Do If I Need Money Urgently South Africa: Your Guide

When faced with an urgent need for money in South Africa, it is important to know where to turn for help. In this guide, we will explore the options available to those in need of urgent financial assistance in South Africa.

What To Do If I Need Money Urgently South Africa

Last Updated: October 2026

If you need money urgently in South Africa, the best option depends on why you need the money, how much you need and whether you can afford to repay borrowed funds. An unexpected medical bill, car repair or other emergency can put pressure on your budget, but taking out credit is only one possible solution. This guide looks at borrowing and non-credit options to consider when you need money urgently.

Key Things to Know If You Need Money Urgently

  • Consider whether you can cover the expense without borrowing before taking on new debt.
  • If you do need credit, compare the interest, fees, repayment period and total cost before accepting an offer.
  • Approval and payout times vary between credit providers and are not guaranteed.
  • Non-credit options can include selling unused items, asking family for temporary help or checking whether you qualify for financial assistance.
  • Only borrow an amount you can reasonably afford to repay alongside your existing expenses and financial commitments.
  • Building an emergency fund can help reduce your reliance on credit when unexpected expenses arise.

You can also explore government social benefits and assistance if you may qualify for support.

Understanding What To Do When You Need Urgent Money

Financial emergencies can happen to anyone at any time. Medical bills, car repairs, and unexpected expenses can quickly drain your savings and leave you in a difficult financial situation. The reality of these emergencies is that they often come without warning and require immediate attention. It is important to be prepared for such situations and have a plan in place to handle them.

When an unexpected expense occurs, first consider whether it can be delayed, reduced or covered without taking on new debt. Depending on your circumstances, options might include using savings, selling unused items, asking family for temporary help or considering short-term loan options. If you consider borrowing, check that the repayments are affordable and review the total cost before accepting an offer.

Considering a Loan When You Need Money Urgently

If you decide that borrowing is appropriate, compare available credit options carefully. Approval and payout times vary between credit providers, so you should not rely on a loan being available immediately. Compare the interest rate, fees, repayment period and total cost, and make sure the repayments fit within your budget.

You can compare loan options before deciding whether to apply.

Compare loan options with FatCat Loans

How Fast Loan Applications Work

Some credit providers allow you to complete a loan application online. You may be asked to provide personal, income, banking and other financial information so the provider can assess your application and affordability.

If an application is approved, review the loan amount, interest, fees, repayment period and other terms before accepting the offer. Approval and payout times vary depending on the provider, verification requirements and banking processes.

What to Consider Before Taking an Urgent Loan

Borrowing may help cover an expense when other options are unavailable, but it also creates a repayment obligation. Before applying, consider:

  • Whether the expense genuinely needs to be paid immediately.
  • Whether you have a non-credit alternative available.
  • The interest rate and applicable fees.
  • The monthly repayment and repayment period.
  • The total cost of the credit.
  • Whether you can afford the repayments alongside your existing expenses and debts.

If you’re considering an online loan, you can learn more about how online loans work before applying.

Alternative Quick Money Solutions

Before borrowing, consider whether another option could help you cover the urgent expense without taking on new debt. Depending on your circumstances, this could include selling unused items or asking friends or family for temporary help.

Selling Assets for Quick Cash

When faced with an urgent need for money, selling assets can be a viable solution. Whether it’s selling unused items or liquidating valuable possessions, selling assets can provide extra cash when needed. This can be particularly helpful during a financial emergency when immediate funds are required.

It is important to carefully consider the value of the assets being sold and ensure that the selling process is done safely and securely. Selling assets can provide a temporary solution to urgent financial needs and help bridge the gap between your current situation and the need for immediate funds. With any financial decision, it’s important not to act too quickly or impulsively. Take the time to evaluate what you’re selling, the potential consequences, and the pros and cons overall.

Selling things like clothes or jewellery could be a helpful solution, but it’s important to ensure you won’t regret it later. Selling larger possessions like a home or car should involve a longer consideration period, and it may be a good idea to involve a second opinion from someone you trust.

Borrowing from Friends and Family: Tips and Cautions

Borrowing from friends and family can be another option to consider when in need of urgent money. However, it is important to approach this option with caution and establish clear repayment terms to avoid potential strain on relationships.

When borrowing from friends and family, it is important to treat it as a formal loan and not take advantage of the relationship. Clear communication and trust are key to ensuring that the borrowing process goes smoothly and does not create any unnecessary tension.

Borrowing from friends and family can provide a temporary solution to urgent financial needs, but it is important to handle this option responsibly.

How to Choose a Reliable Credit Provider

If you decide to apply for credit, check the provider carefully before submitting personal or banking information. Verify that the credit provider is registered with the National Credit Regulator (NCR) and confirm that the registration details match the provider you are dealing with.

Carefully review the loan amount, interest, fees, repayment period and total cost before accepting an offer. Be cautious of anyone promising guaranteed approval, requesting suspicious upfront payments or asking for sensitive information such as your banking PIN or password.

Finally, carefully review the terms and conditions of the loan, including the loan amount, repayment terms, and any fees or charges associated with the loan. By doing your due diligence, you can choose a reliable lender before submitting your online loan application and avoid falling victim to fraudulent or unfair lending practices.

Starting an Emergency Fund: Planning Ahead

One of the best ways to prepare for urgent financial needs is to plan ahead and build an emergency fund. An emergency fund is a savings account specifically set aside for unexpected expenses. By regularly contributing to an emergency fund, you can create a financial safety net that can be accessed during times of urgent need. Building an emergency fund requires discipline and commitment, but it can provide peace of mind and financial stability during unexpected expenses. Once you deal with your urgent situation, it’s a good idea to start considering how you can improve in the future. An emergency fund is one great way to avoid finding yourself in such a situation again!

Starting an emergency fund is a proactive step towards financial stability. To begin, open a separate savings account specifically designated for your emergency fund. Set a realistic savings goal and commit to regularly contributing to your emergency fund. This can be done by automatically transferring a portion of your income into the account each month. It is important to treat the emergency fund as a non-negotiable expense, just like any other bill or financial obligation. By prioritizing your emergency fund and consistently contributing to it, you can build a financial safety net to help you navigate unexpected expenses.

Conclusion

If you need money urgently, consider both borrowing and non-credit options before deciding what to do. Using savings, selling unused items, asking family for temporary help or checking whether financial assistance is available may help you avoid taking on additional debt.

If you decide to borrow, compare the costs and repayment terms carefully and only accept credit you can reasonably afford to repay. Once the immediate situation has passed, building an emergency fund can help you prepare for unexpected expenses in the future.

Frequently Asked Questions About Needing Money Urgently

What can I do if I need money urgently in South Africa?

Consider whether you can use savings, reduce or delay the expense, sell unused items, ask family for temporary help or access financial assistance before taking on new debt. If you decide to borrow, compare the costs and make sure the repayments are affordable.

Can I get a loan quickly in South Africa?

Some credit providers offer online application processes, but approval and payout times vary. Timing can depend on affordability checks, document verification, the time of application and banking processes. No legitimate provider should guarantee approval without assessing your application.

How can I find a legitimate lender?

Check that the credit provider is registered with the National Credit Regulator (NCR) and verify its registration details. Be cautious of guaranteed approval claims, suspicious upfront payments and requests for sensitive banking information.

Can I compare quick loan options online?

Yes. You can compare loan options and review factors such as interest, fees, repayment periods and eligibility requirements before deciding whether to apply.

How can I avoid relying on loans for future emergencies?

Building an emergency fund can help you prepare for unexpected expenses. Even small regular contributions can gradually create a financial buffer that may reduce the need to borrow when an unexpected cost arises.

How To Get A R10,000 Loan With Bad Credit

Find out how, where, and how fast you can get a R10,000 loan with bad credit. Apply today & get approved. Read more.

How to Improve Your Chances of Getting a R10,000 Loan with Bad Credit

Last Updated:  October 2026

If you have bad credit and need to borrow R10,000, there are steps you can take before applying that may help you present a stronger application. There is no way to guarantee approval, but checking your credit information, reviewing your budget and preparing the documents a lender may require can help you avoid preventable problems.

This guide focuses on what you can do before applying, including checking your credit information, understanding affordability, preparing your bank statements and avoiding common application mistakes.

If you’re looking for information about the loan itself rather than preparing an application, read our guide to R10,000 personal loans with bad credit.

Important: FatCat Loans is a loan comparison platform, not a lender. We cannot guarantee that an application will be approved. Credit providers use their own lending criteria and are required to assess affordability before granting credit.

Apply button for bad credit loans up to R350,000

Before You Apply: R10,000 Loan Checklist

  • Check your credit report for errors or outdated information.
  • Review your income, essential expenses and existing debt repayments.
  • Make sure the proposed repayment would fit your budget.
  • Prepare recent proof of income and bank statements if required.
  • Check whether you are currently under debt review.
  • Avoid submitting multiple applications simply to see which lender approves first.
  • Make sure all information on your application is complete and accurate.

What Do Lenders Consider When You Have Bad Credit?

Having bad credit does not automatically mean that every credit provider will decline an application. However, your credit history can form part of the lender’s assessment and approval is never guaranteed.

Depending on the credit provider and type of application, factors considered may include:

  • Net monthly income
  • Monthly living expenses
  • Existing credit repayments
  • Debt-to-income ratio
  • Recent missed payments and defaults
  • Employment stability (or consistent self-employed income)
  • Information shown in recent bank statements where these are requested

If you’re unsure what your score means, read: Credit Score Meaning in South Africa.

Affordability Assessments and the National Credit Act (NCA)

In South Africa, registered credit providers must comply with the National Credit Act (NCA) and applicable affordability assessment requirements before granting credit.

Affordability checks typically consider:

  • Verified income
  • Normal monthly expenses
  • Existing credit commitments
  • Disposable income after expenses

If someone offers “guaranteed approval” without checking affordability, treat it as a red flag.

Understanding “Bad Credit” vs “Blacklisted” vs “Debt Review”

Bad Credit

“Bad credit” is an informal term generally used to describe a weaker credit profile. This may be associated with factors such as missed payments, defaults, high credit utilisation or other information recorded in your credit history.

Can You Get a R10,000 Loan If You Are “Blacklisted”?

“Blacklisted” is not a formal lending status in South Africa. The term is commonly used to describe someone with negative information on their credit record, such as defaults or judgments. Credit providers can consider credit information alongside affordability and other lending criteria when assessing an application.

See also: Blacklisted Loans South Africa.

Under Debt Review

If you are under active debt review, access to further credit is generally restricted. If you’re in this situation, read: Under Debt Review and Need a Loan Urgently.

Minimum Requirements for a R10,000 Loan

Exact requirements vary between credit providers, but you may be asked for:

  • A valid South African ID
  • An active bank account
  • Proof of stable income (salary slips or consistent deposits)
  • Recent bank statements
  • Evidence that you meet the credit provider’s income and affordability requirements

If you’re self-employed, you may need extra proof of income. If you want to understand how bank statements affect approvals, see: How to Get a Loan with Bank Statement Only.

Check Your Credit Information Before Applying

Before applying for a R10,000 loan, consider checking your credit report so you can see the information recorded about you and identify any information you believe may be incorrect.

A credit provider may access credit bureau information when assessing a credit application. Credit enquiries and application processes can differ between providers, so check how your information will be used before submitting an application.

If you find incorrect information on your credit report, follow the relevant credit bureau’s dispute process rather than repeatedly applying for new credit.

If you’re unsure what your credit information means, read our guide to credit scores in South Africa.

How to Improve Your Chances Before Applying for R10,000

  1. Check your credit report. Look for incorrect or outdated information and follow the bureau’s dispute process if something appears wrong.
  2. Review your current budget. Work out your income, essential living expenses and existing debt repayments before deciding whether another repayment is affordable.
  3. Prepare the required documents. Having your ID, proof of income and recent bank statements ready can help avoid unnecessary delays if the lender requests them.
  4. Provide accurate information. Make sure the income, expenses and debt information on your application is complete and correct.
  5. Avoid unnecessary multiple applications. Applying repeatedly does not guarantee that one lender will approve you and may result in multiple credit enquiries.
  6. Consider whether R10,000 is affordable. Don’t choose a loan amount simply because it is available. Consider the repayment and total borrowing cost.
  7. Compare suitable options carefully. If you receive an offer, review the interest rate, fees, repayment period and total amount repayable before accepting it.

If you’re working on improving your profile, see: How to Build Credit in South Africa and How to Check and Improve Your Credit Score.

Why a R10,000 Loan Application May Be Declined

Decline Reason Why It Matters How to Improve
Too Many Recent Applications Multiple applications may result in several credit enquiries and can form part of a lender’s assessment. Avoid unnecessary repeat applications and review why your previous application was unsuccessful before applying again.
Unpaid Debit Orders Recent account activity may be considered where bank statements form part of the assessment. Review your budget and address missed financial commitments where possible before taking on additional credit.
High Debt-to-Income Ratio Existing debt repayments can reduce the amount of disposable income available for another loan. Review your existing commitments and consider whether taking on additional credit is affordable.
Irregular Income It may be more difficult for a lender to assess whether repayments are sustainable. Provide the income documentation requested by the lender and make sure the information is accurate.
Active Debt Review Access to further credit is generally restricted while you are under debt review. Speak to your debt counsellor if you are unsure about your current debt-review status.

If you’re facing repeat declines, read: What to Do If Your Loan Has Been Declined.

How to Borrow Responsibly

Before you accept a R10,000 loan, make sure the repayment fits your budget even if something unexpected happens. A simple plan helps:

  • Calculate repayments using the Loan Calculator
  • Choose a term that keeps repayments comfortable
  • Prioritise essential spending over non-essentials
  • Avoid borrowing again before your budget stabilises

If you’re managing multiple debts, learn more about Debt Consolidation and Consolidation Loans.

How to Stay Safe and Avoid Loan Scams

  • Never pay upfront “approval” fees
  • Avoid “guaranteed approval” claims
  • Check that the credit provider is registered with the National Credit Regulator (NCR)
  • Read the full contract (fees, APR, repayment schedule)

Upfront-fee warning: Be cautious if someone asks you to pay an “unlock”, “release” or similar fee before providing a promised loan. Verify the credit provider and the reason for any requested payment before sending money.

Read: Fraud Alert and How to Verify NCR Registration in South Africa.

Frequently Asked Questions About Applying for R10,000 With Bad Credit

Can I improve my chances of getting a R10,000 loan with bad credit?

You cannot guarantee approval, but you can prepare before applying. Check your credit information, review your budget, provide accurate income and expense information, prepare any documents the lender requires and avoid unnecessary repeat applications.

Should I check my credit report before applying?

It can be useful. Checking your credit report allows you to see information recorded about you and identify information you believe may be incorrect before submitting a new credit application.

Will bad credit automatically mean my application is declined?

No. Credit providers use their own lending criteria and may consider your credit information alongside income, existing debts, expenses and affordability. However, approval is never guaranteed.

Should I apply to several lenders at the same time?

Submitting multiple applications does not guarantee approval and may result in multiple credit enquiries. It can be better to understand the eligibility requirements and compare suitable options before deciding whether to submit an application.

What documents might I need for a R10,000 loan application?

Requirements vary between credit providers, but you may be asked for identification, proof of income, recent bank statements and information about your expenses and existing financial commitments.

Can I apply for a R10,000 loan while under debt review?

Access to further credit is generally restricted while you are under debt review. Speak to your debt counsellor if you are unsure about your current status.

Before You Apply for a R10,000 Loan With Bad Credit

Bad credit does not automatically mean that every R10,000 loan application will be declined, but there is no way to guarantee approval.

Before applying, check your credit information, review your income and existing financial commitments, make sure another repayment is affordable and prepare the documents a credit provider may require.

If you are ready to compare borrowing options, you can learn more about bad credit loans in South Africa or read our guide to R10,000 personal loans with bad credit.

Compare bad credit loans options button

Helpful next reads:

What To Do If Your Loan Has Been Declined in South Africa (2026 Guide)

Learn why loan applications are declined in South Africa and discover practical steps to improve your chances of approval before applying again.

What To Do If Your Loan Has Been Declined in South Africa (2026 Guide)

Last Updated: July 2026

Getting told your loan application has been declined can be frustrating, especially if you were relying on the money for an important expense.

The good news is that a declined application doesn’t necessarily mean you won’t qualify for credit in the future. In many cases, understanding why your loan was declined can help you improve your chances the next time you apply.

South African lenders must follow the National Credit Act (NCA), which means they are required to assess whether a loan is affordable before approving it. They will also consider factors such as your credit history, income, existing debt, employment stability and banking behaviour.

Every lender has its own approval criteria, so being declined by one lender does not necessarily mean you will be declined by another.

In this guide, we’ll explain the most common reasons loans are declined in South Africa, what you should do next and practical steps you can take to improve your chances of approval.

Person reviewing a declined loan application in South Africa

At a Glance

✓ Loan declines are common and don’t always mean you have bad credit.

✓ Affordability is one of the biggest reasons lenders reject applications.

✓ Applying to multiple lenders in a short period may reduce your chances of approval.

✓ Understanding your credit profile can help you identify issues before applying again.

✓ Improving your financial profile may increase your chances of approval.

12 Common Reasons Your Loan Was Declined

The most common reasons a loan application is declined in South Africa include affordability concerns, poor credit history, existing debt, missing documentation, lender-specific criteria and difficulties verifying your income. Understanding the reason for the decline is the first step towards improving your chances of approval.

Reason Can You Fix It? Should You Apply Again Immediately?
Low affordability ✅ Yes ❌ Improve finances first
Poor credit score ✅ Usually ⏳ Wait and improve your score
Too much existing debt ✅ Yes ⏳ Reduce debt first
Missing documents ✅ Yes ✅ Once corrected
Incorrect information ✅ Yes ✅ Once corrected
Debt review ⚠️ Usually no ❌ Seek professional advice
Income couldn’t be verified ✅ Yes ✅ After providing proof
Multiple recent applications ✅ Yes ⏳ Wait a few weeks

Common reasons South African loan applications are declined

So you’ve been turned down for a personal loan. Why?

One of the things that makes rejection difficult is that you aren’t always informed why the lender denied your loan.

There are several possible reasons for rejection, and while it may appear to be concerning, there is nothing to be concerned about in many cases. First, we’ll go over some of the most common reasons for personal loan rejection in this section.

Your Credit Score May Be Too Low

Your credit score is a simple “grade” based on your track record of repaying loans, credit cards, and other forms of borrowing on time.

Most lenders analyse your credit history when considering whether or not to give you money. They prefer people who can manage and return their debts without late payments, defaults, judgments or other negative listings on your credit profile.

Many lenders will reject applicants with low credit scores. However, you may still be eligible for a loan elsewhere (don’t reapply straight away – more on that later).

Alternatively, work on boosting your credit score to increase your chances of getting credit in the future. If your credit history is preventing you from qualifying for traditional finance, you may also want to explore our guide to bad credit loans in South Africa, which explains the options available to borrowers with less-than-perfect credit.

If you don’t have “good” or “excellent” credit, you may learn more about your alternatives in our guide to building your credit score.

You may not meet the lender’s requirements

A good credit score is unlikely to be the sole factor lenders consider. While many lenders will grant credit to those over 18, some will have a larger limit. In that situation, you can either wait or switch providers.

Different Lenders Have Different Lending Criteria

Every lender has its own lending policy and risk appetite. Some specialise in borrowers with strong credit histories, while others are willing to consider applicants with less-than-perfect credit. This means being declined by one lender doesn’t necessarily mean you’ll be declined by another.

As a result, even the “best” borrowers will be turned down from time to time.

Affordability

A lender needs to know that a borrower can afford to repay a loan. On the one hand, it can look at the borrower’s credit history, but even the greatest intentions won’t help if the repayments are too large.

As a result, responsible lenders will only offer you loans they believe you can readily return.

If you’re worried about affordability (for example, a low income), the most straightforward approach is to ask for a smaller loan amount. Using our Loan Calculator can help you estimate repayments before submitting another application.

You Applied for More Than You Could Afford

Sometimes borrowers simply request more money than their financial circumstances support.

Lenders assess how much disposable income you have available after paying your essential monthly expenses and existing debt. If the requested loan would place too much pressure on your budget, your application may be declined.

Before applying again, consider whether a smaller loan amount would better match your affordability. If you’re unsure what lenders may realistically approve, read our guide on how much you can borrow in South Africa, which explains how income, expenses and affordability affect the amount you may qualify for.

Your Income Could Not Be Verified

Lenders need confidence that your income is stable.

If your payslips, bank statements or proof of income don’t match the information on your application, the lender may reject the application until additional verification is provided.

This is particularly common for:

  • Self-employed applicants
  • Freelancers
  • Commission earners
  • Seasonal workers

Banking Behaviour Concerns

Your banking behaviour can play an important role in a lender’s affordability assessment. Many lenders review recent bank statements to better understand how you manage your finances and whether you can comfortably afford additional credit.

They may look for:

  • Returned debit orders
  • Gambling transactions
  • Irregular salary payments
  • Frequent overdraft use
  • Signs of financial distress

Improving your banking habits before applying again may strengthen your application and improve your chances of approval.

You’re Already Under Debt Review

Borrowers under debt review generally cannot take on additional credit until the debt review process has been completed or legally withdrawn.

If you’re currently under debt review, speak to your debt counsellor before considering further borrowing.

There Were Errors on Your Application

Small mistakes can delay or even prevent approval.

Always double-check:

  • ID number
  • Employment details
  • Income
  • Contact details
  • Banking information

before submitting your application.

Incorrect Information on Your Credit Profile

South Africa has several major credit bureaus, including:

  • TransUnion
  • Experian
  • XDS
  • Compuscan (now part of Experian)

If you believe incorrect information is affecting your ability to borrow, you can contact the relevant credit bureau to request a review or correction of inaccurate information.

You can learn more about your rights as a credit consumer on the National Credit Regulator (NCR) website.

Your Employment History Was Too Short

Some lenders prefer applicants who have been in stable employment for several months. If you’ve recently started a new job or have frequent changes in employment, a lender may decide to wait until you have a longer employment history.

Your Documents Were Missing

Missing or incomplete documentation can delay or prevent approval. Make sure you provide all requested documents, such as identification, proof of income and bank statements, when submitting your application.

Fraud Prevention Checks

Lenders carry out identity and fraud checks to protect both borrowers and themselves. If they cannot verify your identity or notice inconsistencies in your application, they may decline the loan until further information is provided.

What not to do if denied a loan

Don’t panic if you’ve been denied a loan; think before you act. Two things to avoid:

Don’t keep applying

Remember that applying for a loan or credit card creates a mark on your credit file that other lenders can view. Lenders expect you to browse around. A flurry of applications can appear eager for credit to a lender in a short period.

Don’t Apply to Multiple Lenders at Once

After a loan decline, it may be tempting to submit applications to several lenders immediately.

However, multiple applications within a short period can create several credit enquiries, which some lenders may view as a sign that you’re experiencing financial difficulty.

Instead, take time to understand why your application was declined, improve your financial profile where possible and compare lenders carefully before applying again. Our Compare Loans guide can help you review different lenders, loan features and eligibility requirements before submitting another application.

What to do if you are denied a loan

A loan denial gives you three options:

Before applying again, it’s worth reviewing the different types of personal loans in South Africa that may better suit your financial circumstances. Different lenders offer different loan amounts, repayment terms and affordability requirements.

  • Find a new lender (without firing off too many applications)
  • Rebuild credit and reapply later
  • Abstain from borrowing

Find a new lender

As previously stated, you must limit yourself to only a few more loan applications to protect your credit report. Before applying again, compare lenders carefully and only apply for products that match your income, affordability and borrowing needs.

Different lenders use different lending criteria. Some place greater emphasis on your credit profile, while others focus more heavily on affordability, income stability and your ability to comfortably repay the loan. Comparing lenders carefully can improve your chances of finding a loan that suits your financial circumstances.

Understanding how lenders assess affordability can also help you choose the right loan. Read our guide on how much you can borrow in South Africa before applying again.

Depending on your financial circumstances, another type of loan or a smaller borrowing amount may be more appropriate than reapplying for the same product immediately.

Borrowing from friends and family, credit unions, or remortgaging if you’re a homeowner are also options.

Rebuild your credit score and reapply later

Improving your credit profile takes time, but consistent financial habits can make a real difference. Paying your accounts on time, reducing existing debt, keeping your credit utilisation low and managing your finances responsibly may improve your creditworthiness over time.

You can learn practical ways to strengthen your credit profile in our guide to improving your credit score in South Africa.

What credit score is required for a personal loan?

It’s possible to get by without borrowing money at all. Maybe you have savings, or the purchase wasn’t necessary. You may also be able to buy it outright by delaying it for a few months.

Does a rejection of a loan affect your credit score?

Strangely, no. An unsuccessful credit application won’t influence your credit score because of the credit file records that you applied, not whether it was successful.

So don’t take this as a reason to keep applying for credit even if lenders have declined you.

How to Improve Your Chances Next Time

Although every lender has different approval criteria, there are practical steps you can take to strengthen future applications.

These include:

  • Improving your credit score
  • Reducing existing debt
  • Paying accounts on time
  • Applying for a realistic loan amount
  • Avoiding multiple applications
  • Keeping your bank account well managed
  • If you believe incorrect information is affecting your ability to borrow, you can contact the relevant credit bureau to request that inaccurate information be reviewed or corrected.
  • Comparing lenders rather than applying everywhere

Small improvements over time can significantly improve your chances of approval.

What Should You Do After a Loan Is Declined?

  1. Find out why your application was declined.
  2. Avoid submitting multiple applications immediately.
  3. Improve your affordability where possible.
  4. Reduce existing debt.
  5. Strengthen your credit profile.
  6. Compare lenders before applying again.

Steps to take after a loan application is declined in South Africa

Once you’ve identified why your application was declined and taken steps to improve your financial position, comparing lenders carefully can help you find a loan that better matches your circumstances.

Compare South African loan options after a declined application

Can You Avoid Having Your Next Loan Declined?

Although no lender can guarantee approval, there are practical steps you can take before submitting another application.

These include:

  • Checking that your application information is accurate
  • Applying for a realistic loan amount
  • Making repayments on time
  • Reducing existing debt where possible
  • Avoiding multiple loan applications within a short period
  • Keeping your bank statements well managed
  • Comparing lenders before applying

Preparing your application carefully can significantly improve your chances of approval while helping you avoid unnecessary credit enquiries.

Frequently Asked Questions

Why was my loan application declined?

A loan application can be declined for several reasons, including affordability concerns, a low credit score, high existing debt, insufficient income, missing documentation or lender-specific eligibility criteria. In South Africa, lenders must also comply with the National Credit Act (NCA), which requires them to ensure that a loan is affordable before approving it.

Does a declined loan application affect my credit score?

A declined application itself does not usually lower your credit score. However, the credit enquiry made during your application may appear on your credit report. Submitting multiple loan applications within a short period can make some lenders view you as a higher-risk borrower, so it’s generally better to understand why your application was declined before applying again.

How long should I wait before applying for another loan?

There is no legal waiting period, but it’s usually better to address the reason your application was declined before submitting another one. For example, you may need to reduce existing debt, improve your credit score, correct errors on your credit report or provide additional proof of income. Applying again immediately without making any changes may lead to another decline.

Can I get approved by another lender after being declined?

Yes. Every lender has its own lending criteria and risk policies. Being declined by one lender does not automatically mean every other lender will reject your application. Comparing lenders carefully and applying only when you meet their requirements can improve your chances of approval.

Can I get a loan if I have bad credit?

Possibly. Many South African lenders consider applications from borrowers with less-than-perfect credit histories. Approval usually depends on your overall affordability, current income, employment stability and ability to repay the loan rather than your credit score alone.

Can I find out why my loan was declined?

In some cases, yes. While lenders are not always required to provide a detailed explanation, they will usually tell you which credit bureau they used during the assessment. Speaking to the lender and contacting the relevant credit bureau, where appropriate, may help you identify the reason for the decline and what you can improve before applying again.

Key Takeaways

  • Loan applications can be declined for many reasons, including affordability, existing debt, poor credit history and missing information.
  • A declined application does not automatically mean you’ll be declined by every lender.
  • Avoid submitting multiple loan applications in a short period.
  • Improving your affordability and credit profile can increase your chances of approval.
  • Comparing lenders carefully before applying may help you find a loan better suited to your financial circumstances.

Conclusion

Having your loan application declined can be disappointing, but it doesn’t mean you’ll never qualify for credit.

In many cases, lenders decline applications because of affordability concerns, existing debt, missing information or lender-specific lending criteria rather than simply because of a poor credit score.

Before applying again, take time to understand what may have affected your application, improve your financial position where possible and compare lenders carefully.

Applying for a realistic loan amount, reducing existing debt and strengthening your overall financial profile can significantly improve your chances of approval over time.

If you’re ready to explore your options, visit our Compare Loans page to review trusted South African lenders and find loan products that suit your income, affordability and financial goals.